


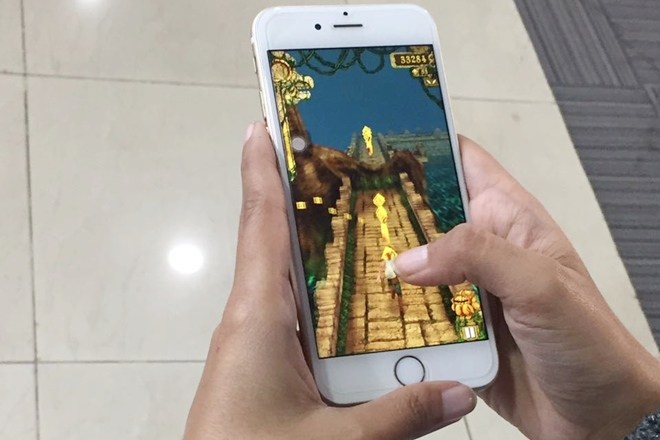
Whether it is Temple Run, Pokémon Go or Candy Crush, Clash of Clans and Monopoly, games and gaming apps are fun, a good way to entertain yourself, and surprisingly as it may seem, to financially educate yourself. Each of these super-addictive games offer insurance lessons that we sub-consciously imbibe. But what would Pokémon Go teach us about insurance, you would wonder? What can a simple game like Candy Crush, tell us about the importance and finer nuances of something as ostensibly mundane as insurance? Read on, you are about to take several jumps of financial understanding, much more than what you would in an engaging game of Temple Run!
Monopoly: Don’t buy just one property set, and the most expensive is certainly not the best!
We have all grown up playing the popular board game Monopoly, and as a kid, most of us had a certain liking for the ‘Park Lane-May Fair’ set. It fetched the maximum rent whenever any player came on the property. But, just getting that was not always enough to win. Similarly, buying the most expensive insurance cover need not be the best policy. Nor, is the most expensive insurance the best option. While term insurance plans provide maximum cover, and allow you to plan for long-term with low premiums, ULIPs are wealth creation instruments & provide dual benefits of protection and investment.
Traditional endowments that return money at the end of the policy term along with bonuses serve a different need. So, just like you would diversify and buy more property sets in Monopoly, it is better to buy more than one insurance policy – based on what you want to do. One size fits all doesn’t work.
Temple Run: Go for that magnet that helps you get regular returns and reduces your risk…there’s an added bonus too!
The best strategy to score well and meet most of your objectives in Temple Run is to get the magnet! After all, not only does the magnet automatically ensure a steady accumulation of coins – that would be required to make other purchases in the game – but, there is also the added benefit of filling up the bonus meter faster each time you get 400 coins.
Insurance plans are the magnet that allow you to hedge risks; some even give a steady stream of income (read coins). Add to that a bonus. You can opt for an insurance plan which has the feature of steady monthly income returns. While bonuses are mostly paid at the end of the policy, when the last payment is made, you can get an interim bonus as per the insurance company’s performance.
Clash of Clans: Be responsible and financially empower your family for life’s battles
The first thing that Clash of Clans sub-consciously teaches us, is to train the troops and be responsible for the ‘village’. In real life, it’s best to financially empower (read train) your family, in case of any eventuality. Insurance is bought for financial security.
There is nothing more assuring than protecting your family, in case something happens to you. Also, Clash of Clans champs will tell you that patience is the biggest asset in the game. So is the case with insurance. You may think yearly premiums are a waste – they are not! The day they count, they really count BIG.
Pokémon Go: Search for the best ‘Pokémon’ add-on to make your insurance cover better
Catching Pokémons is a task, but catching the right ones, at the right time is an art – and that’s where the fun of Pokémon Go lies! Similarly, after buying insurance, it is important to keep ‘catching’ the right add-ons, based on your needs.
From accidental disability insurance to critical illness riders – you should make sure that you ‘catch’ the best Pokémon! For instance, an unexpected accident may affect your income and ruin your dreams. Ensure that your family’s lifestyle is not compromised even if you are unable to work due to disability & cover other risks specific to your family.
Candy Crush: Buy insurance when it is simple, and keep topping up as per need
The initial stages of Candy Crush are simple and easy to win. Just like it is less costly and easier to buy insurance, when young. As you move up the Candy Crush levels, your challenges rise, just like your liabilities tend to rise with stages of life. The best thing then is the flexibility to top up your insurance cover or switch from one to the other, something that ULIPs offer.
You can either top up your term insurance, or switch from equity to debt and debt to equity in ULIPs. The lesson, insurance once bought is not cast in stone. Many insurers allow you to increase insurance amount and purchase add-ons that protect you from new risks in that stage of life. You can also opt for add-ons like Critical Illness; this rider protects you from devastating expenses that come with a serious illness.
This article is sponsored by HDFC Life
Disclaimer: All product names, logos, and brands are property of their respective owners. All company, product and service names used in this article are for identification purposes only. Use of these names, logos, and brands does not imply endorsement. Photographic images are owned by their respective copyright owner.