


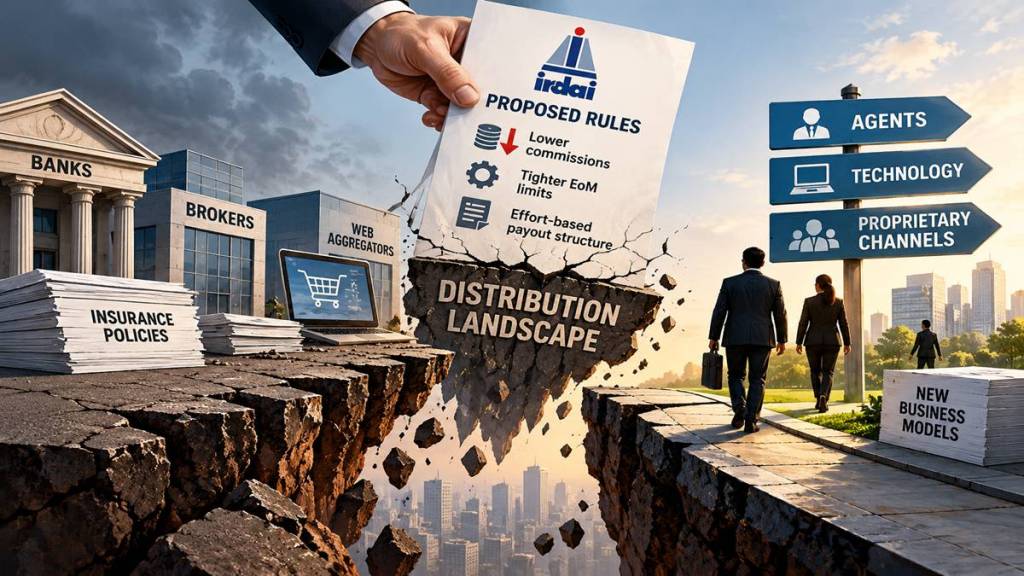

The Insurance Regulatory and Development Authority of India’s consultation paper proposing sharp cuts in insurance commissions and expenses of management (EoM) could trigger a major reset in the existing distribution landscape, forcing insurers to invest in technology & agent networks, while making some existing business models unviable, industry executives said.
“We may actually see the contraction in the life insurance business over the next 2-3 years because a lot of distribution will go out of business,” said the chief executive of a private life insurer. Irdai’s proposed effort-based commission structure seeks to differentiate payouts based on the effort involved in selling and servicing insurance. The draft, which favours agency distribution, proposes commissions of 6.25-25% of first-year premiums for life insurance agents, compared with 5-20% for other intermediaries such as brokers, bancassurance and web aggregators. For health insurance, commissions for distributors on first-time policies have been proposed at 15-20%.
“The non-agency channel is roughly about 50% of the business today. Of that, about 65-70% is banks and 30% is others. The 30% others’ share could completely evaporate,” the above-quoted life insurer said.
Emkay Research said the proposed distribution reforms would push the insurance sector into “uncharted waters”. While the intent behind the reforms could be to address the root causes of mis-selling and make insurance more affordable, the sharp reduction in distribution commissions could make insurance distribution unviable and the profession less attractive, it said.
“This proposal pushes the sector in uncharted waters by almost cutting the oxygen (commission) supply to this ‘push sector’,” Emkay said.
A bank-backed private life insurer described the proposed changes as a “tectonic shift”, saying insurers would need to reassess the assumptions underpinning their existing business models.
“We all have to go back to our shareholders. We have to go back and understand the basics of the business when we started. What were the assumptions of these models?” the executive said, adding that insurers also have only two years to comply with the Expenses of Management (EoM) framework.
Bancassurance entities account for around 45% of the total premium of private life insurers and receive an average commission of 10% of total premium, including new and renewal business. In general insurance, bancassurance entities account for around 5% of premiums but receive an average commission of 26%. In contrast, agency and broker channels together generate around 63% of premiums while receiving a substantially lower average commission of 17-18%.
“The bancassurance channel therefore emerged as one of the costliest channels for insurance distribution. Rather than translating into lower costs or better outcomes for customers, the significant customer access available to bancassurance entities appears to be contributing to the maximisation of commission income,” Irdai said.
However, insurers said replacing business that could be lost from non-agency channels would require significant investment in proprietary distribution channels. “If 30% of the institutional business goes away, we will have to invest in proprietary channels, but in the initial years, the proprietary channel is also EoM negative,” an insurer said.
Jefferies, however, sees the proposed changes as broadly neutral for insurers but negative for distributors such as PB Fintech and Turtlemint.
The proposed commission structure could reduce new-business commissions for health and term insurance by at least half and commissions on new motor own-damage policies by around a third, Jefferies said. “We see this as a risk for distributors like PB Fintech and Turtlemint, noting a 10% cut in new business commission rates translate to a 10-12% fall in their earnings,” Jefferies said.