


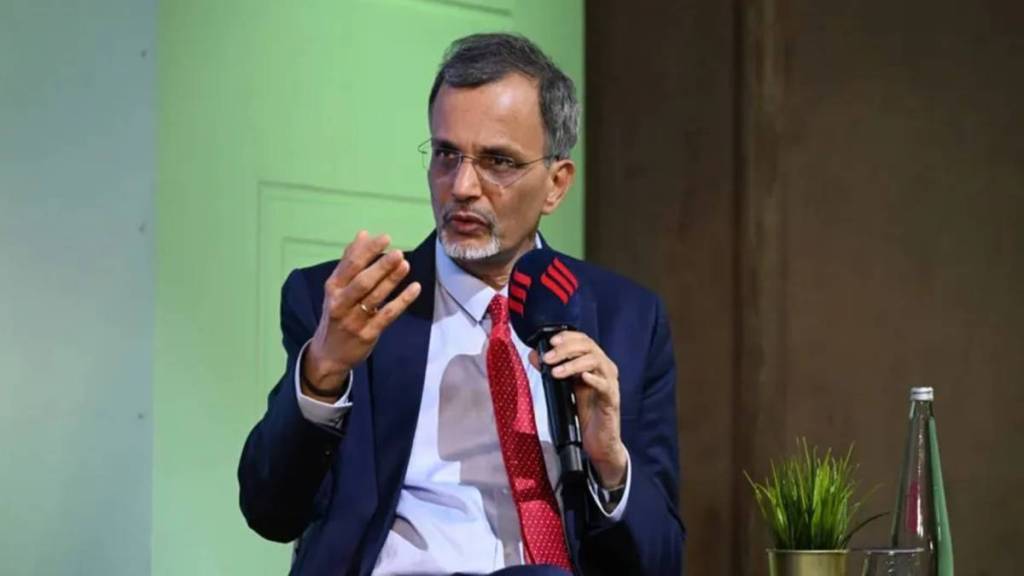

India’s recent Foreign Currency Non-Resident (Bank), or FCNR (B), mobilisation was a “fortuitous case of timing”, as banks would not have been able to mobilise deposits on the same terms had the exercise taken place amid the latest spike in global yields, Chief Economic Advisor V Anantha Nageswaran said on Friday.
Speaking at the PAFI Annual Forum here, he said rising bond yields in developed economies reduce the incentive for investors to take emerging-market risks, potentially putting pressure on countries dependent on global capital flows, he said.
Banks mobilised $133 billion during June-August under the Reserve Bank of India’s special Foreign Currency Non-Resident (Bank), or FCNR (B), deposit scheme, aimed at beefing up forex reserves amid rupee weakness and fund outflows.
“Suppose we were doing the FCNR deposit mobilisation now, we wouldn’t have gotten what we got in the previous three months after this kind of interest rate increases,” Nageswaran said, describing the earlier mobilisation as a “fortuitous case of timing” because it took place before the latest spike in interest rates began to unfold.
He said the higher yields in developed economies could make investors less willing to deploy funds in emerging markets, where they face additional exchange-rate, legal and compliance risks.
This could pose a challenge for emerging economies such as India that rely on global capital flows. Nageswaran said investors continue to demand a higher return for taking emerging-market risk, even as the interest-rate gap with developed economies has narrowed.
He said markets could take time to recognise the changing risk landscape, creating pressure on capital mobilisation in the near term. “There will be a gap before the market realizes” that the risks associated with developed-country debt have also increased, he said, adding that “markets take time to adjust to new realities.”