


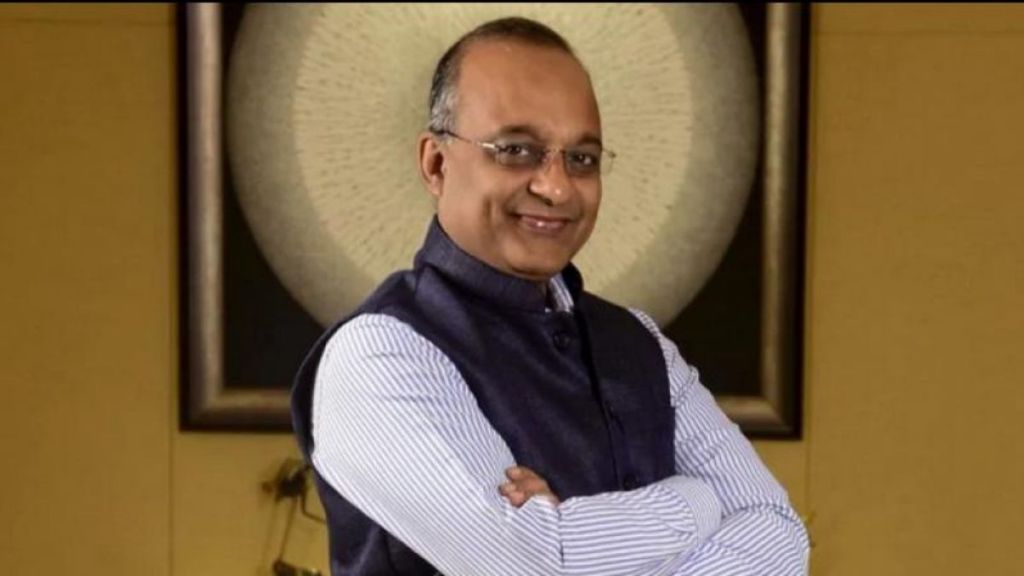

Sashidhar Jagdishan’s decision not to seek a third term at the helm of HDFC Bank, announced on Saturday, has the outward form of a graceful exit. The board says it tried to persuade him to stay and that he would not be moved. He retires on October 26, two months from now, after six years as managing director and chief executive. On paper, this is the kind of voluntary, calendar-bound departure that well-run institutions are supposed to produce. The trouble is that nothing about HDFC Bank’s year has been orderly, and the timing makes it hard to read this as a purely personal choice.
As recently as March, Jagdishan told an interviewer he was “willing and raring to go” for another term. Between that statement and Saturday’s filing lies a bruising stretch: the abrupt resignation of chairman Atanu Chakraborty over practices he said conflicted with his personal ethics; an external legal review that found nothing to substantiate his concerns; and an internal inquiry into the bank’s dealings with a state public sector undertaking that concluded the episode amounted to overreach rather than malfeasance, yet still ended with warning letters and token penalties for three senior executives, including the chief executive. Add a share price that has fallen more than a quarter this year and touched a 52-week low days before the announcement, and the picture is of a leader who chose to leave before the board or the regulator had to decide whether it wanted him.
That may well be the right outcome. But it exposes a failure of process that shareholders should not wave through. The Reserve Bank of India (RBI) expects lenders to apply for a chief executive’s reappointment, or to submit fresh names, six months before the incumbent’s term ends. For Jagdishan, that deadline passed in April. Three years ago, the board had cleared his current term with seven months to spare. This time, management was still describing succession as unfinished business on the earnings call the very day he bowed out. A bank of this size, with an interim chairman whose own tenure has had to be extended by the RBI, has now given itself eight weeks to identify, vet, and secure regulatory approval for a new CEO. That is not fast-tracking; it is scrambling.
None of this diminishes what Jagdishan achieved. He steadied the bank in the long shadow of Aditya Puri, absorbed the RBI’s digital embargo in his first years, and executed the enormously complex merger with HDFC Ltd, among the largest in Indian corporate history, without the balance-sheet accident many had feared. The deposit-led recalibration that followed was unglamorous and, on the numbers, largely successful. The board is right to record its appreciation of his substantial contribution to the bank, which he joined three decades ago as a finance manager. However, good leadership is sometimes about recognising when the interests of the institution are better served by making way.
The lesson lies elsewhere. Private banks in India are widely held; there is no promoter to steady the ship when the captain steps off. The board and the regulator are the only guarantors of continuity, and this board let the succession question drift through a year in which every signal suggested it could not afford to. Investors have absorbed enough surprises from HDFC Bank this year. They deserve, at minimum, a transition that is planned rather than improvised.