


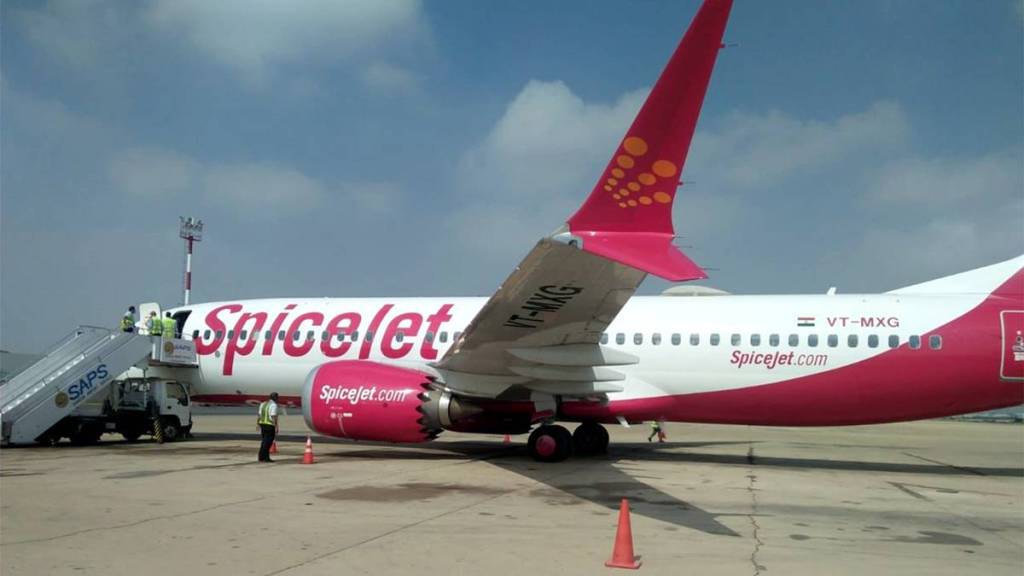

SpiceJet has once again been given breathing space, but the latest National Company Law Tribunal (NCLT) reprieve should not obscure the more difficult question facing the government: how long can a financially distressed airline be kept going without a credible path to recovery?
The tribunal’s decision last week to rehear the remaining insolvency petitions, after lessor Aviator ML withdrew its case following a settlement, avoids an immediate insolvency proceeding. That may be welcome for an airline whose failure would further concentrate the aviation market.
But SpiceJet’s problems are no longer simply a temporary liquidity squeeze. Its domestic market share plunged to 1.6% in July, its lowest since 2014. An airline that once commanded more than a fifth of the domestic market has been reduced to a marginal player. The latest NCLT development thus buys time; it does not answer whether there is enough of a business left to revive.
SpiceJet’s crisis has been building for years. The grounding of its Boeing 737 MAX fleet in 2019, followed by the pandemic, badly damaged its finances and operations. What followed was a vicious cycle: a shortage of operational aircraft reduced capacity and revenue, while inadequate cash prevented the airline from paying lessors, vendors, and maintenance providers.
Fund-raising, settlements, and restructuring have periodically provided relief, but the recurrence of lessor disputes and insolvency petitions shows that the underlying balance-sheet problem has not been resolved. There have been signs of an operational recovery, but they have not translated into a sufficiently strong business. An airline cannot indefinitely rely on settlements with creditors and fresh capital to bridge the gap between its costs and its ability to generate cash.
There is also a peculiar problem with airline insolvency that the government cannot ignore. Unlike a conventional company, an airline may not own the assets that make it an airline. Aircraft are often leased; routes are not conventional property; and slots and other operating rights depend on regulatory and operational continuity.
Go First demonstrated the difficulty. Once its lessors were able to recover aircraft during the insolvency process, the prospect of preserving the airline as a going concern became increasingly difficult. SpiceJet’s creditors include aircraft lessors, making the dilemma even sharper: an insolvency process may protect creditors’ rights but could simultaneously strip the airline of the assets needed to revive it.
Yet avoiding insolvency indefinitely is not a solution either if the airline cannot generate enough cash to meet its obligations and sustain operations. The government has a legitimate reason to want SpiceJet to survive. A market dominated by a few large carriers is hardly desirable, and the disappearance of another airline would affect employees, regional connectivity, and competition. But preserving competition cannot mean preserving an airline at any cost.
Financial stress in aviation also deserves closer regulatory scrutiny because the consequences can extend beyond shareholders and creditors to employees, suppliers, and passengers. Safety, of course, must remain non-negotiable, irrespective of an airline’s financial condition.
What SpiceJet needs now is not another open-ended reprieve but a credible, time-bound recovery plan backed by capital and a demonstrable ability to rebuild its fleet and meet its obligations. The NCLT can decide whether the airline enters insolvency. The government must decide what it is trying to preserve. If the objective is a viable competitor, then SpiceJet needs to demonstrate that viability. Otherwise, repeated postponement risks turning a difficult rescue into a much larger reckoning later.