



The long arm of justice can move slowly — often requiring deep pockets and a multi-year court battle. But for a growing class of specialised investors, – litigation can also present a high risk, yet golden, investment opportunity. Litigation funding has emerged as a nascent investment class where a third party pays some or all of the costs for a lawsuit in exchange for a return linked to the eventual financial recovery.
Kingshuk Banerjee, a disputes partner at Khaitan & Co defines it from a funder’s point of view as “an investment into a litigation”. While India has no dedicated statutory or regulatory framework governing third-party litigation funding, the practice is not expressly prohibited when undertaken by non-lawyer third parties. And the government has also confirmed in Parliament that it currently has no proposal to create a dedicated framework for third-party litigation funding.
A third party financier can approach a litigant and offer to pay the costs incurred — to pay lawyers, gather evidence, brief experts etc. If the plaintiff succeeds and recovers money at the end of the case, the investor is repaid the amount funded along with the agreed return on their investment, Banerjee explains in layman terms.
‘A $65 billion industry by 2030’
The concept began primarily as a niche form of financing for parties that could not afford the costs of litigation before developing into a global, multi-billion-dollar asset class. Law firms in the United States or UK have now grown increasingly comfortable using investments from third parties to pay the cost of lawsuits. In India, however, it remains at a nascent stage, with limited checks and legal safeguards.
“Legal finance is a large and growing global industry, expected to reach a global market size of around $64 billion by 2030. In the UK, US and Europe it’s a well-established asset class,” Pratyush Miglani, Investment Advisor at ELF Partners, told Financial Express Digital.
He noted that a report by Maharashtra-based Market Research Future projected a “compound annual growth rate of 9.62% during the forecast period 2025 – 2035”. The analysis published last year estimated that the litigation funding investment industry would grow from $23.58 billion in 2024 to $64.76 billion by 2035. MRFR cited rising litigation expenses, increasing corporate willingness to outsource legal financing, and growing awareness of the benefits of third-party funding as key reasons for this growth.
A report by financial services company Burford Capital also added that “reported use of legal finance has doubled in recent years” — while acknowledging that many still lacked direct experience or needed more understanding about the process. The Indian side of this, Miglani acknowledges, is “still at a very early stage” and “may not even reach 1% of this” growing global figure.
Market still finding its feet in India
Litigation funding currently remains a niche inquiry rather than a mainstream tool for India’s top law firms. It is also largely a foreign interest — with Miglani noting that a good part of the work at ELF Partners currently “involves educating both claimants and potential investors about how the product works”.
“We do receive a limited number of inquiries regarding third-party funding options. These arise primarily from foreign clients, particularly those involved in cross-border disputes. Such clients tend to be more familiar with third-party funding as a concept, given that it is well established in jurisdictions like the United Kingdom, Singapore, and Hong Kong,” said Ila Kapoor, Partner, Shardul Amarchand Mangaldas & Co.
She adds that such ‘investors’ typically approach SAM to understand the current legal position in India, the permissibility of such arrangements under the law, and whether funders are actively operating in the domestic market. What’s missing, Kapoor argues, is a legislative foundation for such an alternative investment fund.
India has only one SEBI-registered Alternative Investment Fund dedicated to legal and litigation finance called ‘5 Rivers Capital Fund I. Many others operate as tech platforms, corporate aggregators, or private networks — often working on a case by case basis without regulatory oversight.
“Several jurisdictions such as Singapore and Hong Kong have enacted statutory frameworks governing third-party funding. India currently lacks an equivalent legislative foundation, and similar statutory recognition would provide clarity to parties and third-party funders operating in India, as regards aspects such as- which proceedings qualify for third-party funding, disclosure requirements, management of conflicts of interest, setting down qualifications for third party funders and valid agreements for funding,” Kapoor reiterates.
The practice has, however, received judicial recognition. In a 2018 judgment, the Supreme Court noted that there appeared to be no restriction on non-lawyer third parties funding litigation. In 2023, the Delhi High Court, while dealing with third-party funding in an arbitration dispute, described such funding as important for access to justice and said transparency and disclosure rules would be necessary.
Growing interest in India
Miglani notes that roughly 70% to 80% of the current mandates received by ELF Partners are “global and unconnected to India”. These are typically meritorious claimants or companies with recoveries due in a different jurisdiction — such as a foreign-seated arbitration with enforcement abroad. Approximately 20% of the cases are India-linked and mostly commercial disputes. He explains that the company currently receives “at least two inquiries a week for legal finance” with the number “rising quarter over quarter” as awareness spreads.
Delhi-based LegalFund told Financial Express that it puts money “behind a fairly wide range of matters” and has “committed or deployed meaningful capital across more than 100 matters in India”. The technology-backed litigation firm sees significant growth potential in the “underserved mid-market segment” — with its portfolio spanning unpaid invoice recovery, commercial suits, MSME disputes, arbitrations, National Company Law Tribunal proceedings, intellectual property disputes, and decree or award enforcement.
Advocate Amarendra Kumar Dubey, Senior Legal Advisor at LegalFund added that over 50 such matters have already been resolved while 20-30 are still working their way through courts, tribunals, or arbitral panels. The company advertises a Rs 5 crore funding cap per case, with a “bias toward larger commercial disputes where funding economics make sense”.
“LegalFund generally looks for commercial claims worth roughly Rs 50 lakh or more in realistic recovery value. Smaller claims can still get funded if liability is clear-cut, the odds of recovery are good, or several smaller claims can be bundled into one portfolio. Decree and award enforcement cases don’t have a minimum size at all — each is judged on its own merits, largely based on whether the judgment debtor’s assets can actually be located and seized. For invoice disputes and IP cases, the funding typically needed runs around 25–30% of the claim’s value,” said Dubey.
Building a deal
Both Miglani and Dubey laid heavy emphasis on the need for a detailed assessment before a funding opportunity is selected. For ELF Partners, founded as a legal finance consultancy out of Singapore in 2019, this involves a three pronged approach:
- Legal merits is an underlying assessment of the legal issues in the matter and how strong the claim actually is
- Quantum analysis looks at what’s at stake, whether the claimed losses are backed by evidence, and how well the claimant can prove damages.
- Asset tracing and enforcement matters because recovery ultimately depends on where the respondent’s assets are located and how straightforward or difficult enforcement will be in that jurisdiction.
“The time factor is a key point of concern. The judiciary and judicial system in India can be somewhat unpredictable. So that’s a major uncertainty……time factor is one problem….it could become an open-ended investment that goes on for years. The returns on the investment would also become a key concern,” warned chartered accountant Sunil Arora.
“Duration risk — the time value of money — is the single biggest risk in this business, which is why our upfront assessment needs to be robust and the budget has to be held to. Costs can run higher, particularly where enforcement lands in a difficult jurisdiction, and most litigation funding agreements now build in some contingency for that scenario based on industry experience,” Miglani added.
Two third-party litigation funding companies told Financial Express that the structure can vary widely from case to case. Funders are connected to claimants once the suit clears review — with potential investors chosen on the basis of their risk appetites, regional focuses and industry specialisations. Miglani said some of these investors focused only on class actions, others prefer loss-of-profits cases, others specialise in investment treaty arbitration.
“We also work with well-capitalised companies who want to use legal finance to reduce the burden of legal costs and the reserves they’d otherwise have to hold. We’ve arranged working capital for existing projects at such companies, collateralised against claims and awards they hold — effectively treating litigation as an asset that can be collateralised to raise capital, usable both for the legal matter itself and for broader working-capital needs,” he added.
“The process typically starts when a claimant sends LegalFund the details of their case along with supporting documentation. The platform then evaluates the matter on things like the strength of the legal argument, the quality of the evidence, how much the claim is worth, what it will cost to pursue, how long it’s likely to take, the financial standing of the other side, and — critically — whether recovery is actually realistic even if the case is won. Cases that pass this screening go through deeper legal and financial due diligence, after which both sides sign a funding agreement covering the funding cap, which expenses are covered, how money will be released, how returns are structured, reporting requirements, and how any settlement will be handled,” LegalFund summed up.
Dubey adds that money can go towards lawyer and counsel fees, court or arbitration fees, paperwork and documentation costs, expert witness fees, asset-tracing work, enforcement costs, and other pre-approved expenses. The claimant remains the actual party in the case with their own legal team — the funders are not directly involved in the legal proceedings.
“Claimants don’t pay anything upfront, and if the case doesn’t succeed, they owe nothing back — the capital that’s deployed covers legal fees, expert costs, and enforcement expenses. On the investor side, approved cases are packaged as investment opportunities with information about the nature of the claim, the risks involved, and the potential upside,” he said.
What does the payout look like?
LegalFund told Financial Express that returns depend significantly on the merits of the underlying case — with “high returns come less from taking a large percentage share and more from how quickly a case resolves”. Dubey outlined gross returns of about 12% to 18% on a year-to-year basis. The average time typically ranges from over 24 months to about 30 months.
Meanwhile, global-focused ELF Partners noted that the returns sought by investors would depend entirely on how long the litigation takes. Miglani hypothesised that if money was locked in for three years, investors would “at the minimum want 4x the invested capital”.
Arora however struck a cautionary note when asked about the potential returns — noting that a 12% to 18% return may not be lucrative for most investors in such a high-risk environment. The founder partner of Sunil Arora and Associates noted that the outcome remained uncertain, with no way to ‘ensure’ the legal outcome was successful.
“To my mind…I would not risk my money. 12% to 18% is no return to be risking for this kind of an investment. It becomes even more concerning when I talk about ‘double in one year’ or 3x in 3 years…to have that kind of a number. The litigation and returns may not get concluded in 2 or 3 years. Another downside of this sort of investment is that you don’t have any assets that are getting created…unless and until you get a positive outcome for the case,” he reminded.
India’s litigation finance market has few clear success stories
Miglani outlined a more nuanced (but unwritten rule) followed by the industry: the funding funding budget shouldn’t exceed roughly one-tenth of the claim’s total value. To give an example, the budget would typically stay under $1 million for a $10 million claim. This would cover the legal fees, cost of arbitration, court fees, cost of experts as well as the cost of defending set-aside proceedings and cost of enforcement proceedings.
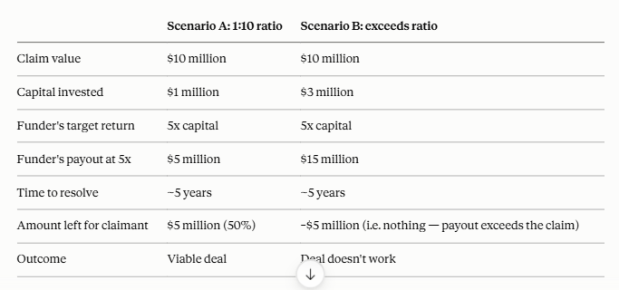
“Funders themselves are highly selective — typically reviewing around 100 opportunities and funding two…There’s no single reason matters don’t get funded, and no pool of individual “applicants” in the crowdfunding sense — each funded matter is backed by one funder or a small syndicate. Where a matter is funded, the payout is typically structured as a multiple of the invested capital rather than a percentage of recovery,” he added.
But the judicial system can move slowly — especially in India where there was a backlog of around 54 million cases by the end of 2025. Kingshuk Banerjee noted that litigation could “go on for years” in Indian courts and that matters did not end by simply winning a case. Enforcement can often be a secondary challenge for the litigant — with third-party funders only benefiting after the actual payout. He explained that litigation funding was more common in arbitration cases, since there were clearer timelines and projections available. The lack of a clear regulatory framework could be another reason for fewer litigation funding cases in India.
“There are some funders now operating in India…many of them reach out to us and ask if there are any opportunities. But I haven’t personally seen a litigation funded case in India so far.” Banerjee clarified.
Miglani confirmed much the same issue in conversation with Financial Express: While there were success stories, these at best involved Indian claimants with recoveries happening abroad. He added that there were several cases making their way through the Indian courts after securing third party funding.
Not every investor’s cup of tea
Litigation funding is a non-recourse, high-risk asset class with a high cost of capital. If the claimant loses their case, the funder receives nothing at all. Put more simply, the investment can be zero or return five to six times the invested capital. As such, it has traditionally been the domain of seasoned institutional players.
ELF Partners said it counted many leading legal finance funders of the world among its clientele. The firm also works with “family offices and ultra-high-net-worth individuals who want to invest in this asset class directly” rather than investing through a fund. But it is not the recommended choice for the general public at this time.
“Family offices and UHNIs are increasingly interested in allocating a small slice — often 1–2% — of their portfolio to this asset class, partly to learn how it works and partly for the return potential. But we wouldn’t recommend this asset class to a layman investing directly. Anyone without that risk appetite or expertise is better served investing through an institutional legal finance fund rather than a single opportunity,” Miglani warned.
LegalFund has meanwhile found a way to ‘spread’ the risk by building tailored portfolio funding arrangements. Dubey argues that bundling claims this way spreads risk across the portfolio and gives more flexibility than funding each matter separately.
Regulatory void in India
Litigation funding exists in a somewhat grey regulatory space in India. Only one fund is presently registered with SEBI and there are no clear laws governing the space. There is also no specific provision in the Indian Income Tax Act that deals with such investments. Miglani reveals that a common query — even from practicing lawyers — is whether this set up is “even legal”.
“India’s litigation funding market is growing quickly, but there’s still no dedicated regulatory framework governing it. On top of that, court proceedings and the enforcement of judgments or arbitral awards can drag on longer than expected, which stretches out the timeline for any investment,” noted Dubey.
Kingshuk Banerjee noted that court challenges in India could drag on for years — with additional uncertainty coming from its legal positioning. He also noted that there was some debate as to whether it was permitted under the Contract Act, since one couldn’t ‘gamble’ on a legal outcome. Success fees for lawyers are not permitted in India, although an established practice in some parts of the world.
“At present, there is no proposal under consideration of the Government for establishment of a legal and regulatory framework to facilitate Third Party Funding of litigation in the country and further, no examination of the potential of Third Party Litigation Funding as a means to address high litigation costs and pendency of cases has been carried out by the Government,” Union Minister Arjun Ram Meghwal told Parliament in February 2025.