


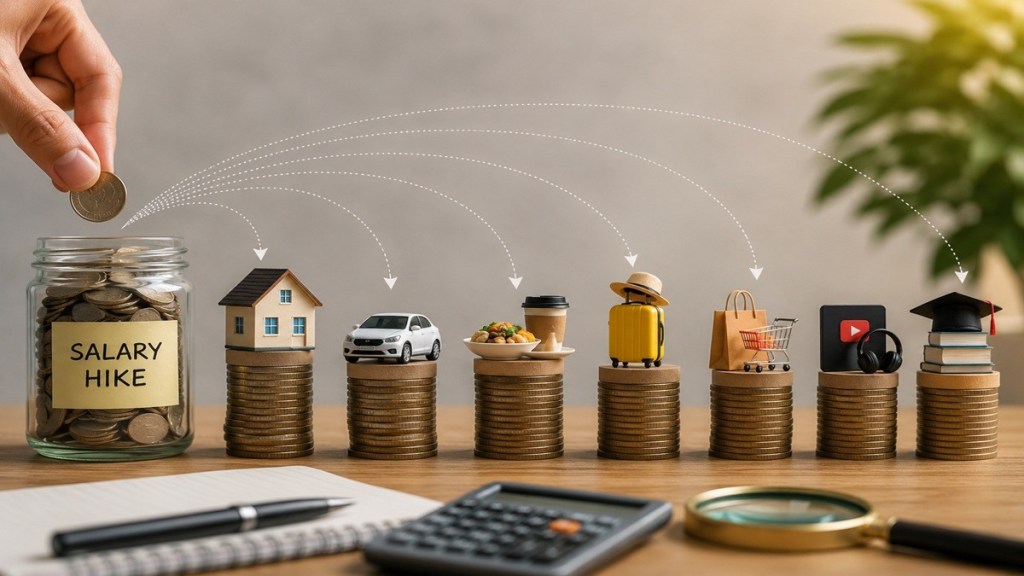

For many salaried employees, the 2026 appraisal cycle is already over, and the salary hike has probably started showing up in their bank accounts.
A double-digit increase should, in theory, mean more money available for savings and investments. But that is rarely how it works. A better house starts looking affordable. The car upgrade suddenly seems within reach. Dining out becomes more frequent, weekend trips increase and subscriptions and gadgets quietly add to the monthly bills.
By the time the next appraisal cycle arrives, the salary is higher, but the amount left for investment may hardly have changed. This is how lifestyle inflation quietly eats into a salary hike.
Salary hikes in India are still happening at a decent pace. According to Aon’s Annual Salary Increase and Turnover Survey 2025-26, salaries in India were projected to rise by an average of 9.1 percent in 2026. The actual salary increase in 2025 was 8.9 percent. This survey was based on data from over 1,400 organisations across 45 industries.
However, a salary increase and a strengthened financial position are not the same thing.
If expenses rise at the same pace as income, a large portion of the salary hike simply goes toward funding a better lifestyle. Not much remains for investments, an emergency fund, or a retirement corpus.
This is the biggest issue with lifestyle inflation. It doesn’t arrive as a single, massive expense. Instead, it creeps in through small upgrades that gradually become your new normal.
What is lifestyle inflation?
Simply put, lifestyle inflation is the act of raising your spending level as your income increases. Previously, a Rs 1,000 dinner was considered a special occasion. Now, a Rs 2,000 dinner feels normal. Earlier, one holiday a year was enough. Now, two holidays seem essential.
Before, a Rs 30,000 smartphone sufficed. Now, a Rs 70,000 phone feels affordable given the salary.
None of these expenses are inherently wrong. It is natural to want to live a better life after earning more. The problem arises when a one-time lifestyle upgrade turns into a permanent monthly commitment. That is why, after a salary hike, the biggest question shouldn’t be, “How much more can I spend now?”
The question should be, “What portion of my additional income will strengthen my financial position?”
1. Housing and rent
The most significant and expensive form of lifestyle inflation is often seen in housing. As soon as the salary rises, many people feel they can move to a better locality or upgrade from a smaller home to a larger one. If the previous rent was Rs 30,000, a home costing Rs 40,000 or Rs 45,000 suddenly seems manageable.
However, housing costs go beyond just the rent. A larger home often entails higher maintenance, furniture, appliance, and electricity costs. If the new home is far from the office, commuting expenses may also rise. In other words, a single decision made after a salary hike can drive up various other expenses.
According to MoSPI’s Household Consumption Expenditure Survey 2023-24, the average monthly per capita consumption expenditure in urban India stood at Rs 6,996, with non-food items accounting for nearly 60 percent of urban consumption. While this figure does not directly prove lifestyle inflation, it highlights how large a share non-food spending already occupies in urban household budgets.
The biggest risk with housing is that it is a recurring expense. Once the rent or EMI increases, you are committed to that higher monthly outflow. Before upgrading your home after a salary hike, it is not enough to check if the EMI or rent fits within your current income. You must also consider whether this expense will lock up a large portion of your income before the next salary hike arrives.
2. Cars and commuting
Another major lifestyle upgrade involves the car. After a salary hike, opting for a car worth Rs 15 to 20 lakh instead of one costing Rs 10 lakh might seem easy. An EMI calculator might even show that the installment fits comfortably within your monthly income.
However, the true cost of a car extends far beyond the EMI. Fuel, insurance, servicing, parking, tolls, and maintenance also add up, and these costs can be significantly higher for an expensive car. If, alongside a salary hike, you have also moved into a larger home further from your office, your commuting expenses rise too. The decisions regarding your car and your housing are no longer separate.
This is a key aspect of lifestyle inflation: one expense leads to another. First, you upgrade your car. Then your fuel budget increases. Next, you go for more weekend drives. Then parking and maintenance costs go up. That is why determining a car’s affordability based solely on the EMI can be risky.
3. Dining out, food delivery, and convenience
The trickiest part of lifestyle inflation involves expenses that seem insignificant: Rs 250 for a coffee, Rs 500 for a food delivery order, Rs 2,000 for a weekend dinner, a cab to the office, an order via quick commerce. Viewed individually, none of these expenses seems large.
The problem arises from the frequency. If you used to dine out twice a month but start doing so every weekend after a salary hike, your annual expenditure rises sharply. Food delivery might have started as a matter of convenience, but if it becomes a weekly habit, it turns into a fixed part of your lifestyle.
Deloitte’s Consumer Signals India research (May 2026) indicates that Indian consumers are moving towards “calibrated consumption,” becoming more selective about discretionary spending. Even in travel, there is a shift from budget options to full-service carriers, upgraded seats, and superior hotels. People aren’t just spending more; they are willing to pay a premium for better quality and experiences. There is nothing inherently wrong with this, but turning every convenience into a permanent spending habit after a salary hike can lead to financial strain.
4. Travel and experiences
A few years ago, a single family holiday a year seemed sufficient. Now, weekend trips, staycations, concerts, international holidays, and premium hotel stays can all become part of one’s lifestyle.
Travel is an expense that is easy to justify: “I had been working too hard,” “I wanted to spend time with the family,” “I wanted to give the kids an experience.” These reasons may well be valid. The problem isn’t taking a holiday. The issue arises when a one-time luxury gradually becomes an annual financial commitment.
Suppose you used to spend Rs 50,000 a year on travel. After a salary hike, that figure rose to Rs 1.5 lakh. The following year, a budget of Rs 2 lakh began to feel normal. This isn’t just inflation. It is lifestyle inflation.
Deloitte’s 2026 research also found that while overall travel intent has softened slightly, those who do intend to travel are increasingly willing to pay more for comfort and reliability, with a growing preference for full-service airlines, upgraded seats, and premium accommodation. Rising income doesn’t just mean more trips. The average cost per trip rises too.
5. Gadgets, subscriptions, and digital lifestyle
This is perhaps the least visible form of lifestyle inflation. A new smartphone, then a laptop, then a smartwatch, then earbuds. Alongside these come OTT subscriptions, music apps, cloud storage, fitness apps, shopping memberships, and food delivery subscriptions. A monthly subscription of Rs 299 or Rs 499 doesn’t seem like much on its own.
But when you have several such subscriptions, the cost adds up. Spend an average of Rs 400 a month on five subscriptions and that comes to Rs 2,000 a month, or Rs 24,000 a year. Add a gadget upgrade or two during the year, and the total rises further.
A simple check: list all your subscriptions, add up the monthly cost, then multiply by 12. Seeing the annual total often reveals that these small expenses aren’t so small. The same applies to gadgets. Buying a new phone or laptop isn’t a mistake in itself, but if every new model starts feeling affordable simply because your salary has gone up, that is a sign of lifestyle inflation.
5. Children’s education and lifestyle spending
Lifestyle inflation isn’t limited to your own expenses. It becomes more complex when it comes to children. With a salary increase, parents may spend more on better schools, extra classes, sports coaching, foreign language and music classes, gadgets, and holidays.
Many of these expenses may be necessary, so it wouldn’t be right to call every additional expense on children lifestyle inflation. But one question can still be asked: should every child’s amenities be upgraded with every salary hike?
This is where emotional spending can creep in. If a parent spends Rs 10,000 more on a child, it rarely feels like just an expense; it feels like investing in the child’s future. Sometimes that is true. But in financial planning, it helps to separate need from aspiration: increasing the budget for a child’s education is one thing, upgrading every activity, gadget, and experience with every salary hike is another.
7. Personal care, domestic help, and convenience
Another form of lifestyle inflation is the steady pursuit of convenience. First a salon once a month, then a premium salon. First a basic gym, then a premium one. First a cab when needed, then a cab for every short distance. First a few hours of domestic help, then more.
These expenses make life easier, which is exactly why they’re difficult to reduce. This is where lifestyle inflation becomes invisible: you think you’re buying convenience, but every convenience adds a new line to your monthly budget, and once the new normal sets in, it’s hard to go back.
How much of the salary hike is actually saved?
Take a simple example. Suppose a person’s take-home income increases by Rs 20,000 a month. They don’t necessarily spend the entire amount, but lifestyle inflation might look something like this:
| New expense after salary hike | Additional monthly expense |
| Improved home / rent | Rs 5,000 |
| Car / commute | Rs 3,000 |
| Eating out and delivery | Rs 2,500 |
| Shopping and subscriptions | Rs 2,000 |
| Travel fund | Rs 3,000 |
| Personal care / convenience | Rs 1,500 |
| Other small upgrades | Rs 2,000 |
| Total | Rs 19,000 |
Source: MoSPI, HCES 2023-24
This is only an illustration, not an average household spending pattern. But the message matters: a salary hike of Rs 20,000 led to Rs 19,000 going into lifestyle, leaving only Rs 1,000 for investment. Income may have risen by 10 percent, but the pace of wealth creation did not rise anywhere close to that.
One-time expenses versus recurring expenses
The clearest way to see lifestyle inflation is to separate one-time expenses from recurring ones. A Rs 30,000 smartphone is a large expense, but it’s a one-time one. Rs 8,000 in additional rent, on the other hand, has to be paid every month, adding up to Rs 96,000 over a year. A Rs 20,000 holiday and a new Rs 20,000 EMI are not the same thing: the holiday spend is over once taken, while the EMI recurs every month.
This is why, after a salary hike, the first decisions to scrutinise are the ones that raise fixed monthly expenses. Once a fixed cost rises, a portion of the next month’s salary is already spoken for before it even arrives.
Spending more isn’t the problem, spending without a plan is
It isn’t wrong for a person who earns more to spend more. If income has increased, it’s natural to spend on a better home, better food, travel, or family experiences. Personal finance doesn’t require investing every salary increase while holding your lifestyle exactly where it was.
The real problem is when every extra rupee of income goes toward consumption. The salary rises, but the pace of financial freedom doesn’t. You can have a better car, a better house, and expensive holidays, but if the emergency fund stays weak, investment contributions don’t grow, and debt keeps climbing, the financial position is not as strong as the income alone suggests.
Deloitte’s 2026 Consumer Signals research suggests Indian households are not simply spending without a plan. The Financial Well-being Index stood at 111.1 in March 2026, up from 109.1 in March 2025. About 80 percent of consumers expressed confidence about upcoming payments, and 60 percent felt comfortable with their savings. In other words, Indian consumers are trying to balance saving and consumption, not abandoning saving altogether. The real issue is how incremental income gets used: does the next Rs 10,000 or Rs 20,000 go entirely into consumption, or does a portion also go into investments that strengthen your financial position?
A simple rule for salary hikes
There should be a simple rule for salary hikes: upgrade your lifestyle as your income rises, but not in the same proportion. If you receive an extra Rs 20,000 a month, that doesn’t mean the entire amount is available for spending. One possible framework:
| Where the extra income goes | Suggested share |
| Investments | Rs 10,000 |
| Lifestyle upgrade | Rs 6,000 |
| Emergency fund, debt repayment, insurance, or a specific goal | Rs 4,000 |
(Source: Illustration)
This isn’t a universal formula. Some people have home loans, others carry the cost of their children’s education, some are nearing retirement, and others are already in a strong financial position, so the exact split will vary. But the principle stays the same: after a salary hike, set aside money for the future first, then decide on the lifestyle upgrade. Do it the other way round, and expenses tend to rise first, leaving whatever is left over, often very little, for investment.
The real question a salary hike should answer
The real benefit of a salary hike isn’t that you can now afford an expensive phone or dine at better restaurants. Some lifestyle upgrades may well be necessary. What matters is asking, every year: has my income increased, has my lifestyle been upgraded, and, most importantly, has my financial strength grown as well?
If your salary rises by 8 to 10 percent annually but your investment contribution stays roughly the same, your income and lifestyle are both expanding, but your pace of wealth creation is lagging behind.
It may not be possible, or even necessary, to stop lifestyle inflation altogether. The key is to make sure the entire benefit of a salary hike doesn’t go solely toward lifestyle. A portion should improve your life today. A portion should secure it for tomorrow. The real advantage of a salary hike isn’t just a slightly more expensive life each year. It’s knowing that, a few years from now, your financial freedom has grown just as fast as your income.
Disclaimer: This article is for informational and educational purposes only and should not be considered personal financial advice. The examples used are illustrative and may not reflect the actual spending patterns of any individual or household. Readers should assess their own income, expenses, financial goals and risk profile before making financial decisions.
Every financial journey has a turning point. What’s yours?
Financial Express is launching a new series highlighting real experiences with money, investments, and the taxman. Did a sudden tax rule catch you off guard? Did a piece of financial advice change your life? Your story could provide invaluable, practical lessons for thousands of fellow taxpayers. Share your experience with us. We respect your privacy: no stories will be featured without a direct conversation and your full consent. Thank you.