



Nippon India Small Cap Fund is one of the oldest small-cap funds in India with a track record of nearly 16 years. Launched in September 2010 as the Reliance Small Cap Fund, the fund was rechristened Nippon India Small Cap after Nippon Life Insurance took over Reliance Mutual Funds in September 2019.
Today, this scheme commands the highest assets among all equity schemes from Nippon Mutual Fund. In fact, it’s the largest small-cap fund in India with assets under management (AUM) of over Rs 78,407 crore (as per the June 2026 portfolio).
Considering the size, the fund house has restricted inflows into the scheme, but investments are not prohibited entirely.
Currently, fresh lump sum investments and major switch-ins are not accepted (w.e.f. 7 July 2023). Only existing SIP/STP are permitted, and the fresh ones, from 22 March 2024, are restricted to Rs 50,000 per day, per permanent account number (PAN).
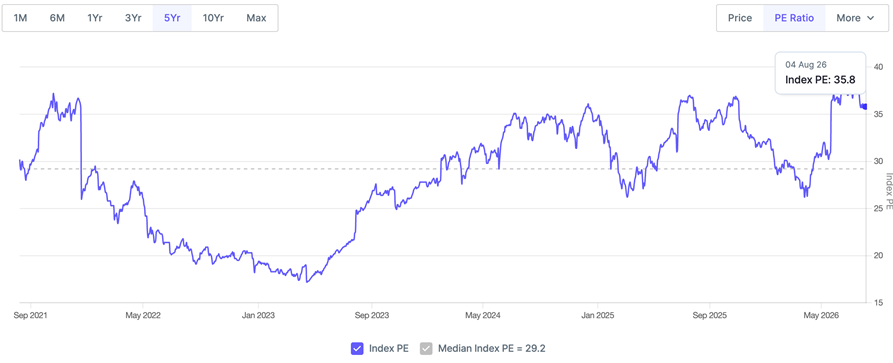
These restrictions have been put in place by the fund house considering valuations of the small-cap segment. The BSE 250 SmallCap Index is currently not far from its September 2024 peak, and the price-to-equity (PE) ratio of this index is at nearly 36x, higher than the 5-year median of 29x. This reflects that the fund house is conscious of the margin of safety.
BSE 250 SmallCap Index PE Moved Up Sharply After March 2026
Besides, given that the impact cost in small-cap investing is high (as trading volumes are thin in this market cap segment and buying or selling huge chunks of small-cap stocks drastically drives the prices up or down), and ultimately it affects existing investors, restricting inflows is a rational decision on the part of the fund house.
But despite this, the scheme continues to witness inflows from existing SIPs/STPs and the fresh ones (as per the present limit). It shows, first, investors’ affinity for the small-cap segment (given the wealth-creation potential it has demonstrated in the past), and second, their preference for Nippon India Small Cap for its impeccable long-term performance track record.
But has the fund delivered, and how has it fared recently over the short term?
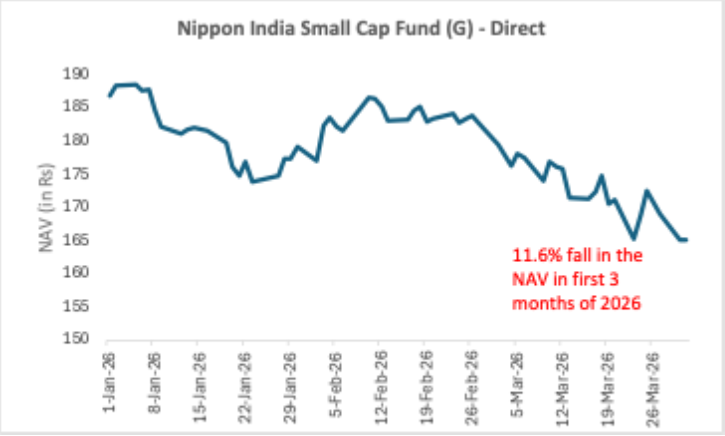
Like most other small-cap funds, Nippon India Small Cap Fund plunged during the period 1 January 2026 to 31 March 2026 – the period of simmering geopolitical tensions in West Asia. The NAV of Nippon India Small Cap Fund fell 11.6%, while the BSE 250 SmallCap – Total Return Index (TRI) dropped 15.2%.
This was because the war between the US and Iran escalated, oil was on the boil, Trump 2.0’s threw tariff tantrums, supply chains were disrupted, and a weak Indian rupee, among other factors, had a bearing on the Indian equity markets.
Returns of Nippon India Small Cap Fund from 1 January 2026 to 31 March 2026
In comparison, here’s the magnitude of the NAV fall registered by other top four small cap funds in India by AUM during the period 1 January 2026 to 31 March 2026:
HDFC Small Cap Fund = -14.3%
Quant Small Cap Fund = -13.3%
SBI Small Cap Fund = -12.6%
Nippon India Small Cap Fund = -11.6%
Axis Small Cap Fund = -11.1%
Nippon India Small Cap Fund’s drawdown was less compared to most of its peers.
During the period 1 January 2026 to 31 March 2026, the fund also made some changes in its portfolio. It made fresh entries or major additions in high-growth small-caps and specialised plays, such as Kaynes Technology India, Inox Wind, ICRA, and Genus Prime Infra, among a few others, and made a complete exit from Siemens Energy India from its non-core allocation, plus trimmed its position in ITC. These were conscious moves to manage risk and returns.
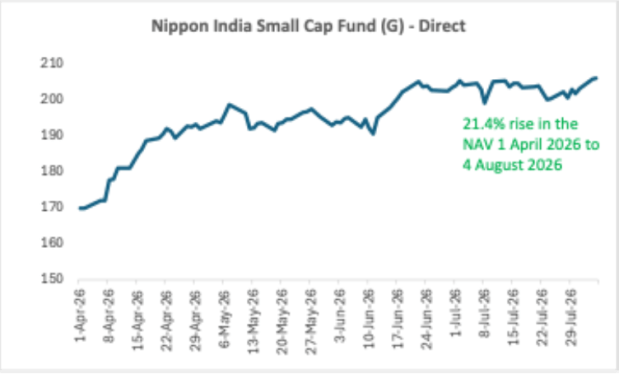
In the ensuing four months or so, i.e., 1 April 2026 to 4 August 2026, Nippon India Small Cap Fund’s NAV gained 21.4% on an absolute basis, while the BSE 250 Small Cap – TRI gained 27.3%.
Return of Nippon India Small Cap Fund Performance Since April 2026
On a relative basis, here’s how some of the comparable peers fared during the period 1 April 2026 to 4 August 2026:
Nippon India Small Cap Fund = 21.4%
HDFC Small Cap Fund (AUM Rs 40,417 crore) = 21.1%
SBI Small Cap Fund (AUM Rs 40,157 crore) = 23.2%
Quant Small Cap Fund (AUM Rs 33,739 crore) = 30.4%
Axis Small Cap Fund (AUM Rs 29,394 crore) = 24.3%
(Note: AUM is as per the portfolio as of 30 June 2026)
Barring Quant Small Cap Fund (which follows a very active, agile approach and momentum play), SBI Small Cap Fund, and Axis Small Cap Fund, Nippon India Small Cap Fund lagged a bit. This is mainly because of its over-diversified portfolio, which does not push returns in the short term as much as smaller schemes with a relatively compact or optimal portfolio.
That said, if we assess on a year-to-date (YTD) basis (from 1 January 2026 to 4 August 2026), Nippon India Small Cap Fund clocked a decent absolute return of 10.3% (as of 4 August 2026), while the BSE 250 SmallCap – TRI returned 7.9%.
Here’s how the other comparable peers fared on a YTD basis:
Quant Small Cap Fund = 13.2%
Nippon India Small Cap Fund = 10.3%Axis Small Cap Fund = 10.6%
SBI Small Cap Fund = 7.1%
HDFC Small Cap Fund = 3.8%
(Note: YTD returns as of 4 August 2026)
It shows that despite the market turbulence, Nippon India Small Cap Fund has rewarded investors well even in challenging times.
How has the long-term performance of Nippon India Small Cap Fund been?
The table shows that on long-term returns as well, i.e., over 5 years and 10 years—which is a reasonable horizon to invest in small cap funds—Nippon India Small Cap Fund has performed impressively.
Performance Across Time Periods
| Absolute | CAGR | ||||
| 6 Mths (%) | 1 Yr (%) | 3 Yr (%) | 5 Yr (%) | 10 Yr (%) | |
| Nippon India Small Cap Fund | 12.4 | 9.0 | 17.5 | 19.8 | 21.8 |
| Quant Small Cap Fund | 18.3 | 12.9 | 19.2 | 18.8 | 20.8 |
| Axis Small Cap Fund | 12.6 | 9.6 | 16.9 | 17.1 | 19.8 |
| HDFC Small Cap Fund | 5.3 | 2.5 | 13.8 | 16.2 | 18.5 |
| SBI Small Cap Fund | 11.8 | 6.7 | 12.7 | 14.6 | 19.2 |
| Category Median | 15.4 | 11.5 | 17.2 | 17.7 | 17.7 |
| BSE 250 SmallCap – TRI | 12.6 | 5.9 | 15.9 | 15.1 | 15.4 |
The returns data is as of 4 August 2026.
Category median calculated considering all small cap funds in the category and not merely the top five by AUM.
Source: Value Research
Over a 5-year and 10-year period, it has delivered a compounded average growth rate (CAGR) of 19.8% and 21.8%, respectively, outperforming its comparable peers, the entire category median, and the BSE 250 SmallCap – TRI (as of 4 August 2026).
In fact, the scheme has even outperformed the aggressively and dynamically managed Quant Small Cap Fund, which follows a short-term tactical rotation style with momentum play.
Nippon India Small Cap Fund has also outperformed the second- and third-largest small cap funds by AUM, i.e. HDFC Small Cap Fund and SBI Small Cap Fund, by a noticeable margin over both the 5-year and 10-year periods.
Risk Taken by Nippon India Small Cap Fund
| Risk Ratios | |||
| Std Dev (%) | Sharpe Ratio | Sortino Ratio | |
| Nippon India Small Cap Fund | 19.2 | 0.60 | 0.89 |
| Quant Small Cap Fund | 20.2 | 0.66 | 1.12 |
| Axis Small Cap Fund | 16.8 | 0.65 | 0.91 |
| HDFC Small Cap Fund | 17.5 | 0.44 | 0.61 |
| SBI Small Cap Fund | 17.2 | 0.41 | 0.62 |
| Category Median | 19.6 | 0.61 | 0.90 |
| BSE 250 SmallCap – TRI | 21.8 | 0.49 | 0.77 |
The Risk Measures have been calculated using calendar month returns for the last three years and are as of 31 July 2026.
Category median calculated considering all small cap funds in the category and not merely the top five by AUM.
Source: Value Research
What’s important is that the returns have been delivered by keeping risk (Standard Deviation of 19.2%) in check. The standard deviation of the scheme is lower than the entire category median, the aggressively managed Quant Small Cap Fund, and the BSE 250 SmallCap – TRI.
Thus, on a risk-adjusted basis, the fund has adequately compensated its investors, considering the Sharpe and Sortino ratios. It is almost in line with the category median.
Yes, the Sortino ratio is better in the case of Quant Small Cap, but it is mainly because of the hyper-active style that focuses on momentum and aggressive sector rotation, while Nippon India Small Cap Fund typically follows a buy-and-hold approach and a low portfolio turnover ratio.
Can the appealing returns be sustained?
To manage its large asset size of over Rs 78,407 crore, Nippon India Small Cap Fund holds a portfolio of over 250 stocks. In comparison, funds such as SBI Small Cap typically hold around 50–70 stocks, Axis Small Cap 100- 130 stocks, HDFC Small Cap 80–90 stocks, and Quant Small Cap 55–100 stocks. This stems from their deliberate mix of AUM scale, fund management, liquidity protection, and risk management strategy.
In its portfolio as of 30 June 2026, Nippon India Small Cap Fund has 251 stocks, with nearly 72% small caps and around 14% each in mid caps and large caps.
The top 10 stocks comprise only 14.4% of the total portfolio, and include names such as HDFC Bank, SBI, Karur Vysya Bank, Bharat Heavy Electricals, Apar Industries, and Zydus Wellness, among others.
Some of these stocks have a weightage of more than 1%, while stocks with an equity holding of less than 1% of the corpus account for 77.4% of the portfolio.
Banking & financials, capital goods/industrials, and consumer discretionary are the top 3 sectors, comprising around 54.0% of the total portfolio.
The capital goods sector has been a primary engine of wealth creation in Indian small-caps due to massive government capex. Similarly, the performance of banking & financial services (due to strong credit expansion, improving asset quality, and healthy net interest margins) has helped buoy up the returns.
At present, nearly 96.9% of the assets are in equities, and the remaining 3.10% are in cash & cash equivalents. The fund’s portfolio price-to-equity (PE) and price-to-book (PB) ratios are 29.0x and 3.6x, respectively, indicating a growth-oriented approach.
Nippon India Small Cap Fund Portfolio
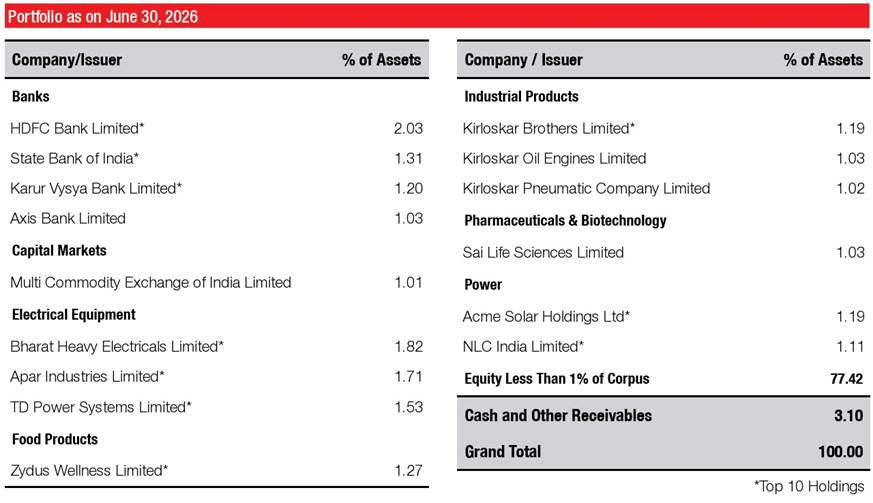
Source: Fund Factsheet
A point to note is that while this massive diversification helps smooth out idiosyncratic risks, it also causes “diworsification”—diluting the fund’s ability to generate extreme outperformance (alpha) compared to a more concentrated portfolio like Quant’s.
That said, so far Nippon India Small Cap Fund has prudently managed the portfolio, delivering appealing returns across time periods while keeping risk in check, thus generating efficient risk-adjusted returns.
This has been possible because the fund focuses on identifying good growth businesses with reasonable size, quality management and rational valuation. The investment approach adopts prudent risk management measures like margin of safety and diversification across sectors & stocks with a view to generate relatively better risk-adjusted performance over a period of time.
Overall, the fund has proved that its large asset size does not hinder performance.
What should you, the investor, do?
If you are already invested or have SIPs in this fund, it’s worthwhile continuing. The fund has proved that the size of its assets is not weighing down on the returns, and the risk is well managed.
Having said that, when investing, make sure you have a high-risk appetite and a time horizon of 7-10 years or more. In the current volatile market conditions, SIPs shall help mitigate risk (with the inherent rupee-cost averaging feature) and potentially help compound wealth in this fund. That said, make sure your allocation to small caps in general is not skewed. Invest as per the allocation best suited for you.
Invest sensibly, be a thoughtful investor.
Happy investing!
Note: We have relied on data from www.valueresearchonline.com, www.financialexpress.com, and the factsheets published by the respective fund houses throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
Returns data as of 4 August 2026. Direct Plan and Growth Option Considered. The Risk Measures have been calculated using calendar month returns for the last three years. The Risk Measures have been calculated using calendar month returns for the last three years and are as of 31 July 2026.
Standard Deviation is a measure of the fund’s total volatility. The Sharpe Ratio is a measure of risk-adjusted return that shows how much excess return an investment generates for each unit of risk taken.
Portfolio data as of 30 June 2026. The average of the price-to-book value ratios and price-to-equity ratios of all underlying stock holdings in proportion to their portfolio weights is considered.
Disclaimer:
Disclaimer: The above content is for informational purposes only. Mutual Fund investments are subject to market risks. Past returns are not indicative of future returns. Please consult your financial advisor before investing.
Rounaq Neroy has over 20 years of experience in the financial markets and investments. He is a close observer of the Indian economy and writes deeply on the capital markets, mutual funds, stocks, precious metals, asset allocation, wealth management, and investment strategy. His editorials provide interesting, actionable investment ideas to guide readers in the journey of wealth creation and make wise decisions. Rounaq was the Head of Content at PersonalFN (Quantum Information Services Pvt. Ltd.), which also owns Equitymaster.com – India’s oldest and trusted equity research house.