



UltraTech Cement Ltd. has launched its wires and cables business, Ultravolt, with a Rs 1,800 crore investment, giving the cement major a new product to sell into the same residential construction market where it already has a large distribution and dealer network. Analysts, however, don’t expect the new business to make a meaningful difference to UltraTech’s earnings immediately.
Their view is that Ultravolt can become a useful second growth business if the company can build distribution, utilisation and brand recognition, but cement will remain the main earnings driver for several years. Aditya Birla Group launched Ultravolt on September 3, 2026. According to the company’s launch announcement, the business is housed under UltraTech Cement, backed by Rs 1,800 crore of investment, and starts as the second-largest player in the wires segment by capacity. It aims to become one of the top two players in the segment within five years.
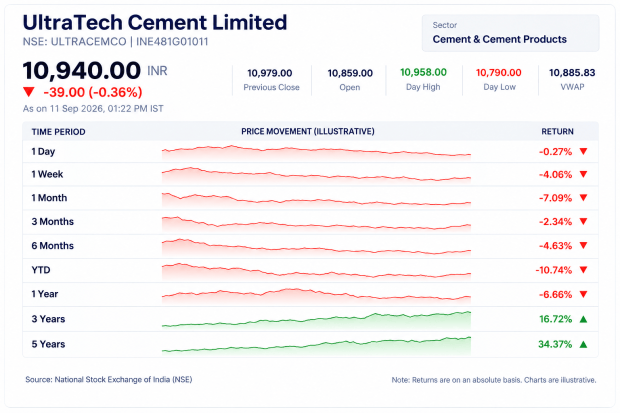
UltraTech Cement share price performance
UltraTech: Analysts see Ultravolt as a long-term earnings opportunity
The first point analysts make is about scale. The Rs 1,800 crore cable investment is relatively small when compared with UltraTech’s cement expansion programme, which means Ultravolt isn’t expected to alter the company’s consolidated earnings profile in the near term.
Akshay Shetty, Research Analyst at Mirae Asset Sharekhan, said, “C&W investment of Rs 1,800 crore versus much larger cement investment. Cement capacity at 200 MTPA with further expansion, so cement remains the dominant earnings driver.”
Shetty also said, “Strategic rationale is increasing the share of the construction-material wallet, particularly residential. Initial consolidated earnings impact small.”
That makes the immediate financial effect fairly straightforward. UltraTech gets a new business with the potential to add another earnings stream, but its cement operations remain much larger and continue to receive the bulk of the company’s expansion capital.
According to UltraTech’s July 2026 investor presentation and earnings disclosures, the company had 205.5 MTPA of total cement capacity, with domestic grey cement capacity at 200.1 MTPA. It has about Rs 17,000 crore of projects under execution for capacity growth over the next 2 to 2.5 years.
| Ultravolt launch | Company disclosure |
| Investment | Rs 1,800 crore |
| Wires capacity position | No. 2 |
| Retailer target | 1 lakh+ |
| UBS outlets | 5,000+ |
| Initial districts | 500+ |
| Initial pin codes | 6,000 |
Distribution network could give Ultravolt big advantage
Analysts see UltraTech’s existing distribution and customer relationships as one of the main reasons the cable business has a credible starting point.
Sanjeev Kumar Singh, Senior Vice President, Institutional Equities, Cement at Motilal Oswal Financial Services, said, “Brand recognition, UBS network, B2B relationship, access to end users/influencers provide ‘right to win.’ Higher wallet share opportunity. Building Product Division stages design, construct, enable, decorate, and service. The company already offers 90 SKUs in construction materials. C&W strategic fit. 85% wire consumption residential, 65% cement demand residential.”
The company is also planning a national rollout rather than building the network gradually across individual regions.
Dilip Gaur, Director, Ultravolt, said at the September 3 launch, “We are venturing at pan India scale rather than testing the market region by region. Our plan is to reach more than one lakh retailers and further activate availability through over 5,000 UltraTech Building Solutions (UBS) outlets. An ambitious rollout across more than 500 districts and 6,000 pin codes to begin with, reinforces our commitment to growth and innovation.”
Gaur added that the new manufacturing facility, more than 20 warehouses, channel relationships and UltraTech’s existing relationships with individual home builders, contractors, real-estate developers and engineering, procurement and construction companies would give Ultravolt a platform to scale.
The company has also started building an electrician network. According to the September 3 launch announcement, more than 1,600 electricians had been onboarded before launch, with a target to train more than 40,000 electricians over the following year.
Ultravolt: Early profitability may remain under pressure
The analysts’ expectation is that Ultravolt’s initial years will involve spending ahead of the full revenue opportunity.
Singh of Motilal Oswal said, “Ultravolt likely aggressive around capacity utilisation, distribution expansion, dealer acquisition, brand building. Initial management investment of Rs 1,800 crore, ramp capacity and optimum utilisation by FY31/32. Initial profitability could be lower due gradual ramp-up, marketing/promotional spending, brand building.”
UltraTech’s management has separately indicated that the business will need additional working capital while inventories are built up.
Atul Daga, Chief Financial Officer of UltraTech Cement, said during the July 20 Q1 FY27 earnings call, “So initially we will have a higher working capital because we have to pile up, ramp up inventories. But going forward and structurally we are working on financing our suppliers on cables and wires, which should release working capital. So, excuse me for having a higher working capital for the next six months, after which we start stabilising and coming down to 30 days plus-minus of working capital. I don’t have a number readily, but that’s the intent.”
Daga said April-June 2027 should be the period when working capital begins to stabilise.
So the first phase is likely to be more about getting the business into the market than maximising margins.
UltraTech isn’t planning another big cable investment
Another important point from management is that the Rs 1,800 crore project isn’t currently being followed by another large cable capex programme.
The company had already spent or committed Rs 888 crore of the approved Rs 1,800 crore by the June quarter. During the July 20 earnings call, Daga said the project was on schedule and on budget, with the facility set up, trial runs started and channel-partner onboarding progressing.
When asked whether UltraTech planned to increase its cables and wires building-material capex, Daga said during the same call, “Amit, as of now, we are fully booked in terms of our cash flows. All the operating cash flows will get ploughed back into growth. And beyond that, also, there is dividends for shareholders. As of now, I don’t foresee any requirement for further investment in cables and wires. They will now first mature and milk the investment that they have done. So capital allocation to conclude, remains very committed to cement and shareholders.”
That is a clear indication that management wants the current cable investment to establish its economics before committing additional capital.
UltraTech: Cement remains the main earnings driver
While Ultravolt is the new business, UltraTech’s financial profile is still overwhelmingly linked to cement.
According to the company’s July 20 investor presentation and earnings call, domestic grey cement capacity stood at 200.1 MTPA and total capacity at 205.5 MTPA. The company plans to take grey cement capacity to 212.7 MTPA by the end of fiscal 2027 and consolidated capacity beyond 242 MTPA as its projects are completed.
Daga said during the July 20 earnings call, “Our growth to 240 million tonnes is funded and under construction. And this year, we launched a new growth business in terms of cables and wires.”
UltraTech’s Q1 FY27 performance also shows the scale of the existing business. The company reported 13.1% growth in domestic grey cement volumes, 81% capacity utilisation, EBITDA of Rs 5,146 crore and profit after tax of Rs 2,604 crore, which was 17.2% higher year-on-year.
Singh of Motilal Oswal said, “While UltraTech is venturing into a new business segment Cables and Wires (C&W), its core business remains grey cement. In the cement business, we believe UltraTech continues to extend its lead over peers across scale, market share, cost, and cash-flow generation. Its large and diversified manufacturing footprint enables the company to capture a disproportionate share of industry growth, while scale benefits should structurally lower opex/t.”
| UltraTech cement expansion | Company disclosure |
| Domestic grey cement capacity | 200.1 MTPA |
| Total cement capacity | 205.5 MTPA |
| FY27 grey capacity target | 212.7 MTPA |
| Planned capex | Rs 17,000 crore |
| Consolidated capacity target | 242+ MTPA |
Analysts see Ultravolt as an extension of the building-material business
Analysts aren’t treating the cable launch as a move into an unrelated industry. Their argument is that wires and cables sit close to cement, ready-mix concrete and other products used in residential construction.
Shetty of Mirae Asset Sharekhan said, it is a “vertical extension of building-materials ecosystem. UltraTech already has grey cement, RMC, white cement and building products, wires/cables is another residential construction product.”
He also said the cable entry wasn’t an aggressive diversification move because the investment is modest compared with UltraTech’s cement capex and operating cash generation.
The company made a similar case at the launch. According to its September 3 announcement, Ultravolt will offer home wires, flexible wires and cables for residential, commercial, industrial and infrastructure applications, with plans to add a broader range of electrical accessories over time.
Sriram Rangarajan, CEO, Ultravolt, said at the September 3 launch, “Wires are the lifeline of a house but often go unnoticed. We want to use our understanding of home consumers and to develop products for their growing needs. We want to bring a more consumer-first approach to the category, with safety, performance and future-readiness at the centre of product development.”
He added that the initial portfolio would cover home wires, flexible wires and cables for residential, commercial, industrial and infrastructure applications.
The bigger Ultravolt valuation story may come around FY29
The analysts’ longer-term view is more positive, but they want to see evidence that the new business can reach the return levels targeted by management.
Singh of Motilal Oswal expects Ultravolt to ramp capacity and utilisation through FY31-32 and said the company is targeting RoCE of around 25% by FY31-32. He also expects EBITDA margins to reach industry levels at full ramp-up by FY30-31.
Shetty said, “Limited value for wires/cables today, no operating track record/meaningful revenue. Management targeted ~25% IRR, 5–7x asset turnover and RoCE above 20%. If delivered, market may assign incremental value. More FY29 valuation conversation than FY27.”
He explained the timing further, saying, “I would view that as an FY29-type valuation conversation, rather than something that materially changes the stock’s FY27 valuation today.”
The current valuation references supplied by the two analysts also show why the cable business isn’t yet being treated as a major earnings contributor.
| Analyst | Valuation reference |
| Motilal Oswal | 15.0x one-year forward EV/EBITDA |
| Motilal Oswal long-term average | 17.0x |
| Mirae Asset Sharekhan FY27 | 17x EV/EBITDA |
| Mirae Asset Sharekhan FY28 | 14x EV/EBITDA |
What Ultravolt means for UltraTech Cement
The analyst view is clear. Ultravolt gives UltraTech access to another large construction-material category, particularly in residential markets, and the company’s existing brand and distribution network could help the new business build scale faster than a standalone entrant.
But the financial impact won’t come overnight. The cable business still needs to build inventory, onboard dealers, establish the brand and increase capacity utilisation. UltraTech has also said that it doesn’t currently see a need for additional cable investment.
Meanwhile, cement remains the main earnings engine, with more than 200 MTPA of domestic grey cement capacity and Rs 17,000 crore of expansion capex already in progress. The success of Ultravolt will therefore be judged less by its launch and more by whether it can eventually deliver the utilisation, margins and returns that analysts and management are looking for.
Conclusion
Ultravolt gives UltraTech Cement a new growth opportunity without changing the company’s core earnings profile in the near term. Analysts expect the cable business to take time to build scale, while cement remains the main driver of revenue and profits. The bigger test will be whether UltraTech can turn its existing distribution network and brand strength into a profitable wires and cables business over the next few years.
Disclaimer
This article is intended for informational and educational purposes only and should not be construed as investment advice, a recommendation to buy, sell or hold UltraTech Cement shares, or a prediction of the company’s future stock performance. The views and estimates cited in the article belong to the respective analysts and research firms and may change as business conditions, financial results, industry trends and company strategy develop. References to Ultravolt’s expected capacity utilisation, profitability, return on capital employed, asset turnover, valuation and potential contribution to UltraTech Cement are based on company disclosures and analyst views available at the time of writing and are not guaranteed outcomes. Past financial performance and historical valuation multiples do not assure future results. Investors should independently evaluate the company’s financial statements, regulatory filings, management commentary, valuation, business risks and broader market conditions, and consult a qualified financial adviser before making any investment decision.