



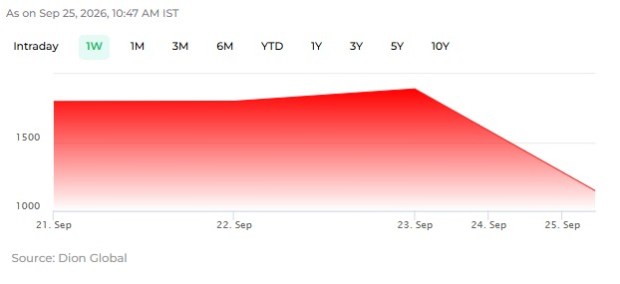
The PB Fintech shares continue to be in focus on Friday after the Insurance Regulatory and Development Authority of India’s proposed commission limits threaten the company’s future revenue stream. The shares of PB Fintech are trading in the red in early trading on Friday, after closing 36% lower on Thursday.
Brokerage House Motilal Oswal has maintained its “Neutral” rating on the stock but revised the target price to Rs 1,150, nearly 5% lower than the stock’s closing price on Thursday. The brokerage has based this at 50 times the average of the current and “worst-case” FY28 earnings per share.
Motilal Oswal on PB Fintech: To underperform till regulatory clarity
If the proposed changes to commission limits are implemented, PB Fintech, the parent of Policybazaar, could witness an around 30% hit to its FY28 core online insurance revenue.
“If we cut our FY28 core online insurance revenue estimates by 30%, without factoring in any adjustments to expenses or additional revenue streams highlighted by the company, our earnings estimates would decline by 46%,” Motilal Oswal said.
Assuming PB Fintech is able to lower its employee and advertisement costs by 20% from the current projections, the earnings cut would be around 30%. The brokerage believes the PB Fintech shares will continue to “underperform” until the final regulations are announced.
The insurance company’s core revenue may fall by 30%, Motilal said. PB Fintech’s core revenue is almost equally split between general insurance and life insurance. The net present value of its general insurance business could drop to 35%-40% of current levels, implying a 60-65% cut, the brokerage said, adding that life insurance net present value is expected to remain “in the same neighborhood.”
Motilal Oswal on PB Fintech: Key risk ahead
The biggest risk for the company is health renewal commissions, as it is not clear whether the cuts would apply to existing business or only to new business.
Motilal sees three factors offsetting these projections. These include the company working with its general insurance partners on a combined operating ratio model, so that lower commissions are passed through to customer prices. “Price elasticity has been ~1, and management expects to “get back” 15–20% through volume growth,” it said.
The other two factors include new revenue streams and cost reductions. The cost base is around Rs 30 billion and its management has indicated potential savings of around 10-15%, although concrete steps will be taken once the final regulations are out. Potential new revenue streams include charging for services, reinsurance broking, and possibly manufacturing.
“This is a draft for consultation. Management expects no impact in FY27, with implementation most likely from FY28. It described FY28 as a year of “challenges and discovery” and aims to return to a similar position by FY29,” Motilal said.
| Key concerns from Motilal Oswal |
| 30% hit to FY28 core online insurance revenue |
| 46% possible cut to FY28 earnings |
| Health renewal commission uncertainty |
| General insurance valuation pressure |
PB Fintech: FY28 earnings hit possible
The PB Fintech share is seen under pressure in the near-term and until there is more clarity on IRDAI’s proposed commission limits. If the changes are implemented as proposed, the insurance company’s earnings could take a major hit. Motilal Oswal underlines a few factors which could offset some of the impact. Most of the impact is likely to be seen from FY28.
Disclaimer: This article is based on research reports from one or more brokerage firms and is for informational purposes only. The views, target prices, and recommendations expressed are those of the respective brokerage firms and do not reflect the official policy or position of Financial Express. This should not be construed as an offer, solicitation, or recommendation to buy or sell securities. Investors must conduct their own independent due diligence and seek advice from a SEBI-registered financial advisor before making any investment decisions.