



Solar Industries is preparing for a major expansion of its global explosives business through the proposed acquisition of South Africa-based Omnia Holdings, while continuing to invest heavily in defence. The deal is expected to substantially increase the company’s revenue base and international reach, but the acquired business currently operates at a lower margin than Solar, with the transaction also requiring significant debt funding.
The combination will give Solar access to established mining explosives operations, manufacturing facilities and distribution networks across multiple markets. At the same time, management has said its defence capital allocation will continue to increase, making the Omnia transaction an addition to Solar’s existing growth plans rather than a replacement for them.
| Key development | Details |
| Omnia acquisition | 100% acquisition of South Africa-based Omnia Holdings |
| Deal value | About Rs 13,000 crore |
| Omnia FY28 revenue contribution | Rs 14,000-15,000 crore |
| Combined FY28 revenue estimates | Rs 31,000-32,000 crore |
| Combined FY28 EBITDA estimates | Rs 6,800-7,000 crore |
| Global distribution reach | More than 100 countries |
| Manufacturing footprint | 25+ countries |
| Solar defence allocation | Management expects capital allocation to continue increasing |
Elara on Solar Industries: ‘Accumulate’
Elara Securities has an ‘Accumulate’ rating on Solar Industries India Ltd. with a target price of Rs 19,970.
Harshit Kapadia, Senior President – Capital Goods, Defence, Railways, Consumer Durables, Consumer Electrical and EMS, Elara Securities, pointed out that the, “the acquisition would enable SOIL to double revenue by FY28E post consolidation. However, it will be margin- and ROE-dilutive, as Omnia EBITDA margin stood at 11% in FY26 with a ROE at 13%.”
The brokerage said the acquisition is expected to double Solar’s current sales from FY28, with the transaction expected to close by mid-2027. Omnia is expected to contribute Rs 14,000-15,000 crore of sales in FY28.
Elara also expects the acquisition to expand Solar’s position in the global explosives market. The brokerage said Omnia’s backward integration into nitric acid and ammonium nitrate manufacturing could provide operating synergies for the combined business.
Solar Industries: Elara on margin improvement and debt reduction
The difference in profitability between the two businesses is central to Elara’s assessment. Omnia reported an EBITDA margin of 11% in FY26, compared with about 27% for Solar, while Omnia’s ROE was around 13% against Solar’s 31%.
Kapadia stated that, “The pace of margin scale-up and reduction of debt would be the key monitorables for rerating.”
Elara expects the acquired business to gradually improve its margins over the longer term, helped by backward and forward integration. The brokerage also expects Omnia’s cash generation to support debt repayment after the acquisition.
Solar Industries share price performance
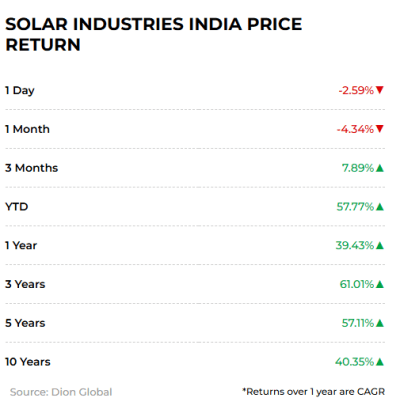
The acquisition will be funded through debt and internal accruals. Elara estimates additional debt of about Rs 11,000 crore by FY28, with annual interest costs of Rs 800-900 crore.
Solar Industries management on global aspirations
During Solar Industries’ business update call on September 15, 2026,, the company’s managing director and CEO Manish Nuwal explained the strategic rationale behind Omnia.
“The strategic rationale for this proposed acquisition of South Africa’s Omnia Holdings is to create a most integrated global platform for commercial explosives and blasting solutions,” Nuwal said.
Management expects the combined business to generate revenue of around Rs 31,000-32,000 crore in FY28, with EBITDA of Rs 6,800-7,000 crore. The company expects the combined EBITDA margin to be around 22-23%.
Solar has also said the transaction will be funded through internal accruals and debt, with no equity issuance planned. Management expects debt to remain below two times EBITDA.
Omnia deal to help expand Solar’s international footprint
The acquisition gives Solar access to an established network across international mining and explosives markets. Management expects distribution reach to increase from around 90 countries to more than 100, while the manufacturing footprint could expand from 11 countries to more than 25.
“If you try to enter into a new geography, it takes 4 to 5 years to really establish ourselves,” Nuwal said.
The transaction also gives Solar access to Omnia’s mining explosives operations and its integrated manufacturing facilities. Elara said the nitric acid and ammonium nitrate operations can provide backward-integration benefits for the combined explosives business.
Nuwal also pointed to the opportunity to use Omnia’s distribution network to sell Solar’s existing products.
“Solar is the largest producer of packaged explosives in the world, and having such kind of strong distribution presence of BME into the system, we would be able to leverage the strength of Solar also, Solar product into this vertical,” he said.
Defence investments will continue
The Omnia acquisition comes even as Solar continues to build its defence business. The management has said the transaction will not reduce capital allocation towards defence.
“Definitely, our focus and our capital allocation for defence will not go down. Rather, as we move forward, it is going to go up and up,” Nuwal said.
Solar has been expanding its defence portfolio across ammunition, rockets and other systems, while its order book provides visibility for the business.
The company’s Q1FY27 investor presentation dated August 13, 2026 showed defence revenue of Rs 933 crore, up 123% year-on-year from Rs 418 crore in Q1FY26. Defence accounted for 26% of Q1FY27 sales, compared with 19% a year earlier.
Omnia’s agriculture business in focus
Omnia also has a sizeable agriculture business alongside mining explosives and chemicals. Elara said agriculture accounted for 54% of Omnia’s FY26 revenue, while mining contributed 41% and chemicals 5%.
Solar management has described the agriculture business as technology-driven, with products spanning crop nutrition, biologicals, biostimulants and related areas.
Nuwal said Solar intends to use Omnia’s expertise and products across its international operations, but there is currently no plan to expand the agriculture business into India.
Q1FY27 shows the strength of Solar’s existing business
Solar entered the Omnia transaction after a strong first quarter. Its Q1FY27 sales rose 70% year-on-year to Rs 3,668 crore, while EBITDA increased 82% to Rs 1,024 crore. PBT rose 89% to Rs 911 crore and PAT increased 89% to Rs 666 crore.
The business had a balanced revenue mix in the quarter. Domestic explosives contributed Rs 1,361 crore, international explosives Rs 1,364 crore and defence Rs 933 crore. The company’s order book stood at Rs 21,350 crore.
This provides the base from which Solar is now adding Omnia’s international operations, rather than relying on the acquisition as its only source of growth.
Motilal Oswal on Solar Industries: Broader defence opportunity
Sneha Poddar, VP-Research, Wealth Management, Motilal Oswal Financial Services, said Solar is moving beyond its traditional industrial explosives business and building a broader defence platform.
“Solar Industries is executing a structural transition from a leader in industrial explosives to a high-technology, integrated defence platform. The strategic integration of global acquisitions like Omnia Holdings, alongside advanced high-margin defence innovations—from Pinaka rockets to autonomous counter-drone systems like Bhargavastra—positions the company for strong scale, deeper global expansion, and long-term earnings compounding,” Poddar said.
Poddar added that, “Solar Industries is moving up the defence value chain—transitioning from energetic materials to complete precision munitions, rockets, and counter-drone warfare ecosystems. Coupled with a expanding international footprint, the business is well-positioned for sustained global scale and revenue diversification.”
Two businesses, two growth drivers
Solar Industries is now building its next phase around two major businesses. Omnia expands the commercial explosives franchise into a much larger international network, while defence continues to receive capital and management attention.
Most analysts believes the key financial question is how quickly Omnia can improve its profitability after consolidation and how efficiently Solar can manage the additional debt. Elara expects the acquired business to benefit from integration and scale over time, while management is targeting a combined business with revenue above Rs 30,000 crore and EBITDA of nearly Rs 7,000 crore in FY28.
For Solar, the acquisition therefore changes not just the size of the business but also its geographic reach and the mix of businesses contributing to earnings.
Disclaimer: This article is based on Elara Securities’ analysis of Solar Industries, the company’s business update call hosted by ICICI Securities on September 15, 2026, Solar Industries’ Q1FY27 investor presentation dated August 13, 2026, and comments by Sneha Poddar of Motilal Oswal Financial Services. The views, estimates, financial projections and forward-looking statements attributed to company management and brokerage analysts are their own and have not been independently verified by the publication. Actual results may differ from estimates because of business, execution, financing, regulatory and market-related factors. This article is intended for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security.