



JPMorgan has drawn a sharp comparison between Syrma SGS Technology, Avalon Technologies and Cyient DLM, arguing that strong earnings growth alone may not justify the premium valuations of the three EMS companies. The brokerage’s comparison puts revenue growth, earnings growth, return on capital employed (ROCE) and working capital at the centre of the valuation debate.
All three stocks have gained sharply over the past one-and-a-half months, but their earnings and capital-efficiency profiles differ. JPMorgan estimates Avalon to have the highest FY26-28 earnings CAGR among the three, while Syrma has the highest revenue CAGR. Cyient DLM has the lowest FY28E ROCE and the highest working-capital requirement of the three.
| Metric | Syrma SGS | Avalon Technologies | Cyient DLM |
| Revenue CAGR, FY26-28e | 37% | 32% | 27% |
| EPS CAGR, FY26-28e | 34% | 47% | 39% |
| FY28e ROCE | 21% | 29% | 16% |
| FY28e P/E | 56.6x | 67.5x | 51.6x |
JPMorgan’s estimates show that Avalon combines the strongest projected EPS growth among the three with a higher FY28 ROCE than Syrma and Cyient DLM. Syrma has stronger projected revenue growth than Avalon, while Cyient DLM has a lower revenue CAGR and ROCE than both.
JPMorgan’s core argument: ROCE matters alongside growth
Bhavik Mehta, CFA, J.P. Morgan, and his team said EMS companies operate with significant capital expenditure and working-capital requirements, making ROCE an important part of how their earnings growth should be valued.
“EMS is a sector where strong revenue growth has driven a P/E multiple re-rating over the past few years; however, one cannot ignore the ROCE of the business, given its capex-intensive and high-NWC nature and, hence, it has to be baked into the multiples as well,” the brokerage said.
JPMorgan said that among companies with comparable earnings growth, businesses generating higher ROCE should command higher multiples. It added that the market can focus more closely on balance sheets, cash flows and ROCE when earnings miss expectations, growth slows and working capital remains elevated.
Syrma: highest revenue growth among the three
Syrma has the highest projected revenue CAGR among the three companies at 37% for FY26-28E, according to JPMorgan estimates. Its EPS CAGR is projected at 34%, while FY28E ROCE is estimated at 21%.
JPMorgan expects Syrma’s growth to come from its industrial and automotive businesses, with demand from energy meters, power electronics, electric vehicles and ICT.
The brokerage expects Syrma to deliver a 33% organic revenue CAGR over FY26-28. It also noted that the company has guided for 35% revenue growth over the next two years.
Syrma’s estimated EBITDA margin is expected to remain around 10.5-10.7% through FY27-29, while ROCE is projected to rise from 12.6% in FY26 to 19% by FY29.
JPMorgan, however, said its reverse DCF implies that the current stock price is pricing in a 34% revenue CAGR for the next 10 years, which it considers optimistic.
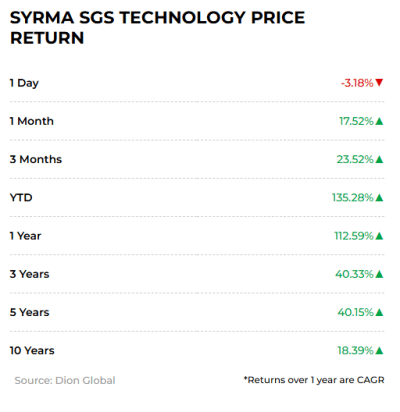
Syrma share price performance
Avalon: strongest EPS growth, but highest P/E
Avalon has the strongest projected EPS growth among the three stocks. JPMorgan estimates a 47% EPS CAGR for FY26-28, compared with 34% for Syrma and 39% for Cyient DLM.
Its projected revenue CAGR is 32%, below Syrma but above Cyient DLM. Avalon’s FY28E ROCE is estimated at 29.3%, also the highest among the three.
JPMorgan expects Avalon’s revenue growth to moderate from 35% in FY27 to 30% in FY28 and 25% in FY29. At the same time, EBITDA margin is projected to rise from 12.1% in FY27 to 13.2% by FY29.
The brokerage said Avalon has guided for 26% revenue growth over the next three years. Its reverse DCF, however, implies a 37% revenue CAGR over the next 10 years, which JPMorgan considers optimistic.
Avalon also has a higher working-capital requirement than Syrma. JPMorgan estimates FY26 NWC at 120 days for Avalon, compared with 63 days for Syrma.
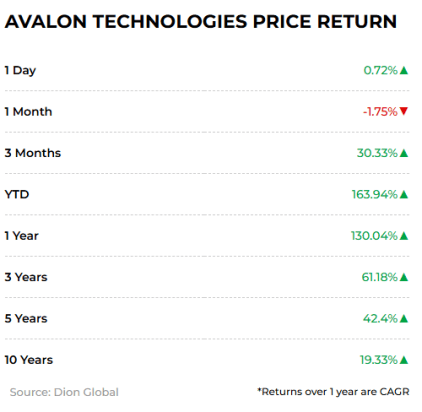
Avalon Technologies share price performance
Cyient DLM: Lower growth and ROCE, high working capital
Cyient DLM has the lowest projected revenue CAGR among the three at 27%, while its EPS CAGR is estimated at 39%. Its FY28E ROCE is 16.3%, below both Syrma and Avalon.
The biggest difference is working capital. JPMorgan estimates Cyient DLM’s FY26 NWC at 195 days, compared with 120 days for Avalon and 63 days for Syrma.
The brokerage said the elevated working-capital days followed delays in order execution, with customers adopting a wait-and-watch approach amid tariff-related uncertainty while inventory had already been procured.
“OCF is high in FY27E, because the company’s NWC days last year increased to 195 from the normal level of 115 days, and that is likely to normalize this year, mainly driven by lower inventory days,” JPMorgan said.
The brokerage expects Cyient DLM’s revenue to grow 30% in FY27, 25% in FY28 and 20% in FY29. Its EBITDA margin is estimated at around 11% during FY27-29.
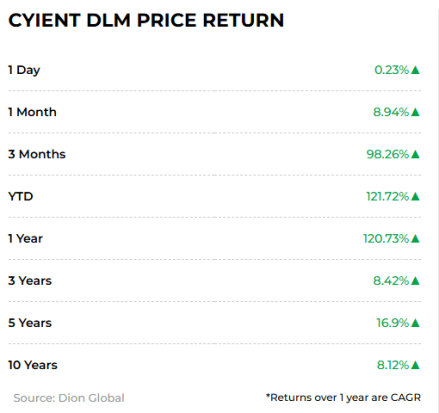
Cyient DLM share price performance
Valuation gap widens between three stocks
The comparison becomes more pronounced when the three stocks are measured against their FY28 earnings multiples.
JPMorgan estimates Syrma at 56.6x FY28 P/E, Avalon at 67.5x and Cyient DLM at 51.6x. At the same time, their projected EPS CAGRs are 34%, 47% and 39%, respectively.
This means Avalon has the highest valuation as well as the highest expected EPS growth among the three. Syrma has a lower EPS growth expectation than both Avalon and Cyient DLM, while trading at a higher P/E than Cyient DLM.
JPMorgan’s broader point is that the valuation comparison cannot be based on earnings growth alone. ROCE and working capital also have to be considered because EMS companies require capital expenditure and cash tied up in operations.
EMS stocks: Reverse DCF shows what market is pricing in
JPMorgan’s reverse DCF analysis provides another way of comparing the three companies.
It implies a 34% revenue CAGR over the next 10 years for Syrma, 37% for Avalon and 39% for Cyient DLM.
The brokerage considers these assumptions optimistic for all three. It noted that Syrma has guided for 35% revenue growth for the next two years, while Avalon has guided for 26% growth over the next three years.
For Cyient DLM, JPMorgan’s own FY26-28 revenue CAGR estimate is 27%, making the 39% long-term growth implied by its reverse DCF notably higher than its current forecasts.
How EMS stocks compare on cash generation
Working capital is an important dividing line in the comparison.
Syrma’s FY26 NWC is estimated at 63 days, while Avalon is at 120 days and Cyient DLM at 195 days.
JPMorgan’s forecasts show Syrma’s free cash flow to the firm turning negative in FY27 before improving to Rs 231 crore in FY28. Avalon’s FCFF is estimated at Rs 38 crore in FY27 and Rs 18 crore in FY28, while Cyient DLM is expected to generate Rs 257 crore of FCFF in FY27 but only Rs 16 crore in FY28.
The numbers show why JPMorgan is focusing on cash conversion and capital efficiency alongside revenue and EPS growth.
EMS stocks: Margin trajectory Avalon has the strongest projected margin expansion among the three. JPMorgan estimates its EBITDA margin rising from 10.8% in FY26 to 13.2% by FY29.
Syrma’s EBITDA margin is estimated at 10.5% in FY27, 10.6% in FY28 and 10.7% in FY29.
Cyient DLM’s EBITDA margin is expected to remain around 10.8-11% over FY27-29.
This gives Avalon both a higher projected EPS CAGR and stronger expected margin expansion, while Syrma leads on revenue growth.
JPMorgan downgrades 3 EMS stocks
JPMorgan downgraded all three stocks from ‘Neutral’ to ‘Underweight’, citing valuation and recent price performance. Syrma, Avalon and Cyient DLM share prices had risen 21%, 35% and 38%, respectively, over the last one-and-a-half month.
For Syrma, JPMorgan’s concern centres on the gap between its growth expectations and the revenue growth implied by the valuation. For Avalon, the brokerage acknowledges higher earnings growth but points to a still higher valuation. For Cyient DLM, lower revenue growth, lower ROCE and elevated working capital form the key parts of its valuation argument.
The broader EMS comparison therefore comes down to four numbers: revenue growth, EPS growth, ROCE and working-capital intensity. Syrma leads on projected revenue growth, Avalon on EPS growth and ROCE, while Cyient DLM has the highest NWC requirement and lowest projected ROCE among the three.
Disclaimer: This article is based solely on J.P. Morgan research and the company data and estimates cited in the report. The views, estimates, forecasts, valuation assessments and ratings attributed to J.P. Morgan and its analysts are their own and have not been independently verified by the publication. Forecasts are subject to changes in business conditions, demand, margins, capital expenditure, working capital, order execution and other factors. This article is intended for informational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security.