



When the SMILE Strategy Stops Smiling
Vijay Kedia describes his method with an acronym. SMILE, he calls it: small in size, medium in experience, large in aspiration, extra-large in market potential. Find that combination, he says, then hold it for long periods and you can almost never go wrong.
Most coverage of his portfolio picks up the winners, the names that turned into multibaggers while everyone else looked away. Far less is written about the other half of a long holding period, the part where you sit through the drop and keep sitting.
Two stocks in his book are doing exactly that right now. A book printer from Mumbai and the company behind Club Mahindra. He has held both for years, and the June 2026 exchange filings show he did not touch either one. Yet one trades about 68% below its record high and the other about 55% below its own. What is holding Kedia behind?
#1 Repro India: The Print-on-Demand Microcap Masking its Losses
Incorporated in 1993, Repro India prints books. It handles the whole chain for publishers, from design and pre-press through printing, binding and dispatch. Its growth story for the last decade has been print-on-demand, where a copy gets printed only after somebody orders it.
With a current market cap of Rs 452 cr, this microcap has been in Kedia’s books at least since the filings for the quarter ending December 2015. That’s how far back Trendlyne has data for, though Kedia could have held it for much longer.
He held 7.1% in March 2023 and has let it drift down since, sitting at roughly 6.3% now, or 906,491 shares. The current holding is worth Rs 29 cr and at the peak price it would have been worth close to Rs 89 cr.
Join now
Why a 29% Sales CAGR is an Illusion
Let us look at the five-year financials to see if we can find out what is it that is holding Kedia behind.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5-yr CAGR |
| Sales (Rs cr) | 138 | 287 | 422 | 479 | 466 | 494 | 29% |
| EBITDA (Rs cr) | -5 | 13 | 44 | 52 | 32 | 36 | Turnaround, Then Drop |
| Net Profit (Rs cr) | -43 | -23 | 9 | 12 | -2 | -33 | Turnaround, Then Drop |
Sales jumped from Rs 138 cr in FY21 to Rs 494 cr in FY26, about 29% a year on a compound basis. However, one must know that FY21 was the year the pandemic shut schools and printing presses, so the base is unusually low and the rate flatters what happened.
Both EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) and net profit were negative in FY21, and you cannot compound out of a loss. The year-by-year figures do the work instead. They show a company that has made a full year profit in only two of the last six years. FY26 closed with a net loss of Rs 33 cr.
Return on capital employed is 1.21%. For every Rs 100 of capital the company has tied up in the business, it earned a little over Rs 1 of operating profit last year. Return on equity is negative. Money has been getting tighter too. Borrowings climbed from Rs 49 cr in FY24 to Rs 186 cr in FY26, cash from operations fell to Rs 3 cr from Rs 50 cr, and free cash flow was negative Rs 67 cr.
The ₹167 Crore Lifeline: Dissecting the Q1 Profit Mirage
On 4th August 2026 the company reported its June quarter. Net profit came in at Rs 129 cr. For a company valued at Rs 452 cr, that looks extraordinary. But as a smart investor, one must learn to read between the lines.
Revenue for the quarter was Rs 140 cr, up nearly 21% from a year earlier and the best top line the company has managed. Operating profit on that revenue was Rs 4 cr, an operating margin of 2.9% and the thinnest in the period we examined. The Rs 129 cr came from other income of Rs 169 cr, and inside that sits an exceptional gain of about Rs 167 cr from the sale of land at Mahape.
Take the land sale out and profit before tax for the quarter was negative. The printing business, in the quarter it grew fastest, made almost nothing. That single gain equals about 37% of the company’s entire market value.
Institutional Flight and Strained Valuations: Is the Bottom In?
The share price of Repro was around Rs 450 in August 2021 and as on 13th August 2026 it was Rs 315, which is a considerable drop.
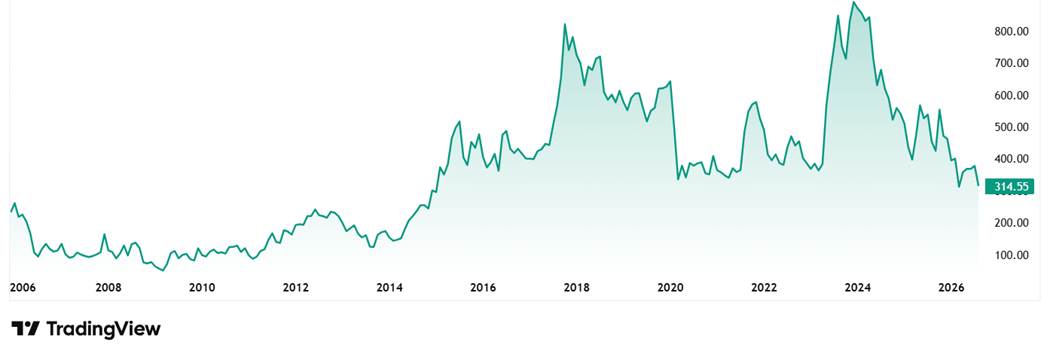
At the current price, the stock has taken a beating of about 68% from its all-time high of Rs 994 and 47% from its 52-week high of Rs 596.
Book value stands at Rs 244 a share against a price of Rs 315, so the stock changes hands at about 1.3 times what the accounts say it is worth. On that measure it is not expensive.
As for valuation, the company’s share is trading at a negative PE due to the string of losses it has logged in the last few years. The industry median is however close to 8x currently. The 10-year median PE of the company is 46x while the industry median for the same period is 15x.
Promoters held 61.7% in March 2017 and hold 46.7% now. Foreign investors, who owned 17.8% in March 2021, are down to 9.07%. Kedia’s own trimming belongs in the same picture. This is not a register where long term holders have been adding. But despite the battering, Kedia still sticks with this stock.
#2 Mahindra Holidays: The 97x PE Outlier Kedia Refuses to Sell
Mahindra Holidays and Resorts India runs Club Mahindra. Started in 1996 and majority owned by the Mahindra group, it sells vacation ownership memberships, which means a family pays a large sum upfront for the right to holiday at its resorts for 25 years. It is the largest business of its kind outside the United States.
With a current market cap of Rs 4,565 cr, the company has had Kedia on its share register since the filings for the quarter ending June 2021. Kedia has held a steady 1% stake in the company since then and currently that holding is worth Rs 46 cr. Unlike Repro, he has not trimmed a single share here.
Record Revenues vs. Crushing Debt: The Q1 Conundrum
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5-yr CAGR |
| Sales (Rs cr) | 1,730 | 2,013 | 2,517 | 2,705 | 2,781 | 2,992 | 12% |
| EBITDA (Rs cr) | 241 | 323 | 481 | 522 | 587 | 632 | 21% |
| Net Profit (Rs cr) | -14 | 68 | 114 | 116 | 126 | 67 | Turnaround, Then Drop |
Sales compounded at about 12% a year and operating profit at about 21%, both measured from a pandemic-hit FY21 base that flatters them. Net profit again carries no CAGR, because FY21 was a loss year, and the row itself is more useful than any single rate.
Profit climbed steadily to Rs 126 cr in FY25, then almost halved to Rs 67 cr in FY26. Interest rose from Rs 91 cr in FY21 to Rs 197 cr in FY26, depreciation from Rs 264 cr to Rs 409 cr.
The June 2026 quarter produced a net loss of Rs 8.55 cr. That headline is misleading in the opposite direction to Repro’s.
Revenue for the quarter was Rs 733 cr, the highest the company has ever recorded for a June quarter. Operating profit was Rs 113 cr. The business was working. What killed the quarter sits underneath it. Depreciation came to Rs 109.40 cr and interest to Rs 47.07 cr, together Rs 156 cr against operating profit of Rs 113 cr.
This is what happens when a company builds resorts quickly. Every new room starts charging the accounts for depreciation and borrowing costs long before it fills up with paying members. Operating margin for the quarter was 15%, down from 17% a year earlier.
Retail Buys the Dip While Foreign Institutions Flee
The share price of Mahindra Resorts was around Rs 200 in August 2021 and as on 13th August 2026 it was Rs 226.
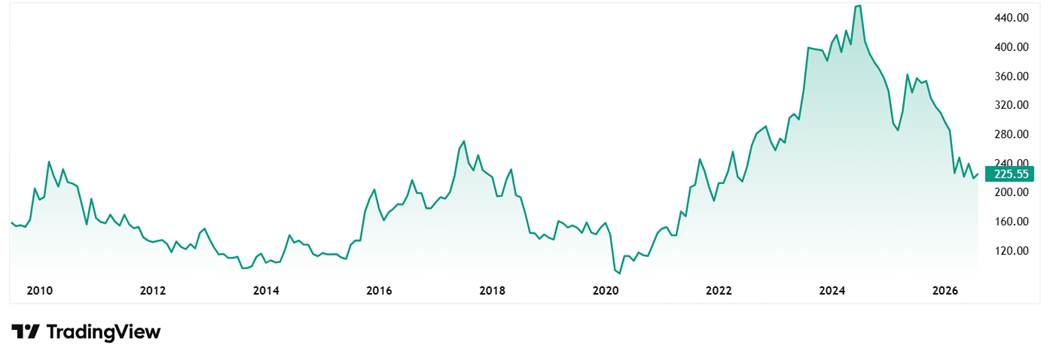
At the current price, the stock is trading at a discount of 55% from its all-time high of Rs 505 and 40% from its 52-week high of Rs 380.
Regarding valuations, the company’s stock is trading at a PE of 97x which is more than 3 times the current industry median of 30x. The 10-year median PE for the company is 50 while the industry median is 36x.
So, even after the fall, the stock carries close to three times the multiple of its own sector. It also trades at about 6 times book value.
One more number is worth watching. Foreign investors held 5.3% in March 2026 and 4.01% by June 2026, a visible cut in one quarter. Meanwhile the number of individual shareholders climbed from about 70,600 in September 2023 to 96,220. Retail has been buying this fall. Foreign institutions have been selling into it.
The 25-Year Cycle: How Upfront Cash Funds Aggressive Expansion
There is a genuine argument on the other side, and it rests on how this business collects money. A member pays a large sum upfront, but the company can only record it as revenue slowly, across the 25-year life of the membership. Cash arrives now, but profit arrives over decades.
The cash flow statement bears this out. In FY26 the company generated Rs 531 cr from operations against an operating profit of Rs 632 cr, and free cash flow after all its resort building was still positive at Rs 139 cr. That is a company funding heavy expansion largely out of what it collects at the door.
The counterweights are real too. Borrowings have grown from Rs 3,131 cr in FY25 to Rs 3,829 cr in FY26. Contingent liabilities stand at Rs 1,510 cr, which is about a third of the company’s entire market value. There has been no dividend since FY18. Return on capital employed is 8.12%.
The SMILE Strategy Stress Test – Patience vs. Value Traps
There is something that becomes clear when you look at both the stocks side by side. Both headline numbers are wrong, and they are wrong in opposite directions.
Repro reported the largest profit in its history while its printing business earned an operating margin of 2.9%. That profit came from land, not from books. Mahindra Holidays reported a loss in a quarter when its resorts delivered record revenue and Rs 113 cr of operating profit. That loss came from buildings which have not started paying for themselves yet.
One is a cheap stock with almost no returns on the capital inside it. The other earns respectable returns and is priced as though it earns spectacular ones. Neither is what the top line of the results suggests, and in both cases the truth lives below the operating line.
The SMILE approach was always built on the idea that patience gets paid eventually, and it has worked often enough in his career to have earned the benefit of the doubt. Whether these two names reward that patience, or quietly test the limits of holding for ten to fifteen years, the next few quarters will start to answer.
A sensible way to follow the story is to add these stocks to a watchlist and read the next two quarterly filings closely.
Disclaimer
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.