



The Pre-Listing Reality Check
Poojaa Precision Engg. listed on the BSE SME platform on 4th August 2026. Two days later, on 6th August, MV Electrosystems debuted on both the BSE and the NSE. When the shareholding tabs went live, two familiar names were already sitting there. Mukul Agrawal held 5.12% of Poojaa. Madhuri Madhusudan Kela, wife of Madhusudan Kela, held 4.22% of MV Electrosystems.
The easy reading is that super investors just added two new stocks. But a closer look at the filings narrate a different story. Neither bought anything last week. Both were on the register well before listing day, at prices no public investor could reach. In Kela’s case the stake shrank rather than grew, diluted by the fresh issue.
That distinction decides who is carrying the risk, and at what price. One of these companies is profitable and looks cheap on the screen. The other lost money last year and trades at 34 times sales. Let’s dive into both.
Join now
#1 Poojaa Precision Engg: The 600-Part SME Powerhouse
Incorporated in August 1992 as Pooja Castings, Poojaa Precision Engg runs out of Chakan near Pune and makes aluminium die castings and machined parts: engine housings, drivetrain pieces, EV powertrain components, electrical assemblies.
With a current market cap of Rs 904 cr, the company has more than 600-part numbers, 216 people on the payroll as on 31st March 2026, and customers from Indian vehicle makers and Tier-1 suppliers through to Germany, the United States, Italy and Switzerland. It has also won vendor approval in aerospace, a slow door to get through and a hard one to be pushed back out of.
Mukul Agarwal’s Pre-IPO Promoter Deal
Here is the part most coverage has skipped. Agrawal did not buy this in the IPO, and he did not buy it on the open market. He bought from the promoters, before the offer opened.
The promoter group held 99.16% of the company at the draft prospectus stage. By the time the issue opened, that was down to 82.63%, with the difference sold into private hands. Agrawal’s 5.12% works out to roughly 10.22 lakh shares, close to 7% of the pre-issue capital. A large slice of what the promoters let go went to him.
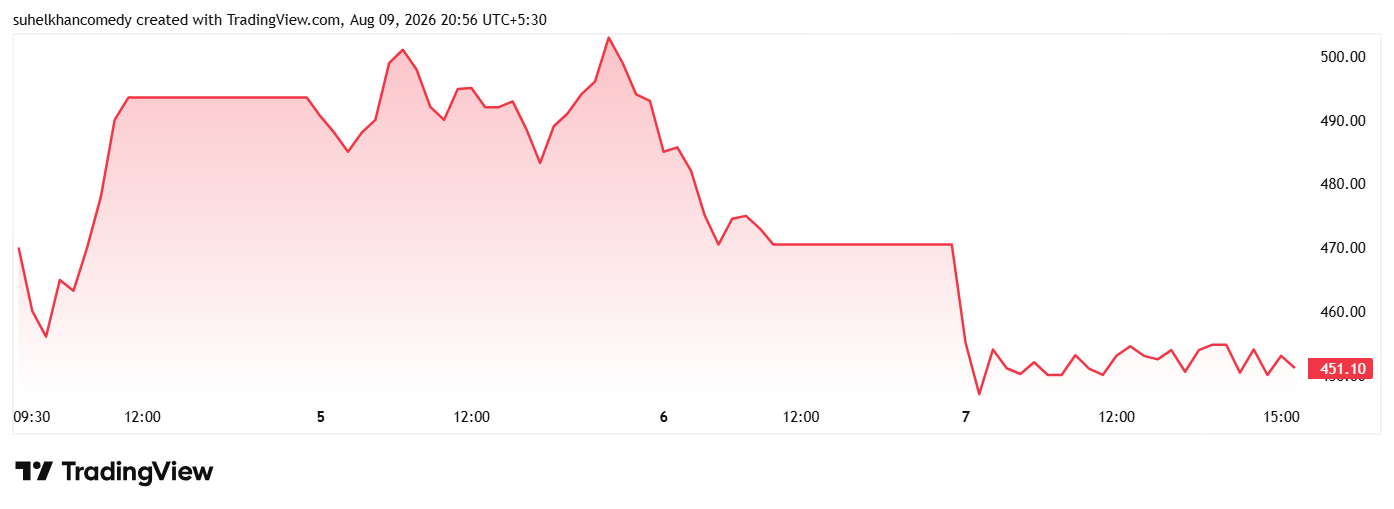
At the closing price of Rs 453 on 7th August 2026, that holding is worth about Rs 46 cr, making him the largest named public shareholder, ahead of every institution.
He was not the only recognisable name in the queue. The company raised Rs 45.14 cr from 14 anchors at Rs 301 a share, and Abakkus Venture Opportunities Fund, from Sunil Singhania’s shop, also found a place in the register.
Profit Margins Under the Microscope
Let us look at the financials of the company.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5-Yr CAGR |
| Sales (Rs cr) | 87 | 130 | 163 | 173 | 222 | 293 | 27% |
| EBITDA (Rs cr) | 9 | 16 | 24 | 28 | 40 | 52 | 42% |
| Net Profit (Rs cr) | 3 | 9 | 14 | 16 | 24 | 31 | 60% |
EBITDA here means operating profit before other income. Sales more than tripled in five years and profit rose roughly tenfold. Return on capital employed (ROCE) sits at 33.4% and return on equity (ROE) at 28.1%, both strong for a foundry.
Now the line that needs watching. Operating margin climbed from 10% in FY21 to 18% in FY26, and most of that move landed in the two years running up to the listing. Margin expansion of that shape, arriving just before a company sells shares to the public, deserves a second look rather than applause.
Valuation Reality: Analyzing the 50% Listing Premium
The IPO of Poojaa Precision Engg was priced at Rs 301. The stock opened at Rs 470 and closed at Rs 453 on 7th August, about 50% above issue price. The stock trades at roughly 29x PE earnings against the current industry median of 30x.
A word of caution is due here. Poojaa is a BSE SME stock, and that platform is a different ball game: you buy shares in lots, into a counter thin enough that a modest order moves the price and a hurried exit gets punished.
You will also see far less. SME issuers report results and shareholding twice a year rather than four times, and they sit outside the corporate governance rules that bind mainboard companies, so Agrawal’s stake and the numbers behind it go dark for six months at a stretch.
The Hidden Warning Signs: Working Capital and Negative Cash Flow
The balance sheet shows the strain fast growth puts on a small manufacturer. The cash conversion cycle, roughly how long money stays stuck between supplier and customer, stretched from 56 days in FY23 to 134 in FY26. Debtor days doubled to 65 and inventory days went from 76 in FY24 to 148 in FY26.
Borrowings doubled to Rs 41 cr and free cash flow was negative Rs 30 cr in FY26, as capital work in progress jumped to Rs 28 cr for the new Pune plant. The profits are real. They are just not turning into spare cash yet, which is what the IPO money is meant to fix.
#2 MV Electrosystems: The High-Stakes Railway Tech Play
Incorporated in 2009 and based in Haryana, MV Electrosystems builds electrical and power electronics kit for railway rolling stock. Its flagship product is IGBT based three-phase propulsion equipment for electric locomotives, the package of traction converters, inverters, vehicle control units and driver displays that moves a train. It also makes switchgear panels for coaches and EMUs.
With a current market cap of Rs 1,669 cr, the company in September 2025 received its prototype clearance from Chittaranjan Locomotive Works for that propulsion system, designed entirely in house, and commercial supplies began in March 2026. Very few Indian companies own this technology outright, and the approval process keeps newcomers out for years.
Madhusudan Kela’s Secret 2025 Investment Stake
Madhuri Kela has held 11.5 lakh shares here since at least the draft prospectus in December 2025, when that was 5.6% of the company. She holds the same 11.5 lakh shares today. The fresh issue of 68.24 lakh shares widened the capital base, so her percentage fell to 4.22%, worth about Rs 70 cr at Rs 612 on 7th August.
So, this is not a new position. It is an old private bet that has only just become visible. The issue was priced at Rs 425, drew bids worth roughly 189 times the shares on offer and raised Rs 130.5 cr from anchor investors. The stock has since traded between Rs 519 and Rs 687.
The FY26 Revenue Decline and Rs 13 Cr Loss
The public accounts run back only four years, so a five-year compounded growth rate cannot be calculated, and with FY26 a loss year a profit CAGR would be meaningless anyway. The year-by-year picture does the work instead.
| Financial Year | FY23 | FY24 | FY25 | FY26 |
| Sales (Rs cr) | 68 | 50 | 63 | 49 |
| EBITDA (Rs cr) | 6 | 6 | 7 | -10 |
| Net Profit (Rs cr) | 1 | 1 | 1 | -13 |
| Operating Margin | 9% | 12% | 12% | -20% |
EBITDA here means operating profit before other income. Five-year CAGR is not shown as only four years of data are available and FY26 was a loss year.
Sales fell 23% in FY26 and the company swung from a small profit to a loss of about Rs 13 cr, with return on equity at minus 31%.
The half-reassuring explanation sits in the working capital lines. Inventory days ballooned to 731, the cash conversion cycle went from 85 days in FY23 to 571 in FY26, and cash from operations was minus Rs 58 cr. That is the signature of a company building expensive kit it has not yet delivered or billed.
And there is something to deliver against. As on 30th June 2026 the executable order book for propulsion equipment stood near Rs 989 cr across 564 units, with MEMU development orders on top. Rs 180 cr of the IPO money is earmarked for this exact gap.
Analyzing 44% Listing Premium and 189x Subscription
The IPO of MV Electrosystems Ltd was priced at Rs 425, the top of a Rs 400 to Rs 425 band, and raised Rs 290 cr entirely through fresh shares. It drew bids for roughly 189 times the stock on offer. Ahead of that, Rs 130.5 cr came in from anchor investors on 29th July, with 30,70,588 shares allotted to a book that included Kotak Mutual Fund, 360 ONE Prime etc.
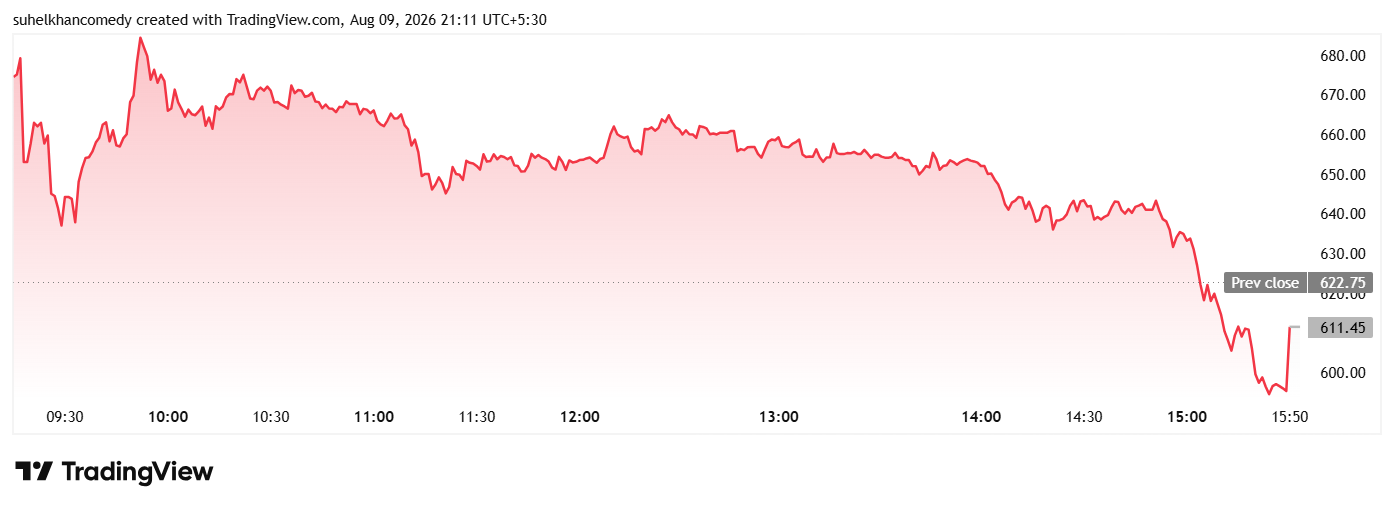
The stock opened at Rs 520 on the NSE on 6th August and Rs 519 on the BSE, a premium of about 22% over the issue price. That put the company near Rs 1,514 cr on day one. It has traded between Rs 519 and Rs 687 since, and closed at Rs 612 on 7th August, roughly 44% above where the IPO priced it.
As for the valuation, the stock is trading at a negative PE due to the logged losses, but the industry median currently is 31x. Buyers are paying for the order book and the CLW approval, not anything in the accounts. Borrowings have risen to Rs 55 cr and interest cover is thin, so delivery has to arrive on schedule.
Weighing the Risks Behind the Institutional Buzz
Put the two side by side and the split is clear. Poojaa is the profitable one, growing fast, priced below its sector, with a working capital squeeze the IPO money should ease. But it comes with a fair warning as it is listed on the SME exchange. MV Electrosystems is the technology one, holding a rare approval and a fat order book, but priced at 34 times sales while still losing money.
The uncomfortable fact they share is entry price. Agrawal bought from promoters before the prospectus was final. Kela has been in since 2025 at the latest. Anchors paid Rs 301 and Rs 425. Anyone buying today pays roughly 50% and 44% above those prices, and a good deal more than the pre-issue investors did.
That gap is not a scandal; it is how public offerings work. But the cushion these two sit on is not one a buyer today inherits. When a famous name shows up in a shareholding tab, the useful question is not what they own. It is what they paid, and when they can sell.
The next few quarters settle much of this. Poojaa has to show margins hold once the listing glow fades and the new plant starts absorbing cash. MV Electrosystems has to turn that order book into revenue and prove the FY26 loss was timing, not trend. Until then, adding both to a watchlist and waiting for the numbers is a good deal cheaper than guessing.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.