



Decoding Mukul Agarwal’s Strategy: Why These 2 Smallcaps?
I was scanning through the portfolios of the super investors like I usually do when 2 stocks in the portfolio of ace investor Mukul Agarwal caught my attention. Both of these stocks have been a part of Agarwal’s portfolio for quite some time now and have a few things in common apart from Agarwal being on the register.
A compounded net profit growth above 100% or in triple digits over five years, a share price near or below book value and still trading below its all-time high. A combined holding of around Rs 176 cr, in Agarwal’s current Rs 7,720 cr portfolio.
Both the stocks are small caps and with the above being said, the question is if there is a hidden uptick waiting to happen or are these mistakes in Agarwal’s books. Let us dive in to find out.
#1 Capacite Infraprojects: A ₹13,535 Cr Backlog Trading Below Book Value
Capacit’e Infraprojects is primarily engaged in the EPC business and provides turnkey solutions for housing, high rises, super high rises, speciality buildings and urban infrastructure. The company offers these services to leading real-estate and government bodies in India. It does not own the land and it does not carry the sales risk. It gets paid to execute.
The company reported its June quarter on 7th August 2026. Consolidated revenue came in at Rs 629 cr against Rs 589 cr a year earlier, a rise of about 7%. Profit after tax was Rs 40 cr, down from Rs 47 cr. The market did not like it. The stock fell over 5% on the day.
Agarwal currently holds 6.6% stake in the company worth Rs 119cr.
Join now
But the same filing carried a far larger number. The order book stood at Rs 13,535 cr. Set that against FY26 sales of Rs 2,623 cr and you get a book to bill ratio of about 5.2 times. In plain terms, the company has already signed up more than five years of work at its current pace of execution. Very few smallcap contractors carry that kind of visibility.
Beyond the Headlines: The Reality of Capacite’s Profit Margins
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5-yr CAGR |
| Sales (Rs Cr) | 880 | 1,340 | 1,799 | 1,932 | 2,350 | 2,623 | 24% |
| EBITDA (Rs Cr) | 136 | 218 | 357 | 334 | 379 | 427 | 26% |
| Net Profit (Rs Cr) | 2 | 48 | 95 | 120 | 204 | 193 | 150% |
EBITDA here refers to operating profit before other income. That 150% figure is real, but it is also misleading. FY21 net profit was Rs 2 cr. When you start from almost nothing, any recovery produces a spectacular percentage. The honest way to read this table is to ignore the last column on the profit row and look at the shape instead.
The shape is good. Sales have almost tripled since FY21 and have risen every single year. Operating profit has grown at a similar clip, which means margins have held rather than been bought with discounts. Net profit went from Rs 2 cr to Rs 193 cr. Even measured against the pre pandemic FY19 figure of Rs 97 cr, profit has roughly doubled in seven years. That is a genuine improvement, just not 150% annually.
FY26 did see profit dip from Rs 204 cr to Rs 193 cr. Some of that is a fair comparison problem. FY25 carried Rs 74 cr of other income against Rs 27 cr in FY26. Strip that out and the operating story actually improved.
A Chart in the Red
The share price of Capacite Infraprojects was around Rs 217 in August 2021 and as of closing on 7th August 2026 it was Rs 213, which is a flat scale for the last 5 years. However, at the current price, the stock is about 36% below its 52-week high of Rs 334, and roughly 54% below its all-time high of Rs 465 hit in December 2024.
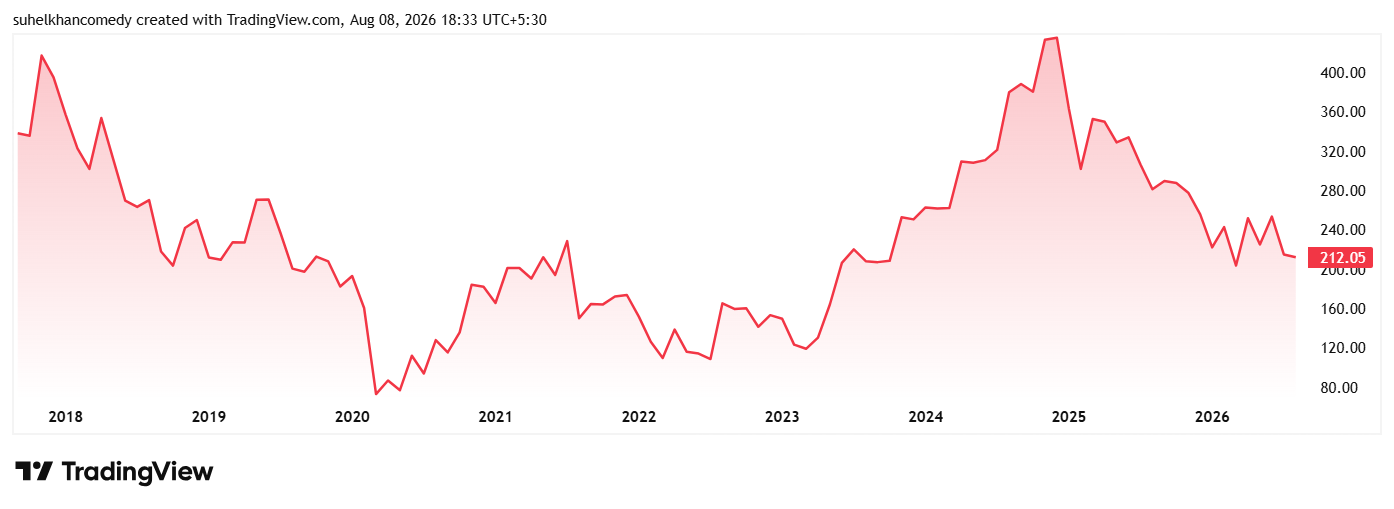
Book value is Rs 226 per share. So, the stock changes hands at about 0.95 times book, which means the market values the whole business at slightly less than the accounting worth of what it owns.
Regarding the valuations, the company’s shares currently trade at a PE of about 10x and the industry median currently is about 17x. The 10-Year median PE for the company is 16x while the industry median for the same period is 17x.
Pledged Shares and Debtor Days
Promoter holding is 31.7%. It was 43.8% until FY22. Promoters have sold down substantially, and while the stake has been stable for two years now, a founding group owning less than a third of a contracting business is worth noting.
Roughly 31.9% of the promoter holding sits pledged with lenders. That is down sharply from about 46% in mid-2024, so the direction is right, but pledged shares are still pledged shares.
Then there is the money. Debtor days run at 151. Customers take about five months to pay. In a business where Capacite pays for steel and wages long before it invoices, that is a permanent drag on cash. Return on equity is 10.4% and return on capital employed is 15.5%. Respectable for a contractor, unexciting in absolute terms.
#2 West Coast Paper Mills: A Commodity Play at a 52-Week High
Founded in 1955 and run by the SK Bangur group, West Coast Paper makes printing, writing and packaging paper from a large mill at Dandeli in Karnataka, and consolidates the Andhra Paper business alongside it. It is one of the oldest and biggest paper makers in the country.
The recent filings show compounded profit growth of 115% over five years. The stock trades at 1.10 times book. Agarwal currently holds a 1.4% stake in the company worth Rs 57 cr.
Let us look at the 5-year financials to get a better sense of what is going on in the books.
Stripping the Anomaly: West Coast Paper’s True Core Earnings
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5-yr CAGR |
| Sales (Rs Cr) | 2,245 | 3,378 | 4,921 | 4,448 | 4,062 | 4,279 | 14% |
| EBITDA (Rs Cr) | 261 | 638 | 1,647 | 1,095 | 494 | 414 | 10% |
| Net Profit (Rs Cr) | -4 | 346 | 1,087 | 786 | 336 | 156 | NM |
EBITDA here refers to operating profit before other income. The five-year profit CAGR is marked NM, or not meaningful, because FY21 was a loss year and a growth rate cannot be calculated from a negative base.
FY21 was a loss of Rs 4 cr. You cannot compound out of a loss, which is why we have marked that cell NM rather than repeat the 115%.
Now look at what the table actually shows. Profit peaked at Rs 1,087 cr in FY23 and has fallen every year since, to Rs 156 cr in FY26. That is an 86% decline in three years. Operating margin went from 33% to 10%. Return on capital employed fell from 53% to 6.17%. Return on equity is 4.25%.
This is not a growth stock caught in a dip. It is a commodity business coming down hard from an exceptional cycle. Also, in FY26 other income of Rs 114 cr made up nearly half of the Rs 237 cr pre-tax profit. The core paper operation is earning considerably less than the headline profit suggests.
Why the Stock Is Rising While Earnings Fall
The share price of West Coast Paper Mills was around Rs 255 in August 2021 and as of closing on 7th August 2026 it was Rs 599 which is a jump of 135% in 5 years.
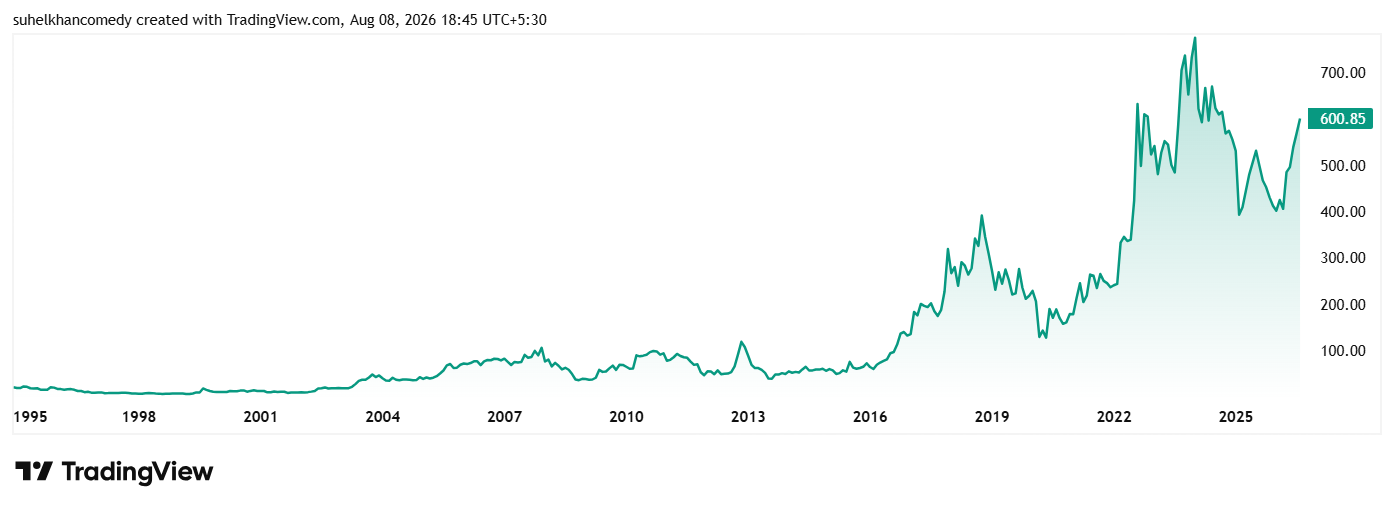
Against a 52-week high of Rs 602, the stock is essentially at a one-year peak. It has climbed roughly 42% just in the last 6 months, while profits were collapsing. But if you look at the all-time high of Rs 815, the stock is 26% below the same.
As for the valuations, the company’s share is trading at a PE of 26x against the industry median of 17x. The 10-Year median PE for the company is 8x while the industry median for the same company is 10x.
The Real Catalyst: How Anti-Dumping Duties Are Driving Up the Stock
What is driving it is policy, not profit. Indian paper mills have spent three years being undercut by cheap imports, much of it arriving duty free from ASEAN countries. In June 2026 the Directorate General of Trade Remedies recommended anti-dumping duties of up to US$376 per tonne on virgin multi-layer paperboard from Indonesia, for five years. The finance ministry still has to notify it.
That is what the market is buying. Not the last four quarters, but the possibility that the import flood is finally dammed. It is a reasonable bet. It is also a bet on a government notification, which is a different kind of risk from betting on an order book.
The balance sheet gives the company room to wait. Borrowings fell from Rs 456 cr to Rs 345 cr in FY26, investments stand at Rs 1,492 cr, and promoters hold a steady 56.6%. Domestic institutions have been buying, lifting their stake from 9.82% to 13.62% over five quarters, while foreign investors halved theirs. West Coast Paper reports its June quarter on 12th August 2026, and the board has recommended a final dividend of Rs 3 per share.
Execution Risk vs. Policy Hope
With all the numbers in sight now, the big question is what is it that Agarwal sees in these two stocks, with opposite trajectories.
Capacite is cheap on earnings that exist, holds five years of contracted work, and is priced below the book value of its own assets. Its problems are the ordinary problems of a contractor. Slow paying customers, pledged promoter shares, thin returns on capital, and a June quarter that missed. Those are execution risks, and they are visible.
West Coast Paper is cheap on assets but not on earnings, is at a 52-week high rather than a discount, and shows a triple digit growth rate that exists only because the starting point was a loss. Its case rests on a policy decision by the government that has been recommended but not yet notified.
The wider lesson here is that compounded growth rates calculated off a pandemic year, a loss, or a near zero base will keep throwing up spectacular numbers for the next few years. FY21 sits inside every five-year window until 2027. The fix takes thirty seconds. Look at the first column of the table before you look at the last one.
A sensible way to follow this would be to add these stocks to a watchlist and watch what the next few quarters do to both stories.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.