



The EV car industry is changing at a rapid pace, and the old winners are being left behind by more dynamic players. A key example is the rise of China’s BYD Auto, which produced 44.5 lakh EV cars in 2025. This is 2.8 times that of Tesla, which delivered 16 lakh cars in 2025. According to Bloomberg, Elon Musk had mocked and laughed at BYD’s products. However, we have seen how quickly the EV industry has changed, and BYD is now the market leader.
Both Tata Motors PV and Mahindra & Mahindra (M&M) are also showing key strengths which can allow them to expand EV adoption in the Indian automotive industry. They could also be among the top players in the international EV car export market. In FY2026, the Indian EV car sales were 1.99 lakh, out of which Tata Motors cornered a market share of 39.6%, and Mahindra had a market share of 23.9%.
Vahan data for the EV car market showed 81.6% YoY growth in July 2026 in terms of vehicle registrations. The EV vehicle registrations were 31,788 compared to 17,509 in the year-ago period. Tata Motors showed 101.8% YoY growth, reaching 13,579 registrations. Mahindra & Mahindra reached 7,677 registrations in July with 124.7% YoY growth.
Besides growing the domestic market share of EV cars, both Tata Motors and Mahindra could also see a strong tailwind due to potential growth in international markets.
Join now
Top EV energy-efficiency by Tata Motors and Mahindra
There are three main reasons why Tata Motors and Mahindra could deliver strong revenue and earnings growth in the next few quarters. The first reason is the improvement in product quality at an affordable entry price. For instance, the entry level Tata Tiago EV showed sales of 2,292 in June 2026 alone, making it one of the top-selling EV models for Tata Motors.
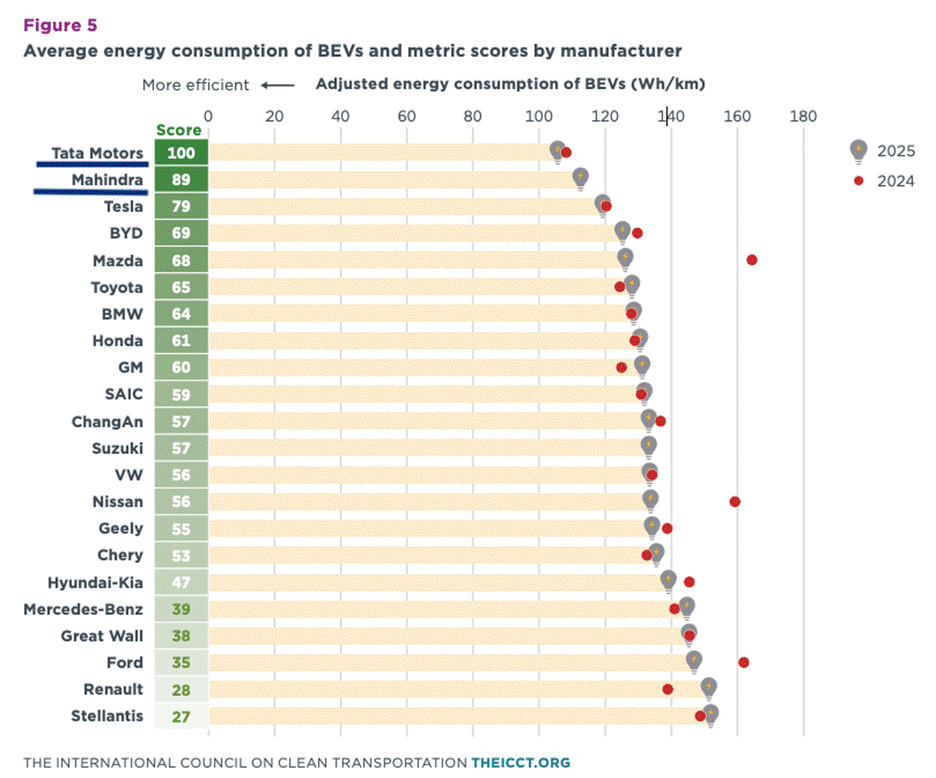
In a recent report by International Council on Clean Transportation, Tata Motors and Mahindra took the top 2 spots in terms of energy-efficient battery-electric vehicles. They were able to beat Tesla, BYD, Toyota, Honda, and other leading EV car manufacturers. Tata’s EV portfolio had an average energy consumption of 106Wh/km, while Mahindra had 113Wh/km. More energy-efficient cars help to increase range and lower the battery cost for EVs.
The ‘China Plus One’ Advantage
The second factor working in favor of Tata Motors and Mahindra is that all the major car markets in the world are looking to diversify their supply chain rather than remaining heavily dependent on China. This China Plus One strategy is being used by other countries to protect themselves against any future geopolitical issues. The European Union has increased tariffs on Chinese EVs to as high as 35.3%.
On the other hand, the recent trade deal between India and the European Union envisages a gradual reduction of tariffs. China’s GDP per capita is also 5X that of India, which increases the labour cost significantly. In export markets, Indian EV manufacturers get a labour cost advantage when competing with Chinese and other key EV brands that are manufactured in higher labour cost regions.
The third factor that should help in the rapid growth of EVs from Tata Motors and Mahindra is potential future expansion of subsidies from the Central and State governments.
China and all other major economies have used subsidies to increase the growth trajectory of their EV industry. We could see bigger subsidies in India as a greater push is given to increase the market share of EVs. This could also help in building a stronger charging infrastructure and increasing attractiveness for EVs.
Now, let’s dig into the performance of these two Indian companies that are leading the EV wave.
#1 Tata Motors PV
Tata Motors PV reported consolidated revenue of Rs 3.36 lakh crore in FY26, which it hopes to increase to Rs 6 lakh crore by FY31. This would be equal to a compound annual growth rate (CAGR) of 12.3%. It also wants to increase the production volume from 6.4 lakh units in the recent fiscal year to 12 lakh units by FY31.
The FY26 revenue saw an 8.3% YoY decline due to a 20.9% YoY decline in Jaguar Land Rover segment. On the other hand, the Tata PV segment reported 20.7% YoY growth. The FY26 EBITDA margin came in at 6.8%, which was a dip of 660 bps, largely due to a 760 bps decline in the JLR segment. The EBIT margin was 1.1%, declining by 660bps YoY due to a 780 bps decline in the JLR segment. The PBT was Rs 2,519 Cr, which was a YoY decline of Rs 26,131 Cr.
Bridging the Margin Gap
Q4 FY26 has started to show some positive trends in terms of stopping the margin decline. In Q4 FY26, the EBITDA margin of JLR was 14%, a 130 bps YoY decline. This is much better than previous quarters, and we could see continuous improvement in this metric as more cost-cutting is delivered at JLR.
The Q4 FY26 also reported 18,742 cr of revenue in Tata PV segment, which was a massive 49.4% YoY growth, largely with the help of the EV cars. The EBITDA margin also increased to 9.4%, a 150 bps YoY growth. The EBIT margin was 4.7%, a 310 bps YoY growth. The PBT of Tata PV was 1,102 Cr, a 710 Cr YoY jump.
The company has yet to report its 1QFY27 results.
Electric models now make up 14% of the total unit sales of Tata Motors. This segment reported 92,000 sales in FY26, which made up 40.2% market share in EV Vahan.
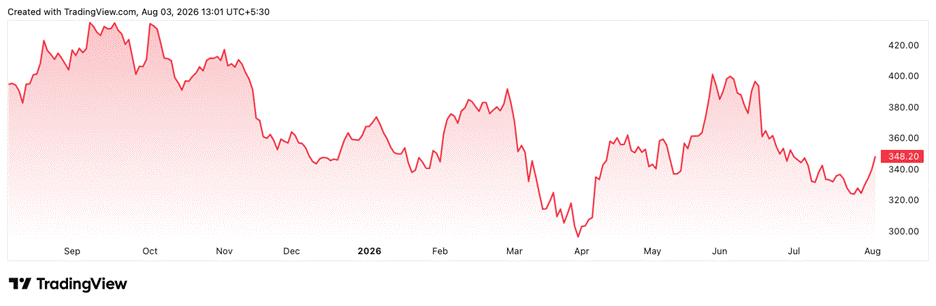
Tata Motors 1-Year Price Chart
Why Affordability is Driving Tata’s Growth Trajectory
As mentioned above, Tata Motors has been ranked #1 in terms of energy efficiency. This is largely due to more compact models in the portfolio and a greater focus on affordability by the management. We could see more affordable models from Tata Motors.
As the revenue share of electric vehicles increases, we could see an inflection point in Tata Motors’ growth rate. The growth runway for EV cars in India is potentially massive. Tata Motors could capture a major chunk of the market share, improving its revenue growth trajectory. This should drive future revenue and margin growth for the company.
#2 Mahindra & Mahindra
Mahindra & Mahindra reported consolidated revenue in Q1 FY27 of Rs 58,188 cr, which was a 28% YoY growth. The PAT was Rs 5,455 Cr, a 34% YoY growth. The quarterly volume for the Auto segment was 3.04 lakh units, up 23% YoY. The SUV revenue market share was 25%. Consolidated revenue for Auto segment was Rs 34,387 cr, up 32% YoY. PAT was Rs 2,129 cr, up 21% YoY. These are strong revenue and PAT growth numbers, which show that the overall business has good momentum.
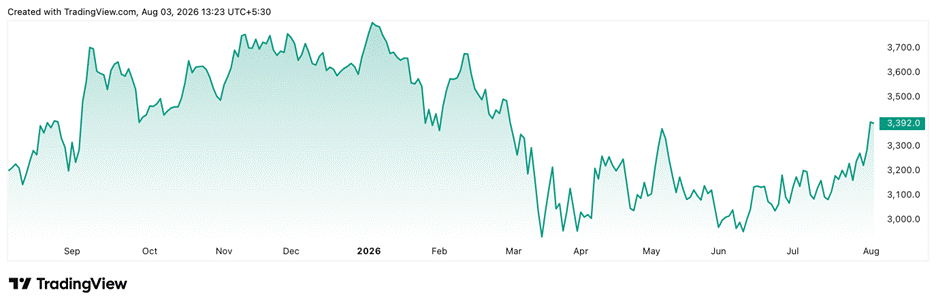
M&M 1-Year Price Chart
Increase in revenue share of EV models
In July 2026, Mahindra sold 7,677 electric SUVs out of a total domestic SUV sales of 60,048. This is equal to a unit sales share of 12.8%. At the close of Q4 FY26, the unit sales share of EV stood at 9.6%. The significant jump in unit sales share in the last few months reflects the triple-digit YoY growth in EV sales for Mahindra.
The company had earlier mentioned a target of reaching 13% to 17% of unit sales share for EV by 2027. However, with the current growth momentum in the EV segment, Mahindra could exceed that target.
A higher unit sales share of EVs in the overall business portfolio creates a big tailwind. The overall revenue and margin trajectory start following the EV business, which can give them good upward momentum.
Tata Motors PV vs Mahindra & Mahindra
| Particulars | Tata Motors PV | Mahindra & Mahindra |
| FY26 sales | Rs 92,120 cr | Rs 42,721 cr |
| YoY volume growth | 43% | 344% |
| Market share | 40.2% | 23.9% |
| EV Revenue | Rs 14,995 cr | Rs 15,089 cr |
| Key Brand | Tiago EV, Nexon EV | XUV 400, XEV 9e |
| Key Growth triggers | Mass adoption, multi-powertrain | Premiumization and Born-EV rollout |
Peer analysis
The return on equity (ROE) of Tata Motors PV was 75.66%, and Mahindra showed an ROE of 20.33%. The industry average was 23.19%. The EV/EBITDA of Tata Motors PV was only 7.10 and for Mahindra it was 11.86. The industry median EV/EBITDA was much higher at 18.11.
The EV business is growing rapidly for both these key players which could deliver good YoY growth in the next few quarters.
| Peer comparison | |||
| Company | EV/EBITDA | Return ratios (%) | |
| Company | ROCE (%) | ROE (%) | |
| Tata Motors PV | 7.10 | 2.73 | 75.66 |
| Mahindra & Mahindra | 11.86 | 15.10 | 20.33 |
| Industry Median | 18.11 | 19.65 | 23.19 |
To conclude, both Tata Motors and Mahindra & Mahindra have a long growth runway in expanding the overall EV market base in India. They could also deliver strong results in international markets due to labour cost advantage, affordable pricing, and the China Plus One trend evolving in key markets.
Add these stocks to your watchlist to track how the penetration progresses in the coming years
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Rohit is a seasoned financial writer with over a decade of experience covering Indian and international stocks. He specializes in converting complex financial data into actionable insights that can help readers make better calls. He covers macroeconomic trends globally, which gives a better analysis of the growth runway for companies in key sectors.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.