



India’s industrial activity remained on a firm footing during the April-June 2026 quarter, with the overall Index of Industrial Production (IIP) rising 5.8% year-on-year to 121.3 in April-June, from 114.7 in the corresponding quarter of the previous fiscal year.
The momentum strengthened further towards the end of the quarter, that is, in the month of June, as depicted by the quick estimates of IIP. The index grew by 7.3% YoY during June, as compared to a 5.1% YoY growth during May. The growth was supported by solid growth across the core industrial sectors. Capital goods production grew by 14.2%, followed by the electricity and gas supply sector, which grew by a significant 10.6%, and the manufacturing sector, which grew by 7.8% during the month, showing strong signs of recovery and growth.
Apart from the IIP data, another factor that is perhaps a testament to this industrial sector growth is Foreign Institutional Investors (FIIs) increasing their stake in industrial product companies.
During the April-June 2026 quarter, FIIs raised their stake in three industrial product companies at a significant pace, which perhaps reflects their conviction related to the sector.
In this article, we will explore these three stocks and try to understand whether it is just the overall industrial growth or business-specific factors that drew FIIs’ attention.
Join now
#1 Welspun Corp Limited: Global Leading Manufacturer of Large Diameter Pipes
Welspun Corp Ltd. is engaged in manufacturing large diameter pipes, and it is one of the largest manufacturers of the same across the globe. The company manufactures TMT rebars, BIS-certified steel billets, ductile iron (DI) pipes, stainless steel pipes, and more.
During Q1FY27, FIIs raised their stake by 3.38 percentage points, taking the total holding to 14.6% at the end of the quarter.
A Global Orderbook of Rs 25,750 crore
As of 27 July 2026, the company had a global orderbook worth Rs 25,750 crore, offering a solid medium to long-term revenue visibility. One of the largest orders received during the April-June quarter was for supplying LSAW pipes worth Rs 700 crore.
The company also received two significant orders during July 2026, which include an order of Rs 1,400 crore for supply of pipes for oil and gas export projects. This order is scheduled to be executed over FY27 and FY28, offering solid revenue visibility for the upcoming two fiscal years.
Towards the end of July, the company received another fresh order worth Rs 960 crore, which shot up the orderbook to its current level. This order is for the supply of coated line pipes and is to be executed within FY28.
Management stated that their current orderbook is one of the strongest in the history of the business; however, they also raised concern about the orderbook being skewed towards US orders.
Welspun Corp products are in high demand across different sectors in the US, especially onshore and offshore oil pipelines, AI data centres, and LNG exports.
The management has indicated that around 75% to 80% of the orders from the US are linked to LNG and Gulf Coast exports, while the remaining 20% to 25% are for data centres.
They also indicated that orders linked to gas turbines are increasing sharply, with over 300 orders linked to gas turbines in the current orderbook.
Middle East: The Next Growth Leg
Welspun Corp is anticipating significant progress in the Middle East with large-scale investment by Aramco, a state-owned oil company in Saudi Arabia, in the oil and gas sector. The management expects this investment to boost the demand for large-diameter pipes, which are essential for oil and gas transportation.
Apart from the oil and gas sector, water infrastructure projects are expected to drive demand for long-distance pipelines and for building water transport networks in the Middle East.
Another factor that is expected to boost Welspun Corp’s orderbook, especially for the line pipes, is reconstruction and infrastructure requirements across the region.
42% Profit Growth in Q1FY27
Sales increased from Rs 3,551 crore in Q1FY26 to Rs 4,081 crore in Q1FY27, reflecting a 15% YoY growth.
Earnings before interest, tax, depreciation, and amortization (EBITDA) surged by 35% YoY to Rs 756 crore in Q1FY27, from Rs 560 crore in the corresponding quarter last fiscal year.
Profit after tax (PAT) without exceptional items grew by 42% YoY from Rs 350 crore to Rs 499 crore during the period.
According to management’s guidance for FY27, the overall revenue for this fiscal year could increase to Rs 20,000 crore, compared to the Rs 16,770 crore generated in FY26, while the EBITDA could rise up to Rs 2,850 crore for the entire fiscal year, up from the actual EBITDA of Rs 2,371 crore generated during FY26.
Return on capital employed (ROCE) of the company stood at 22.9%, compared to 13% of the industry median. The company also has a higher-than-industry dividend yield of 0.27%, while that of the industry is negligible.
Is the stock fairly priced?
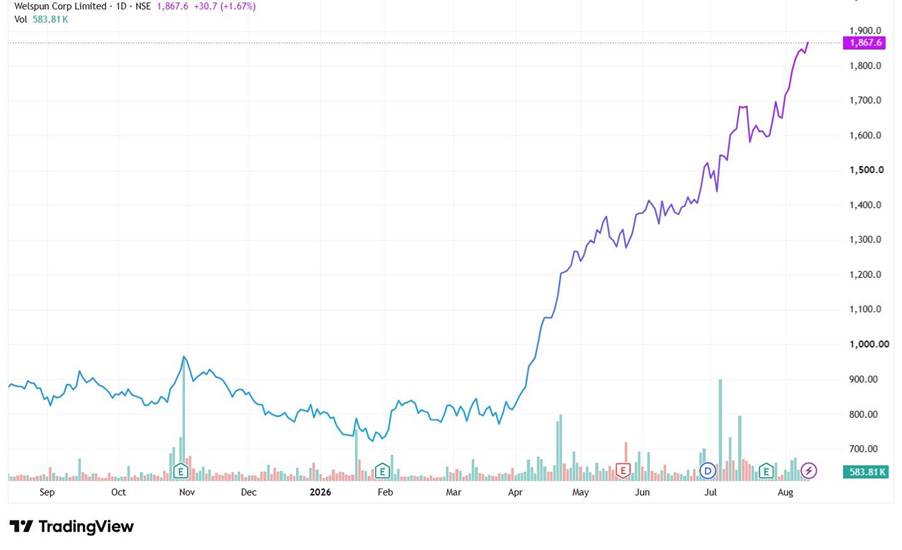
The stock is currently trading at a price-to-earnings (PE) ratio of 21.3x, compared to the industry median of 21.6x; however, the price-to-earnings-to-growth (PEG) ratio is 0.18x, compared to the industry median of 0.75x, indicating that the stock could be relatively undervalued compared to its peers, if adjusted for growth.
1-Year Share Price Chart of Welspun Corp Ltd.
#2 KRN Heat Exchanger and Refrigeration Limited: Offering Thermal Solutions Across Industries
KRN Heat Exchanger and Refrigeration Ltd. is engaged in the manufacturing of heat exchangers and related thermal solutions, which are used across industries such as Heating, Ventilation, and Air Conditioning (HVAC), refrigeration, railways, data centres, transport, automotives, power, marine, commercial buildings, and more.
The company’s product portfolio includes Fin & Tube, Bar and Plate, refrigerator components, complete HVAC systems, micro channels, technical tubes, and more.
FIIs raised their stake by 2.2 percentage points during the April-June 2026 quarter in this company, taking the total holding to 8.86% at the end of the quarter.
New HVAC Facility: Capacity Ramp-up
KRN is expanding its HVAC products facility, which is expected to drive its next growth phase. The company has already commissioned Plant II expansion in May 2025.
Around 85% of the existing capacity of the KRN HVAC facility (Plant I) was already being utilised, and this new plant thus increased the production capacity by 6 times.
The capex for this new plant is around Rs 350 crore as of today, of which Rs 241 crore has been sourced from IPO proceeds only.
The existing capacity offers a revenue of around Rs 450 crore annually, while this new facility can increase the revenue up to Rs 2,850 crore at optimum utilisation, which is expected by FY28.
The new facility has expanded KRN’s portfolio beyond traditional fin-and-tube heat exchangers into products such as wire-and-tube condensers, roll-bond evaporators, frost-free evaporators, skin condensers, bar-and-plate heat exchangers, dry air coolers, ammonia evaporators, and others.
During the April-June quarter, the company also received two fresh orders for the HVAC segment. One is an export order worth Rs 55 crore, and the other is a domestic order worth Rs 43.1 crore, both for supplying heat exchanger coils.
Bus AC: New Growth Vertical
KRN entered the Bus AC business during FY26 through the acquisition of the assets and team of Sphere Refrigeration Systems.
With this acquisition, KRN is moving from being primarily a component supplier to a full Bus AC system assembler, with the final target of becoming a full railway HVAC systems supplier. The company expects this business to have higher gross margins than its existing heat-exchanger business.
The management has anticipated revenue from this segment for FY27 to be around Rs 160 crore and is also targeting to capture a market share of around 15%, out of the total projected market size of Rs 1,000 crore.
During this financial year, the company has planned to start production of full conventional and electric Bus Acs, and in FY28, KRN is targeting to enter the railway coach HVAC systems (passenger coaches).
44.6% Jump in Profits
Total income of the company grew by 38.06% YoY during FY26, from Rs 441.7 crore in FY25 to Rs 609.8 crore in FY26.
EBITDA jumped from Rs 70.5 crore to Rs 112.5 crore, growing at 59.5% YoY, while net profit for the period jumped from Rs 52.9 crore to Rs 76.5 crore, logging 44.6% YoY growth.
Note: Q1FY27 Financial Results are yet to be announced
KRN has a ROCE of 16.06%, slightly lower than the industry median of 16.2%.
Already trading at a premium?
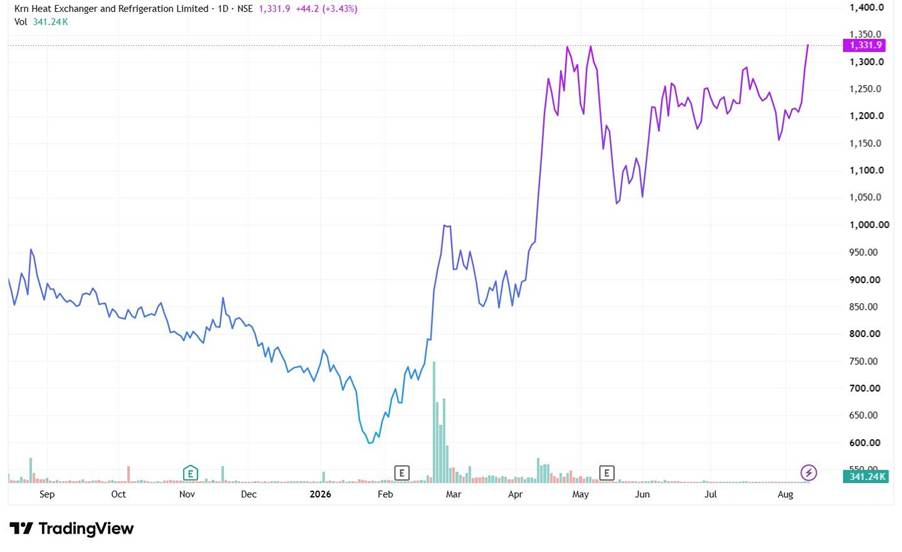
The stock is trading at a PE of 113.4x, way higher than the industry median of 23.9x, reflecting that the stock is relatively overpriced than its peers.
1-Year Share Price Chart of KRN Heat Exchanger and Refrigeration Ltd.
#3 Aeroflex Industries Limited: Leading Metallic Flexible Flow Solutions Manufacturer
Aeroflex Industries Ltd. is one of the leading manufacturers of metallic flexible flow solutions in India. The product portfolio includes SS Flexible hoses, assemblies, and fittings consisting of pre-fabricated components, metal bellows, miniature metal bellows, composite hoses, specialised industrial hoses, and more.
FIIs increased their stake in this company by 2.12 percentage points during Q1FY27, taking the total holding to 3.61% at the end of the quarter.
Data Centre Cooling Emerges as a Major Growth Driver
During Q1FY27, Aeroflex witnessed its liquid cooling business grow significantly on the back of increasing demand for data centre cooling in India. Revenue from Secondary Fluid Network (SFN) skid assemblies contributed around 23% of the total revenue for the quarter. SFN Skid assemblies are used for controlling coolant circulation across data centre cooling systems for managing pressure and preventing leaks.
To cater to the growing demand, the company is expanding its skid-assemblies segment. Already, the company has increased annual production capacity from 6,000 skids to 9,000 skids and has a plan to expand this further to 15,000 skids in a year.
The company is infusing Rs 48 crore for the ramp-up, and by Q3FY27, the management expects to commission the 15,000-skid capacity, and by FY28 they expect to utilise the capacity optimally.
Flexible Hoses Still Provide the Core Base
While the SFN business segment is growing rapidly, the conventional flexible-hose business remains important to Aeroflex as well.
Currently, the company has a flexible-hose capacity of 17.5 million metres per annum, which the company is planning to increase up to 20 million metres by Q3FY27.
The management estimates peak revenue potential of Rs 650 crore to 675 crore from flexible hoses, including assemblies, assuming 70% of sales come from assemblies.
The margin profile also looks better for value-added products, as management indicated margins of 16% to 20% for standalone flexible hoses versus 22% to 26% for assemblies.
162% Profit Growth in Q1FY27
Total income of the company grew by 72.4% YoY during the quarter from Rs 84.7 crore in Q1FY26 to Rs 146 crore in Q1FY27.
EBITDA jumped by 116.4% YoY from Rs 15.5 crore to Rs 33.5 crore during the period.
Profit grew by 162.22% YoY from Rs 7.2 crore in Q1FY26 to Rs 18.8 crore in Q1FY27.
The company has a ROCE of 18.9%, higher than the industry median of 13%, and the dividend yield is 0.09% compared to the industry median, which is negligible.
Already trading at a premium?
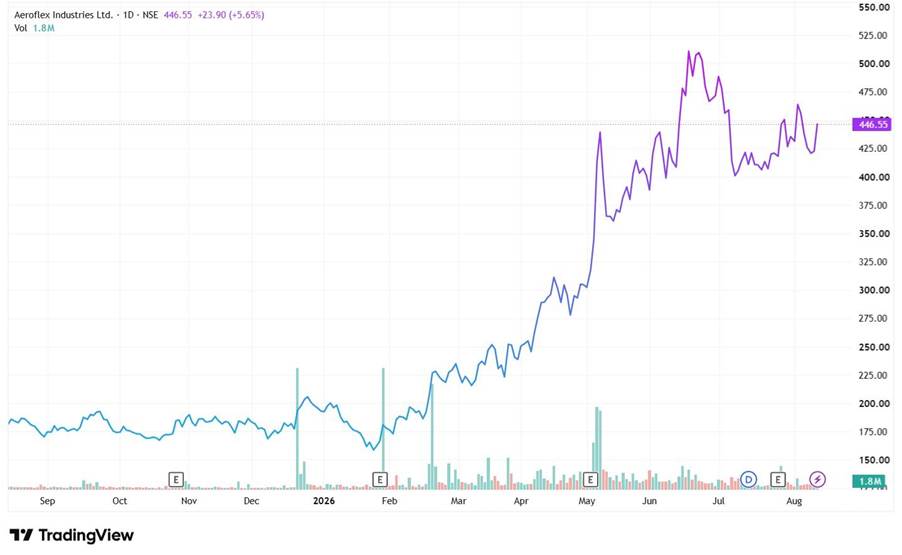
The stock is trading at a PE of 87.9x, against the industry median of 21.3x, while the PEG ratio of the stock is 4.5x, compared to the industry median of 0.6x, reflecting that the stock is relatively overpriced, even if growth is factored in.
1-Year Share Price Chart of Aeroflex Industries Ltd.
Will FIIs’ Conviction play out?
The rise in FII ownership across these three industrial stocks reflects a broader shift towards companies positioned to benefit from India’s industrial and infrastructure expansion. Though the investment case differs for each stock, strong growth prospects remain a common theme for all three. So, whether FIIs’ conviction will play out or not, only time will tell, and for that, you need to add these stocks to your watchlist and monitor their future performance.
We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
Maumita Mitra is a seasoned writer specializing in demystifying the world of investment for a broad audience. She has a keen eye for detail and a knack for explaining complex financial concepts in the simplest manner possible.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting such independent advisors as may be necessary.