



Nowadays, whenever we talk about the automobile sector, it is mostly about electric vehicles (EVs). While India has been making significant progress in the field of EVs, the auto ancillary industry catering to both EVs and conventional vehicles has silently entered its next growth phase.
The automobile and automobile-component PLI scheme of the government has already attracted investments worth Rs 44,326 crore by the end of March 2026, while the overall target was Rs 42,500 crore by the end of March 2027.
Both Foreign Institutional Investors (FIIs) and Domestic institutional investors (DIIs) raising stakes in select auto-components companies aggressively during the same timeframe is perhaps another sign of this industry entering its next phase of growth.
Expanding Institutional Confidence
During the April-June 2026 quarter, FIIs and DIIs bought two auto-component stocks, increasing their stake by as much as 8% cumulatively.
In this article, we will explore these two auto-ancillary stocks and try to understand the rationale behind institutional investors buying them at such an aggressive pace.
#1 NRB Bearings Limited: From Bearings to High-Value Engineering
NRB Bearings Ltd. is a leading manufacturer of needle roller bearings since 1965. Almost 90% of the vehicles running on Indian roads have bearings manufactured by this company. Apart from needle roller bearings, the company has a product portfolio of more than 2,000 other auto-components, including special rollers, crank pins, cages, washers, spacers, and others.
Join now
As per management, the company is now entering higher-value automotive application space and other sectors like electrification, robotics, heavy construction equipment, and other mission-critical friction applications.
During Q1FY27, FIIs raised their stake by 4.23 percentage points, taking the total holding to 18.9%, while DIIs raised their stake by 3.79 percentage points, taking the total holding to 13.85% at the end of the quarter.
NRB Bearings’ EV-Agnostic Approach
While the automobile industry is running after EVs, NRB is maintaining its stance on being EV-agnostic. As per management, most of the company’s products and applications are not restricted to EVs; rather, they can be relevant across internal combustion engine (ICE), EVs, as well as hybrid models. The products include chassis, transmission-related applications, and even steering wheels and others.
This diversified approach of the company is perhaps one of the reasons that has attracted institutional investors to raise stakes.
During Q1FY27, NRB also launched one of its next-generation hybrid platforms for steering applications for BMW and is currently developing applications for other tier I customers such as Mercedes-Benz and its electric models.
NRB is not just diversifying across EVs and conventional vehicles; it is increasing its footprint in the industrial space as well.
During the quarter, revenue from the industrial business segment grew by 14%, up from 11% in the year-ago period.
The company also added new customers in this segment, which include HAAS Automation USA and JCB UK, helping the company grow its presence across the industrial mobility space.
NRB’s Aerospace and Defence Bet
NRB is not restricting itself to just four-wheelers or passenger vehicles. The company acquired Mahant Tool Room (MTR) in July 2026 via its subsidiary to venture into an estimated $14.5 billion to $16.5 billion global aerospace components space.
The company has already secured its first aerospace and defence bearings orders for a mission-critical Sukhoi-30 application.
Profitability Metrics & Valuation
Revenue stood at Rs 370 crore in Q1FY27, up by 19.2% YoY from Rs 310 crore in Q1FY26.
Profit after tax (PAT) grew by 15% YoY to Rs 38 crore from Rs 33 crore during the period.
Return on capital employed (ROCE) stood at 18.4%, higher than the industry median of 16%; NRB has a relatively higher dividend yield compared to its peers. Currently, it is 1.7%, while the industry median is just 0.3%.
Already trading at a premium?
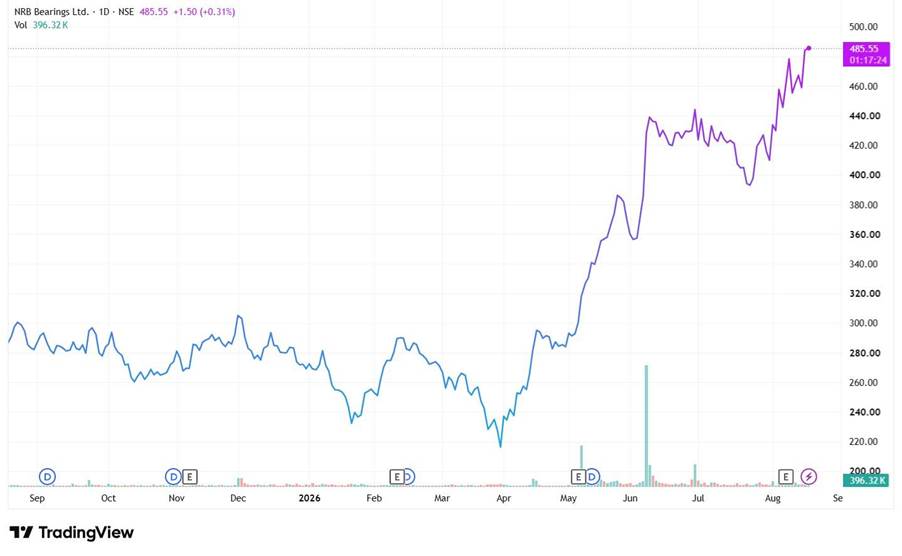
The stock is currently trading at a price-earnings (PE) of 31.4x, while the industry median is 29.7x, and the price-earnings to growth (PEG) ratio is also 2.4x, while the industry median is 0.96x, indicating that the stock is relatively expensive even if adjusted for growth.
1-Year Share Price Chart of NRB Bearings Ltd.
#2 Craftsman Automation: A Diversified Engineering Play
Craftsman Automation Ltd. is a leading manufacturer of machining critical engine and transmission components for Medium and Heavy Commercial Vehicles (M&HCVs) and tractors. The company operates across three main business verticals, which are powertrain, aluminium products, and industrial and engineering products. From product design to manufacturing and assemblies, Craftsman Automaton is an end-to-end solutions provider in this space.
FIIs raised their stake in this company by 2.09 percentage points during the first quarter of FY27, taking the total holding to 17.28%, while DIIs raised their stake by 4.61 percentage points, taking the total holding to 32.9% at the end of the quarter.
Rs 1,500 Crore Capex Cycle Underway
Craftsman Automation is expanding at a robust pace with Rs 1,500 crore of capital expenditure underway.
The company is constructing a new facility at Hosur (Unit 3), which is intended for manufacturing high-pressure die-casting for automotive components. The products will cater to both two-wheeler and four-wheeler customers.
Management has indicated that this facility will be built over two years in phases.
For Phase I and Phase II, the estimated investments are Rs 100 crore and Rs 150 crore respectively. Management has indicated that these two phases will probably be commissioned in the next six to eight months.
As the aluminium segment of the company has been rapidly growing and receiving new orders for both two- and four-wheelers, this new facility is expected to boost the production of the company, as the existing aluminium facility was already running at over 85% capacity.
Another significant project which is currently underway is the Kothavadi Project. The management expects this project to generate over $100 million in revenue by FY29.
Heavy-Horsepower Engines Could Become A Major Business
Craftsman Automation is witnessing significant opportunity in the heavy-horsepower engines space. The company has already received five significant orders in this space, and another order is expected soon.
The company had a target of achieving $100 million of revenue from this segment by FY30, which now seems achievable as the cumulative order value just from the first four orders crosses this mark of $100 million.
Earning Growth vs. Current Valuation
Revenue jumped by 36% YoY to Rs 2,432 crore in Q1FY27 from Rs 1,784 crore in Q1FY26.
PAT for this period surged by 116% YoY to Rs 151 crore, from Rs 70 crore in the corresponding quarter last fiscal year.
ROCE stood at 13.9%, a little below the industry median of 16%, and the dividend yield is around 0.11%, which is also below the industry median of 0.3%.
A Premium Valuation
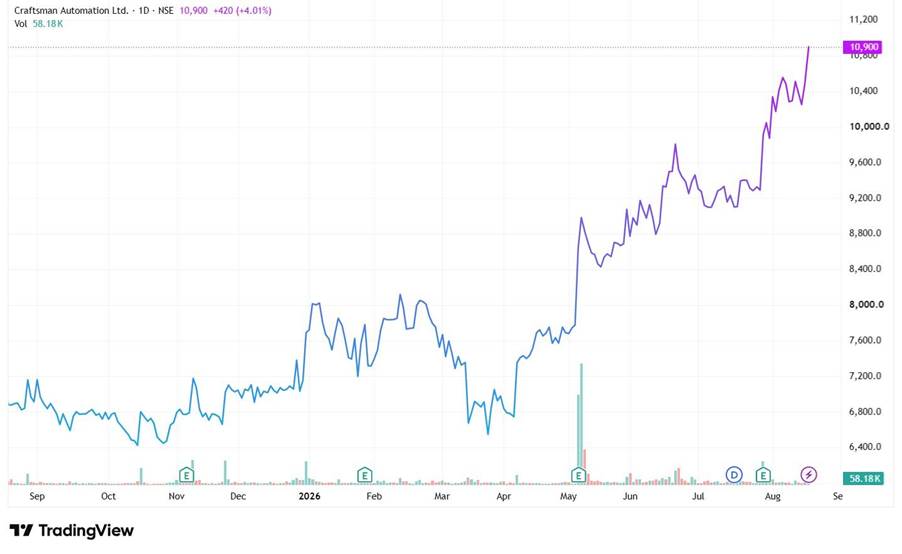
The stock is already trading at a PE of 60.8x, against the industry median of 30.4x, and the PEG ratio is 0.9x, lower than the industry median of 0.96x, reflecting that the stock is relatively overpriced, even if the growth potential is factored in.
1-Year Share Price Chart of Craftsman Automation Ltd.
Is this Institutional Buying Aligned with the Bigger Growth Story?
The rising interest of both FIIs and DIIs in NRB Bearings and Craftsman Automation comes at a time when India’s auto-ancillary industry is entering a broader growth cycle. Both companies are expanding beyond their traditional businesses, with NRB targeting industrial, aerospace and defence applications, while Craftsman is scaling its aluminium, powertrain and industrial businesses through fresh capacity and large capex commitments.
However, as both companies are already trading at premium valuations, execution of the new orders, timely completion of the capacity addition projects and thorough implementation of diversification plans will dictate sustained revenue growth and stronger returns over the next few years. Thus, for now, adding these stocks to your watchlist to keep an eye on them could be a wise decision.
We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
Maumita Mitra is a seasoned writer specializing in demystifying the world of investment for a broad audience. She has a keen eye for detail and a knack for explaining complex financial concepts in the simplest manner possible.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting such independent advisors as may be necessary