



SME Strategy: Why Ashish Kacholia Hunts in Illiquid Waters
Most star investors fish in the main market. Ashish Kacholia also fishes in a smaller pond that most people never visit. The SME exchanges, where small and medium enterprises list, have quietly become his hunting ground. As per the latest shareholding disclosures, he holds stakes above 1% in dozens of listed companies, and a growing number of them are SME names that few retail investors have heard of.
His method is simple to describe but hard to copy. Buy young companies early. Accept that some will fail. Let the winners grow into their valuations over years, not weeks. It is the same playbook that turned several of his earlier small cap picks into household names among market watchers.
Two of his current SME bets sit in the hottest theme in the markets right now, which is defence. One makes precision tooling for aerospace and defence customers. The other builds defence electronics and software driven systems. Both have logged triple digit compounded profit growth over 5 years. Both have also fallen sharply from their 52-week highs. And in both, Kacholia raised his stake while the price fell. That combination deserves a closer look.
Join now
SME Risks: Navigating Liquidity Traps and Six-Month Blind Spots
Both these stocks trade on the NSE Emerge platform, and that changes the rules of the game. SME stocks trade in lots, not single shares, so the minimum ticket size is larger. Daily volumes are thin, which means exits can be slow and painful exactly when you need them to be quick. Price circuits can lock you in or out for days.
Disclosure standards are lighter too. SME companies report results half yearly, not quarterly, so investors fly blind for six months at a stretch. Analyst coverage is close to zero. Shareholder counts are tiny, which is fertile ground for sharp price swings. A handful of large buyers or sellers can move these stocks violently in either direction.
TechEra Engineering: High Margins, Big Moats, and Shrinking Promoter Skin
Incorporated in 2018, TechEra Engineering (India) Ltd designs, manufactures and supplies precision tooling and components for the aerospace and defence industries. The company listed on the NSE Emerge platform in September 2024.
With a current market cap of Rs 274 cr, TechEra is a genuine microcap. Its work includes tooling for aircraft assembly lines and automation systems, a niche where quality certifications act as a wall against casual competition.
Kacholia’s name first appeared in the company’s shareholding data with a 2.11% stake in the December 2025 quarter. He raised it to 3.51% by March 2026 and held 3.57% as of June 2026.
Alongside, Suryavanshi Commotrade Private Limited, also one of his holding companies, Kacholia has held a steady 2.72% across the same period. Taken together, that is a combined holding of about 6.3%, worth roughly Rs 17 cr at the current market cap.
Now look at what the business has done over 5 years.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Yr CAGR |
| Sales/Rs Cr | 8.3 | 7.2 | 26.4 | 38.8 | 49.5 | 48.5 | 42% |
| EBITDA/Rs Cr | 1.5 | -3.7 | 4.1 | 6.9 | 8.6 | 8.4 | 42% |
| Net Profits/Rs Cr | 0 | -6.3 | 1.3 | 2.8 | 3.2 | 3.1 | Turnaround |
EBITDA refers to operating profit before other income. FY21 was a loss-making year, so a 5-year profit CAGR is not meaningful. But there is a clear turnaround in profit terms.
The honest reading is in the table itself. Sales grew 6 times in 5 years, from Rs 8.3 cr to Rs 48.5 cr. Profits turned positive in FY23 and have hovered around Rs 3 cr since.
And that is where the worry starts. FY26 sales at Rs 48.5 cr were marginally below FY25. Net profit at Rs 3.1 cr was flat.
49% Correction: Do the Fundamentals Justify the Valuation?
The share price of Techera Engineering was around Rs 137 when listed in October 2024 and as of closing on 5th August 2026 it was Rs 166.
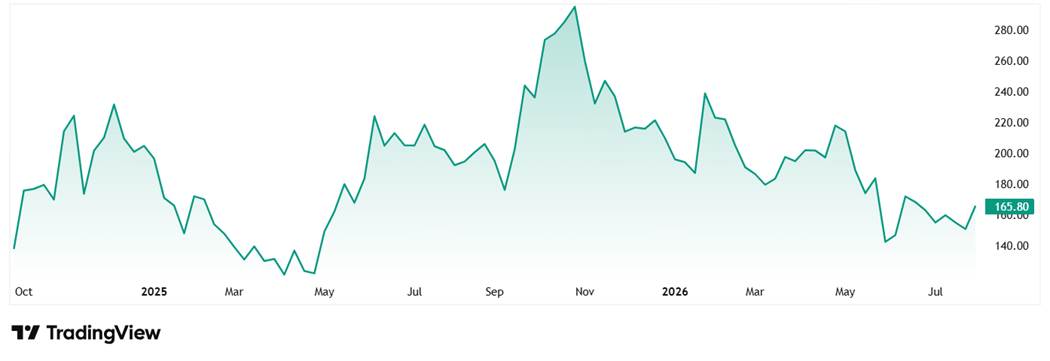
At the current price of Rs 166, the stock has seen a steep correction from its 52-week high, which is also its all-time high, of Rs 326. That’s a fall of roughly 49%. It remains well above its 52-week low of Rs 128.
Regarding valuations, the stock trades at a PE of 122x which is much higher when compared to the industry median of 66x. A 10-year median PE comparison, which we normally use to judge such valuations, is not possible here since the company has been listed for under two years, so no such history exists for the stock.
Swelling Debtor Days and a CFO Exit
There are governance and quality flags a careful reader should not skip. Promoter holding has dropped from 42.3% in September 2024 to 36.9% by June 2026. Domestic institutions, who held over 15% at listing, have exited almost entirely. Debtor days have swelled to 178, which means the company waits nearly half a year to collect its dues. And in July 2026, the CFO resigned, with the promoter’s son stepping into the role.
On the brighter side, the order flow has not dried up. In August 2026, the company announced two fresh domestic orders worth Rs 4.1 cr along with an export order of about US$ 200,000. Small numbers, but for a company with Rs 48.5 cr in annual sales, every order counts.
C2C Advanced Systems: A 171% Growth Engine Masking a 600-Day Cash Crunch
Incorporated in 2018, C2C Advanced Systems Ltd is a vertically integrated defence electronics company. It builds software driven systems and sub systems for air, sea and land defence platforms, using AI, big data analytics and embedded systems.
The company’s market debut in December 2024 was pure drama. The listing was delayed after the market regulator asked for an independent auditor review of its financials. The IPO was still subscribed about 125 times, and the stock listed at Rs 430, a 90% premium to the issue price of Rs 226.
Kacholia was in early, like he usually is. He held 2.6% in December 2024, the quarter the stock listed. He held that through March 2025, then raised his stake to 3.9% by September 2025. As of March 2026, he held 3.82%, worth about Rs 17 cr at the current market cap of Rs 445 cr. Since this is an SME, the financials are reported only twice a year in March and September.
Here is the 5-year financial picture.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Yr CAGR |
| Sales/Rs Cr | 1 | 0 | 8 | 41 | 115 | 146 | 171% |
| EBITDA/Rs Cr | 0 | -2 | 4 | 18 | 41 | 23 | NM* |
| Net Profits/Rs Cr | -0 | -2 | 3 | 12 | 29 | 18 | NM* |
EBITDA refers to operating profit before other income. FY21 EBITDA was near zero and net profit was negative, so 5-year CAGRs on these lines are not meaningful (NM). The data shows a 174% compounded profit figure on this distorted base. FY26 earnings include other income of Rs 16 cr.
The revenue scale up is real and remarkable. Sales went from Rs 1 cr in FY21 to Rs 146 cr in FY26, a 171% compounded rate. The profit CAGR of 174% that shows up on screens carries the same base year problem as TechEra, since FY21 was a loss year. The year wise numbers matter more, and until FY25 they looked superb.
Then FY26 happened. The second half of the year produced a net loss of Rs 5 cr, with operating margins turning negative. The company took a provision of Rs 14.5 cr, discussed at length in its latest earnings call. Full year profit fell to Rs 18 cr from Rs 29 cr, and even that Rs 18 cr leans on other income of Rs 16 cr.
Why a 72% Haircut Isn’t Always a Value Play
The share price of C2C Advanced Systems was around Rs 430 when it was listed in December 2024 and as of closing on 5th August 2026 it was Rs 265.
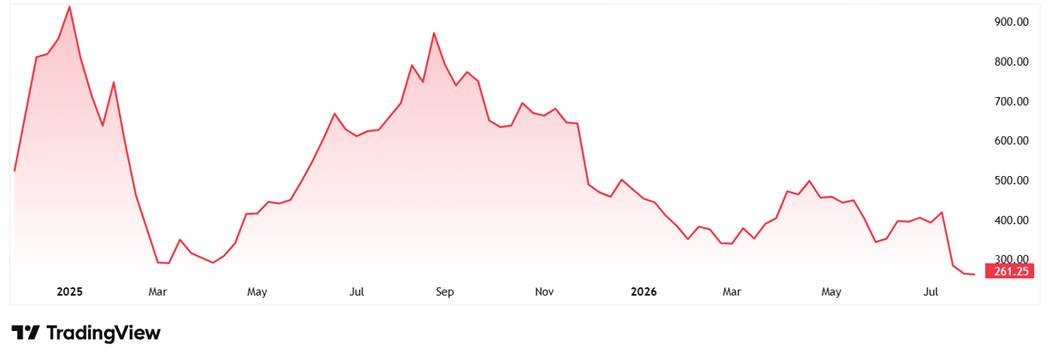
At the current price of Rs 265, the stock has seen a big correction of about 72% from its all-time high of Rs 954.
As for the valuation, the stock is trading at a PE of about 24x which is considerably lower when compared to the current industry median of 67x. A 10-year median PE will add no value to the financials as the company has barely been listed for 2 years.
Balance Sheet Trap: ₹115 Cr Negative Operating Cash Flow
The core problem sits in the balance sheet. Debtor days stand at 602. In plain words, the company takes over a year and a half to convert a sale into cash. Operating cash flow was negative Rs 35 cr in FY24 and negative Rs 115 cr in FY25, even as reported profits grew. A business that books profits but does not collect cash has to borrow, and borrowings have climbed to Rs 55 cr.
Management is acting. A new CEO accepted the role in July 2026, and the company told exchanges it expected Rs 20 cr of receipts by end July and another Rs 60 cr to Rs 75 cr in August. The board has also approved a proposal for preferential warrants, with promoter funding on the table. Whether the cash actually lands is the single most important thing to track here.
Promoter holding has slipped from 41.35% in March 2025 to 37% in March 2026, a drop of 4.35% in the latest reported quarter alone.
Decoding Kacholia’s High-Risk Defence Portfolio Strategy
The obvious question is why one of India’s sharpest small cap investors keeps adding to two stocks with falling prices, stretched receivables and shrinking promoter stakes. Nobody can read his mind, but his track record offers a clue.
Kacholia’s SME bets are structured like a venture capital portfolio inside the public market. Each position is small in absolute terms. His roughly Rs 17 cr in each of these two names is a sliver of a portfolio reported to run into thousands of crores. Some bets will go to zero. A few need to grow 10 times to pay for the rest.
The theme behind both bets is also bigger than either company. India’s push to build defence equipment at home has created a long runway for small suppliers with real certifications and real order books. TechEra’s aerospace tooling niche and C2C’s defence electronics stack both sit on that runway. The bull case is that today’s messy numbers are the growing pains of businesses scaling faster than their systems.
The bear case is equally clear from the same tables. One company earns Rs 3 cr and is priced at 122 times that. The other reports profits it has not collected in cash. Triple digit growth screens attract crowds, and crowds in illiquid SME stocks are how 70% drawdowns happen.
For readers, the takeaway is not to copy the trade. It is to study how a master allocator sizes risk in the riskiest corner of the market. Watch whether C2C collects its promised cash by September. Watch whether TechEra’s order wins translate into profit growth in FY27. The next two half yearly results will answer more than any headline can. Adding both names to a watchlist costs nothing. Following a star investor blindly into an SME stock can cost a great deal.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.