



Retail investors usually learn where the big money went by reading a shareholding filing weeks after the fact. Occasionally the trail is stranger. Two energy names now carry Ashish Kacholia’s name, and in neither case did he walk in and buy at whatever the screen was quoting that morning.
Put the two businesses side by side and an obvious story writes itself. One recovers metal from dead batteries and sells the theme every fund manager follows, recycling and the circular economy. The other runs seismic surveys and maintains oilfields, about as old-school as energy gets. New versus old, one investor, one quarter.
Here is what makes the story even more interesting. The recycler makes its money from lead-acid batteries, the oldest chemistry still in commercial use. The oilfield services firm now draws roughly 40% of its order book from minerals rather than hydrocarbons. Neither is a wager on which way the transition breaks. Both get paid either way. Let us go through them one at a time.
Join now
#1 Ardee Industries: The 12% Pre Listing Gains
Incorporated in 1993, Ardee Industries recovers and recycles end-of-life lead-acid batteries and non-ferrous metal scrap. Out the other end comes high purity refined lead and made-to-order lead alloys, used in energy storage, automotive, e-mobility, cable, chemical and telecom applications. Put plainly, it takes apart dead batteries and sells the metal back to the people who make new ones.
The Pre-IPO Discount Retail Didn’t Get
The company was listed this week on 12th August 2026 with an issue worth about Rs 426 cr, a fresh issue of Rs 320 cr plus an offer for sale of about 2 crore shares worth Rs 105.9 cr. The price band was Rs 50 to Rs 53. The issue saw substantial investor attention: the book closed 133.66 times subscribed, drew bids worth roughly Rs 41,387 cr, and pulled in about 40.39 lakh applications.
Kacholia was already inside twice over. Bengal Finance & Investment, a company he is invested in, took 47.17 lakh shares in the anchor book at Rs 53, worth Rs 25 cr and about 1.5% of the company. That book was allotted on 4th August, a day before the issue opened, and raised Rs 128 cr in all, with Bank of India Small Cap Fund and Rohit Kothari’s Winro Commercial taking the same size each.
Before that, on 24th and 27th July, he joined pre-IPO secondary transactions worth around Rs 115 cr at the same Rs 53 through his personal portfolio, which is a holding of 1.2%. His price was fixed weeks before anyone else could act, and fixed at the top of the band rather than below it.
The Math Behind the Margin Spikes
One caution first. Ardee has only four years of published financials, so a five-year growth rate cannot be calculated and I have not manufactured one. Here is the full record instead.
| Financial Year | FY23 | FY24 | FY25 | FY26 | 3-Yr CAGR |
| Sales (Rs cr) | 412 | 463 | 743 | 1,168 | 42% |
| EBITDA (Rs cr) | 23 | 28 | 66 | 147 | 86% |
| Net Profit (Rs cr) | 9 | 9 | 33 | 85 | 111% |
EBITDA is operating profit before other income. Sales rose about 57% in FY26 alone, and profit did far better, because the gain is margin rather than volume. Operating margin climbed from 5.6% in FY23 to 12.6% in FY26, more than doubling the profit earned on every rupee of sales.
On a business this working-capital heavy, that matters more than the headline growth. Return on capital employed (ROCE) was 49.1% in FY26, return on equity (RoE) was 81%, and debtors are collected in eight days.
The Listing Reality Check: Why the 39% Premium Collapsed
As the company is recently listed, there is no history of stock price. Looking at the valuation, the shares of the company are currently trading at a PE of 22x while the industry median is 25x. The company has three trading sessions of price history. There is no PE band, no ten-year median, and any decade-long industry comparison would measure Ardee against a past it did not have.
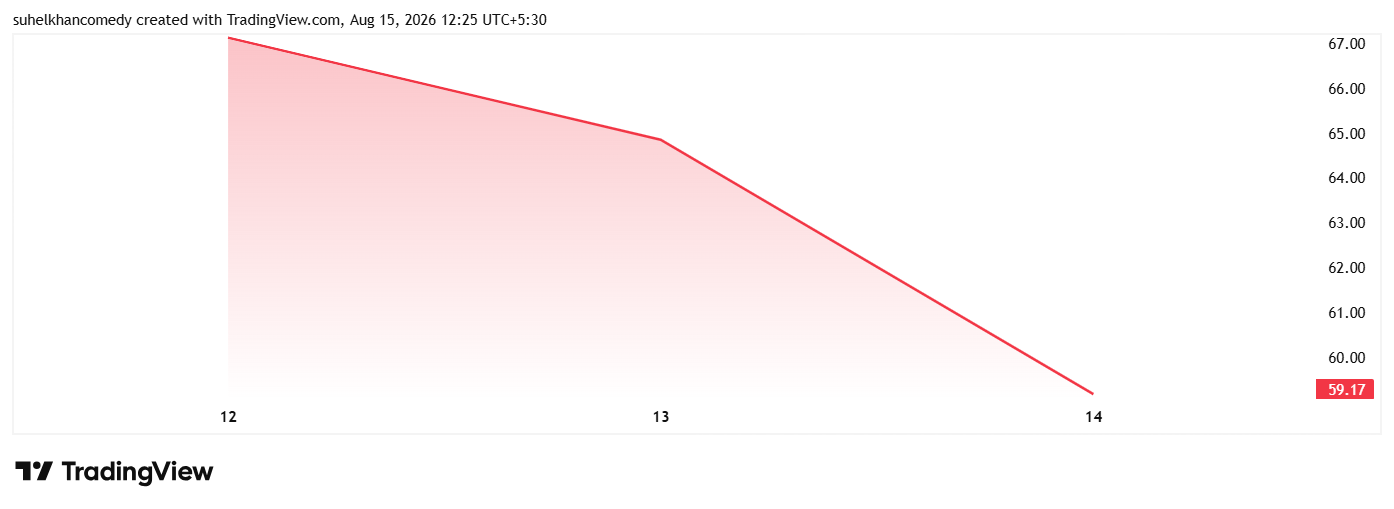
The price does say the early excitement has cooled. The shares opened at Rs 73.6 on the BSE, nearly 39% over the issue price, and Rs 72 on the NSE. As of closing on 14th August 2026, they were at Rs 59.2, still 11.7% above issue but almost 20% below the listing print. Anyone who came in on debut day is underwater. Kacholia, at Rs 53, is not. And that’s how the big whale runs the show.
The Red Flags and What They Mean
Three things deserve attention. Borrowings stood at Rs 184 cr at the end of FY26 against a net worth of Rs 147 cr, a debt-to-equity ratio of about 1.25. That is meaningful leverage for a company whose input costs move with metal prices.
Cash generation is the weak spot. Operating cash flow was negative in FY23 and FY24, turned mildly positive in FY25, and reached Rs 30 cr in FY26. Free cash flow turned positive for the first time only in FY26. That is one year of the business funding itself.
Then the supply calendar. Of the Rs 320 cr fresh issue, Rs 220 cr goes to working capital and Rs 22 cr to repaying debt, so most of the new money funds the balance sheet rather than capacity. Anchor shares come off lock-in in two tranches, half at 30 days and half at 90. Promoter holding has already fallen from 91.48% to 67.62%.
#2 Asian Energy Services: Pivoting from Hydrocarbons to the Minerals Boom
Incorporated in 1992, Asian Energy Services was called Asian Oilfield Services until October 2020. It acquires and processes seismic data, runs and maintains oil and gas facilities, and has pushed into mineral and coal infrastructure. Customers include ONGC, Oil India and Vedanta. Control sits with the Oilmax group.
The 18-Month Lock: Decoding Kacholia’s ₹19 Crore Warrant Conversion
Here the mechanics matter even more. Kacholia was allotted convertible warrants on 5th November 2024 at Rs 335 per share, paying a quarter upfront. He completed the conversion on 5th May 2026, taking 5,74,000 shares. The company raised Rs 131.03 cr in all across 28 non-promoter allottees, with Titagarh Enterprises and Everest Finance & Investment among the others.
That is why his name shows up in the June 2026 quarter and not before. Over that quarter promoter holding fell from 60.75% to 56.14% and public holding rose from 37.05% to 42.19%, the arithmetic of new shares going to non-promoters. His 1.18% stake cost Rs 19.23 cr. At the 14th August close of Rs 374 it is worth Rs 21.5 cr, a gain of under 12% on a price agreed eighteen months earlier.
₹1,754 Crore Order Book: Can Margin Catch Up to Revenue Growth?
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5-Yr CAGR |
| Sales (Rs cr) | 229 | 260 | 110 | 305 | 465 | 791 | 28% |
| EBITDA (Rs cr) | 55 | 66 | -19 | 42 | 66 | 95 | 12% |
| Net Profit (Rs cr) | 23 | 39 | -44 | 26 | 42 | 52 | 18% |
EBITDA is operating profit before other income. Read those growth rates with the middle of the table in view. FY23 was not a soft year, it was a loss of Rs 44 cr on sales that fell by more than half. A rate compounded from FY21 to FY26 smooths that crater into a straight line, which is not what the business did. The recovery since is real: FY26 sales rose about 70% and net profit about 24%. But operating margin slipped to 12% from 14%, so profit growth lagged sales growth by a wide margin.
The standalone order book stood at about Rs 1,754 cr as on 30th June 2026, split roughly 60% oil and gas and 40% mineral services. FY26 also brought the Kuiper acquisition, widening its West Asia footprint. It is absorbing Oilmax Energy at 117 shares for every 10, with the final tribunal hearing held on 7th August and completion guided for September or October.
Evaluating the 160-Day Cash Flow Trap
The share price of Asian Energy Services was around Rs 140 in August 2021 and as of closing on 14th August 2026 it was Rs 374.
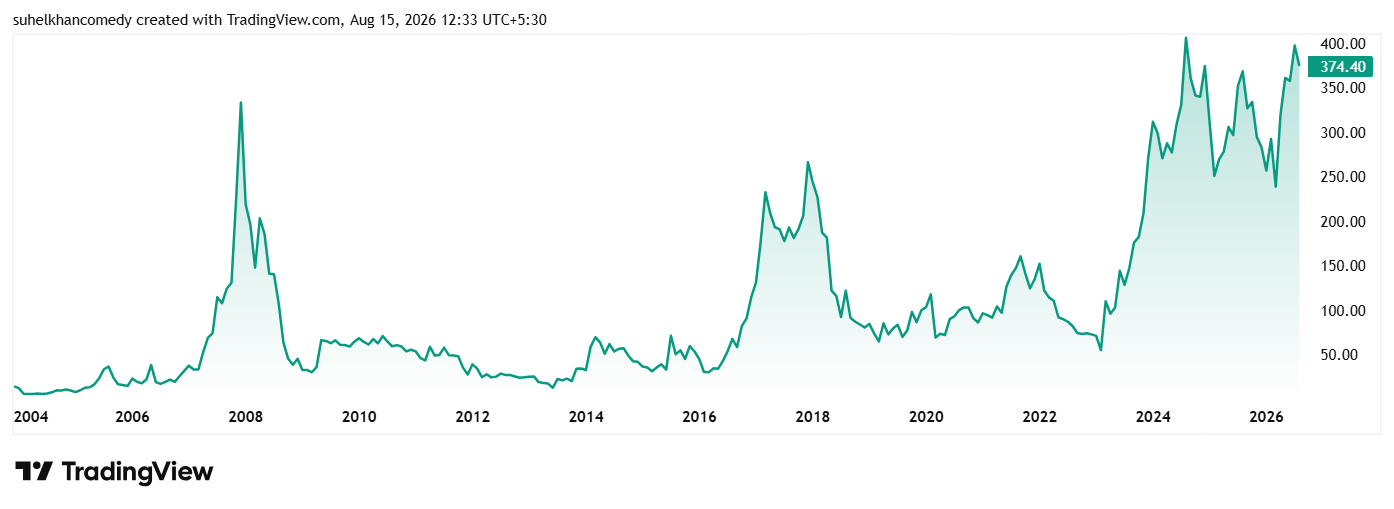
As for the valuation, the company’s share is trading at a PE of 28x against the current Industry PE of 21x. The 10-Year median PE of the company is 26x, while the industry median for the same period is 15x. However, you must note that four of the last ten financial years were loss-making, and a PE calculated on a loss is not really a dependable number.
The balance sheet needs a careful eye. Management describes the company as carrying no net debt, which may be right once cash is set against borrowings. The gross figure still moved from Rs 24 cr in FY25 to Rs 159 cr in FY26. Debtors take 160 days to collect. Free cash flow has been negative three years running, at Rs 73 cr, Rs 52 cr and Rs 8 cr. Services businesses growing this fast tend to swallow cash, and this one has.
The Picks-and-Shovels Verdict: What to Watch as Lock-Ins Expire
If you go back to the frame we started with, positioning for the transition, you would want the recycler and distrust the seismic contractor. But Ardee’s feedstock is the lead-acid battery, the incumbent technology, and its customers make more of them. If lithium took the whole market tomorrow, Ardee’s raw material supply would thin out rather than expand. Asian Energy has already moved four-tenths of its order book into minerals.
Neither is a directional call on which fuel wins. Both sell services and inputs to whoever is digging, refining or recycling. That is a picks-and-shovels position, and a very different bet from the one the sector labels suggest.
The second thread is price. Rs 53 for one, Rs 335 for the other, both agreed before the market had a vote. That is not a better forecast, it is better access, and it is the part a retail investor cannot copy. Ardee today costs about 12% more than what Kacholia paid, after the leverage and thin cash flow record are already public. Asian Energy sits roughly 12% above his conversion price, with a merger awaiting sanction.
What comes next is checkable. The Oilmax merger either completes by October or slips. Ardee’s lock-ins release on a known schedule, and its cash flow either holds the FY26 turn or gives it back. A sensible step is to add these stocks to a watchlist and judge them on those dates, not on the name attached to them.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.