



The IPO Mirage: Why Smart Money Walked Away
On Tuesday, 18th August 2026, Zaggle Prepaid Ocean Services fell to Rs 154, the lowest it has ever traded as a listed company, and below the Rs 164 at which it sold shares in its 2023 IPO. Anyone who bought on day one and held for nearly three years was underwater.
That same afternoon, Kedia Securities bought 20 lakh shares through a bulk deal, at an average of Rs 164.72. The bill came close to Rs 33 cr for 1.48% of the company. The firm belongs to Vijay Kedia, and the market read it the way it usually reads such things. Zaggle closed the next session at Rs 186, up more than 12%.
The second name on this stock is Ashish Kacholia, who held 29,03,356 shares, or 2.2%, at the end of June 2026. Together the two names produce a comfortable story: smart money sees value here. The filings tell a more careful version. Kacholia held the very same 29,03,356 shares at the end of June 2024, when that block was worth 2.4%.
He has not bought or sold a single share in two years. And Kedia’s firm did not appear on the June 2026 disclosed shareholder list at all, meaning his position was either below the 1% reporting threshold or did not exist. This is an arrival, not an addition.
Join now
Unmasking the SaaS Label: The 3% Reality Hiding in Plain Sight
Zaggle sells a spend management solution to companies. Its platforms handle employee expenses, corporate cards, rewards and vendor payments for clients across banking, healthcare and manufacturing. The company positions itself, and is widely recognized, as a fintech SaaS business.
The June 2026 quarter is where that description gets tested. Revenue rose 27.4% over the year to Rs 423 cr. Underneath that number, the company disclosed its mix. Software platform fees brought in Rs 12.5 cr. Program fees brought in Rs 160 cr. Propel Points, the rewards and incentives business, brought in Rs 251 cr.
Run those against the total and the picture changes. Software fees are close to 3% of revenue. Rewards points are roughly 59%, and that line carried a margin of about 7% for the quarter. On the program fee side, cashback ate 66.3% of the fees collected, slightly worse than the 65.7% a year earlier.
This matters because the two deserve very different multiples. Software fees are sticky, high margin and repeat on their own. Points distribution is closer to a pass-through: money comes in, most goes straight back out as cashback, and the company keeps a thin slice. Zaggle is growing fast, but the biggest part of it earns the least per rupee.
When 50% CAGR Collides with a Margins Crisis
The five-year record is impressive, and worth setting out before the criticism.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Yr CAGR |
| Sales (Rs cr) | 240 | 371 | 553 | 776 | 1,303 | 1,853 | 50% |
| EBITDA (Rs cr) | 28 | 60 | 48 | 71 | 115 | 181 | 45% |
| Net Profit (Rs cr) | 19 | 42 | 23 | 44 | 87 | 133 | 48% |
The table is standalone for a reason: the consolidated series only begins in FY23, because the group as it exists today was assembled through acquisitions after that, so a five-year comparison has to run on the parent. On the consolidated books, FY26 revenue was Rs 1,908 cr and net profit Rs 139 cr, so the shape is similar.
Now the quarter that broke the stock. Revenue of Rs 423 cr was up 27.4%, but reported operating profit rose just 1.3% to Rs 31 cr. Operating margin fell to 7.3% from 9.2%. Net profit dropped 32.9% to Rs 17.5 cr. Against the March quarter, revenue was down 32% and profit down 57%.
Management named the causes. The company bought the assets of Dice Enterprises, a Pune spend management firm, in May 2026, and is carrying its costs before any of its revenue arrives, which it expects from the September quarter.
It absorbed costs from a credit card business acquired last year and rebranded, moved previously capitalised expenses into the profit and loss account, and paid salary increments. The chairman called the quarter an inflection point and a move from a decade of profitable growth into a phase of consolidation.
All of that may be true. It is also true that the company had guided for 40% to 45% revenue growth and 10% to 11% margins, and delivered 27.4% and 7.3%. Missing both ends of your own band in one quarter is what took the stock to a 20% lower circuit on 17th August.
The ₹368 Crore Cash Drain: Profit on Paper, Bleeding in Reality
Here is the number that deserves most attention, and it has nothing to do with one bad quarter. Across FY23 to FY26, Zaggle reported consolidated net profit of Rs 294 cr. Over the same four years, cash from operations was negative Rs 130 cr. Free cash flow was negative in every single one of those years: Rs 32 cr, Rs 129 cr, Rs 48 cr and Rs 159 cr, for a cumulative outflow of Rs 368 cr.
Put plainly, the company has not converted its operating profit into cash at any point in its listed life. Debtor days sit at 69 and working capital days at 100, so the business ties up cash as it grows. The gap has been funded by the IPO, an institutional placement and, lately, modest borrowing, which rose from Rs 20 cr to Rs 55 cr in FY26.
None of this is improper. Fast-growing businesses that sit between banks, merchants and corporate clients genuinely absorb working capital. But an investor buying at Rs 164 is buying a claim on future cash, and so far the profit and the cash have pointed in opposite directions for four straight years. On the earnings call, management was asked when growth and positive cash flow might arrive together. The answer was that it is the company’s daily focus, which is honest but not a date.
The Great Institutional Exodus: Who is Holding the Bag?
The ownership register is the most under-read part of this story.
At the end of September 2023, its first quarter as a listed company, foreign institutions owned 15.60% of Zaggle. By June 2026 that was 2.31%. Domestic institutions peaked at 14.56% in December 2024 and are now at 5.44%. Between them, professional money has cut roughly 22 percentage points of ownership in under three years.
Someone bought all of it. Public shareholding has climbed from 31.80% to 47.96%, and the number of individual shareholders has gone from 21,416 to 1,18,274. Promoter holding has barely moved, at 44.30%.
The register today is a stable promoter block, a very large and very new retail base, almost no institutional presence, and two well-known individual investors. That combination explains the violence of the price moves. A stock with a thin professional base and a wide retail one falls 20% on a missed margin and rises 12% on a single bulk deal, because few large holders have the mandate to lean against either move.
What Kedia Paid For, in Multiples
The share price of Zaggle Prepaid was about Rs 164 when listed in September 2023 and as of closing on 20th August 2026 it was Rs 198.
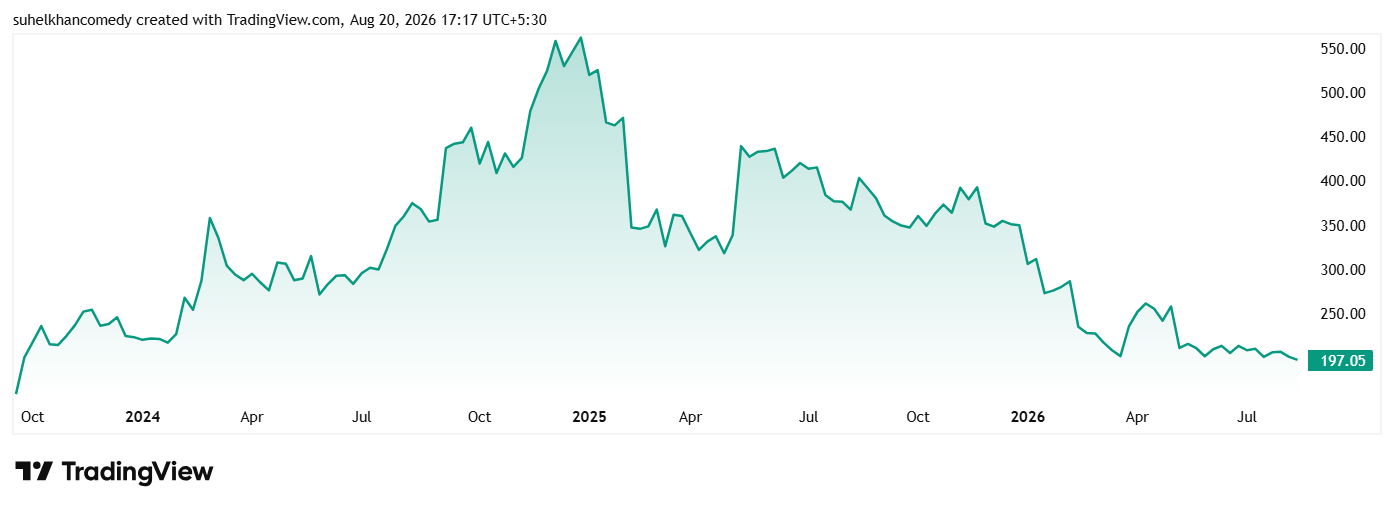
At the current price the stock is trading at a discount of 67% from its all-time high of Rs 597 and 52% from its 52-week high of Rs 414.
With a current market cap of Rs 2,657 cr, the share of the company trades at a PE of 21x and the current industry median is 24x. The current book value is Rs 104 per share and the Return on equity is 10%, while the return on capital employed is close to 14%. It pays no dividend and carries almost no debt.
What can be said here is how the multiple travelled inside the short listed life. The stock has been marked down at speed, from the premium a high-growth software business commands to something close to an ordinary services multiple. The share price is down about 52% from its Rs 414 52-week high, while earnings over the same stretch went up. That is multiple compression, not an earnings collapse, and it is the clearest argument for why a value-minded buyer would show up at Rs 164.
Two housekeeping items belong in the same frame. On 14th August 2026, the company disclosed that its appeal against an income tax demand for assessment year 2022-23 had been dismissed, and said it will challenge that order further.
The same day, the monitoring agency report on the IPO proceeds noted Rs 11.05 cr of spending on general corporate purposes above the permitted amount, while the institutional placement showed no deviation. Neither is large against a Rs 2,501 cr company. Both are the kind of detail ignored on the way up and quoted on the way down.
The Ultimate Valuation Paradox: What are Vijay Kedia and Ashish Kacholia Betting On?
Strip away the headlines and three things are visible.
The first is that Kedia bought a fallen price, not a rising business. He bought on the day of the record low, at a rupee above the IPO price. That is the behaviour of someone who thinks a company compounding revenue near 50% a year for five years has been marked down too far by one quarter of integration costs.
The second is that Kacholia’s silence reads both ways. Eight quarters without a trade is not conviction buying and it is not an exit. It is a position left alone, its percentage drifting from 2.37% to 2.16% only because the share count grew around him.
The third is the one to watch. The September quarter is when Dice revenue is supposed to arrive, integration costs are supposed to normalise, and management says margins should turn. It is also the quarter that shows whether cash finally follows profit. Zaggle has signed a five-year fleet programme with HPCL and put Rs 8 cr into a 20% stake in a cross-border payments firm, so the ambition is not in doubt.
What is in doubt is conversion. A company that reported Rs 294 cr of profit and burned Rs 368 cr of free cash in four years has one number left to prove. Kedia has bought the option on it at Rs 164.72. Everyone else on that register is along for the ride.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.