



Trent Limited’s stock price has seen subdued sentiment over the last few quarters. The stock is down 45% from its peak of Rs 5,500 at the end of 2024. However, this correction has also made the stock valuation multiple a lot more reasonable. The YoY revenue growth has slowed down in the recent quarters, but the company has also delivered a strong margin expansion.
Zudio vs. Pantaloons: The Shifting Retail Landscape
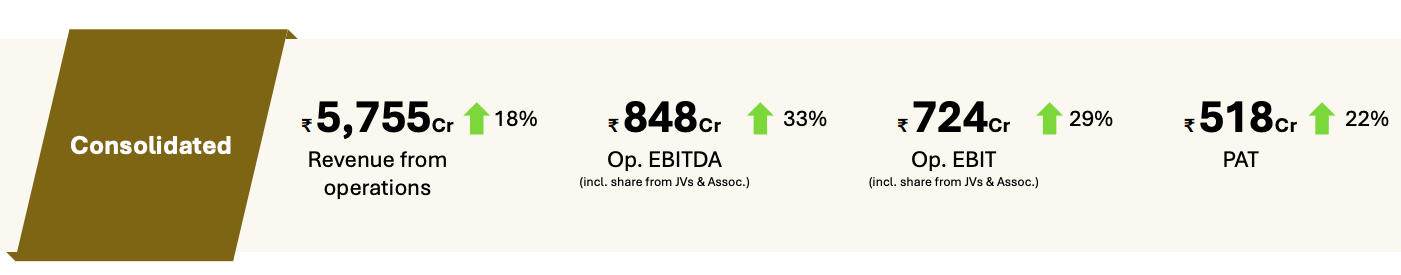
In the recent quarter, the consolidated revenue was Rs 5,755 cr, which was a 17.84% YoY growth. At the same time, the operating EBITDA (earnings before interest, tax, depreciation and amortisation) rose 33% YoY to Rs 848 cr and operating EBIT (earnings before interest and tax) rose 29% YoY to Rs 732 cr. A higher revenue base will be a headwind for future YoY growth numbers. However, the company continues to increase its store count at a rapid pace. One of the key competitors of Trent is Aditya Birla Fashion and Retail Limited, or ABFRL, which has reported a decline in its key Pantaloons segment to 399 stores in the recent quarter from 405 stores in Q1 FY26.
Join now
In the recent quarter, Trent’s Zudio segment had a store count of 982, which was a YoY increase of 216 stores. Back in Q1 FY23, the total store count was 243. Hence, Trent’s Zudio is currently adding net new stores in a single year equal to the total store count four years ago.
#1 Tier-2 Expansion Secures Trent’s Deep Moat
Trent’s Zudio has reached a store count of 982 as of the recent quarterly earnings report. This is a massive presence which is not easy to replicate. Zudio has built a strong network in Tier-2, Tier-3 cities that has allowed it to gain a higher wallet share in these underpenetrated markets.
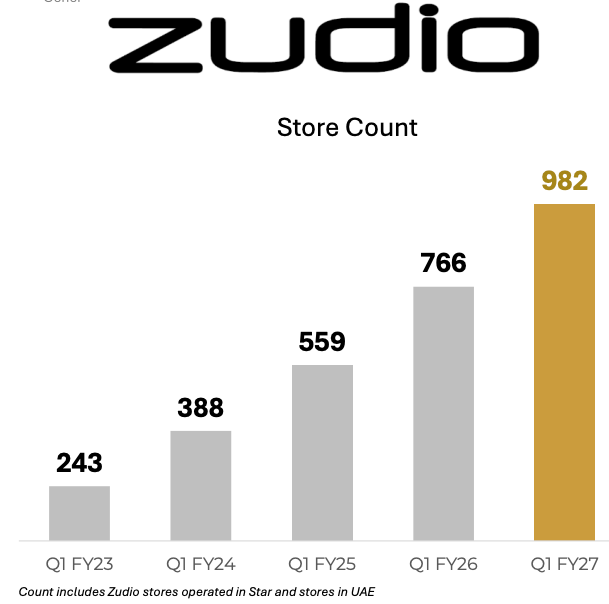
As mentioned above, Zudio’s YoY store count additions continue to be quite strong. At the current pace, Zudio should reach a store count of at least 2,000 by 2030. We can compare it to Spain’s Zara, which is the leader in the fast fashion segment across the globe. Trent has a partnership with Zara in India and operates 20 stores. Zara has close to 1,500 stores globally with an average store size of 20,000 sq ft. On the other hand, Trent’s Zudio is already close to 1,000 stores and has an average store size of 8,000-10,000 sq ft.
It is likely that Zudio’s store count would reach close to Zara or even beat it by 2030. It will be difficult for any future competitor to scale the store count at this pace and reach the network depth shown by Zudio.
#2 Pricing Leverage: Why 33% EBITDA Growth Matters
A key metric to watch in Trent would be its margin expansion potential. The 33% YoY EBITDA growth in the recent quarter has far outpaced the 18% YoY revenue growth. This shows that the company has pricing leverage with its customers and is not competing merely on low prices. As the brand presence of Zudio increases, we could see further improvement in pricing levels, which should improve the margin in the next few quarters.
In the recent quarter, the profit after tax or PAT was 532 cr with a PAT margin of 9.24%. In Q1 FY23, the PAT was only 103 cr with a PAT margin of 6.2%. Over the past four years, the PAT metric has shown 5x growth.
There is a long runway for margin expansion. Trent’s EBIT was Rs 732 cr in the recent quarter with EBIT margin of 12.72%. On the other hand, Zara’s operating margin was close to 20%. A higher store density and better supply chain by Zudio in the next few quarters should be a good tailwind for margin expansion.
#3 Navigating the Forward PE Multiple
At its peak in late 2024, Trent’s stock price was trading at a PE multiple of close to 150. The recent PE multiple is 87.50. The forward PE multiple is below 70 when we look at a potential PAT growth of 25% to 30% for FY27, similar to Q1 FY27. This multiple is a lot more reasonable, relatively speaking, leaving good room for potential growth in the next few quarters.
Trent’s store count growth, revenue growth, and margin expansion potential are still strong. Despite a more competitive environment in the future, Trent has built a good moat, which should allow the company to deliver strong PAT growth in the next few quarters. This makes the stock interesting for investors looking to invest in the retail space where there is a long runway for growth.
Digging deeper into Trent’s performance and its chief rival, Aditya Birla Fashion and Retail Limited.
#1 Trent’s Margin Trajectory: A 304 bps Expansion Over Four Years
Trent reported consolidated YoY revenue growth of 18% in the recent quarter. The operating EBITDA grew 33% YoY, operating EBIT grew 29% YoY, and PAT grew 22% YoY. The PAT margin was 9.24%, up from 8.8% in the year-ago quarter. The long-term trend for PAT margin expansion is also strong. In Q1 FY23, the PAT margin was only 6.2%. Over the past four years, there has been a 304 bps increase in PAT margin.
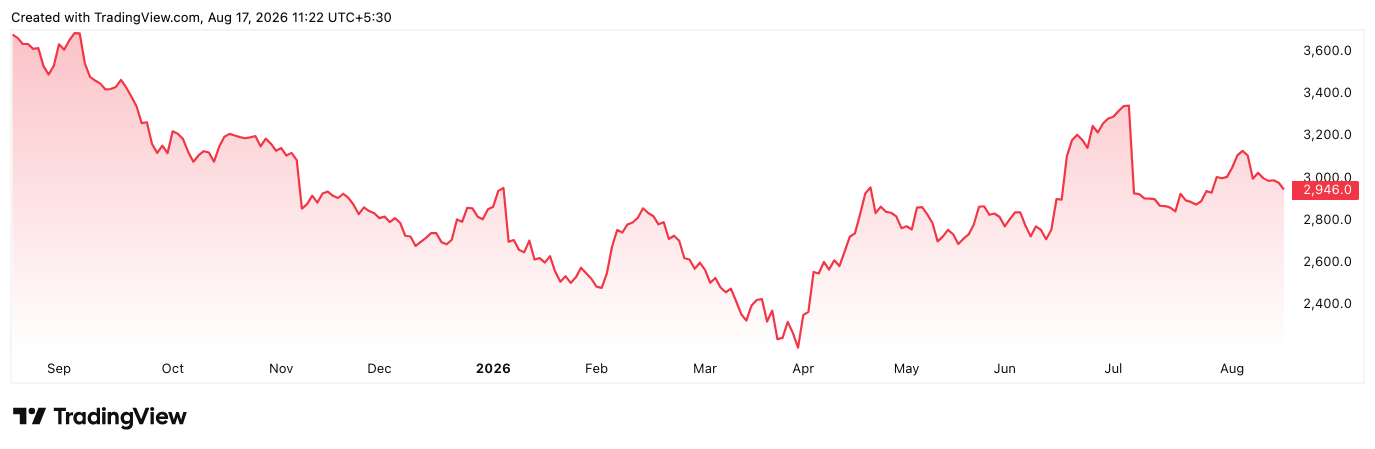
The stock price has declined by 18% in the last 1 year. Trent’s stock hit a peak of Rs 5,500 in late 2024, and since then it has declined by 45%. While the PAT has risen in the past few years, a dip in stock price has made the stock a lot more reasonably priced.
The store count growth is still strong, and as mentioned above, we could see Trent’s store count hit close to 2,000 by 2030, which could even beat the global leader Zara. There is a good moat for Trent due to its store density, brand recognition, and long runway for growth.
Trent 1-year price chart
#2 ABFRL’s Contraction: The Pantaloons Decline and -12.2% Margin Challenge
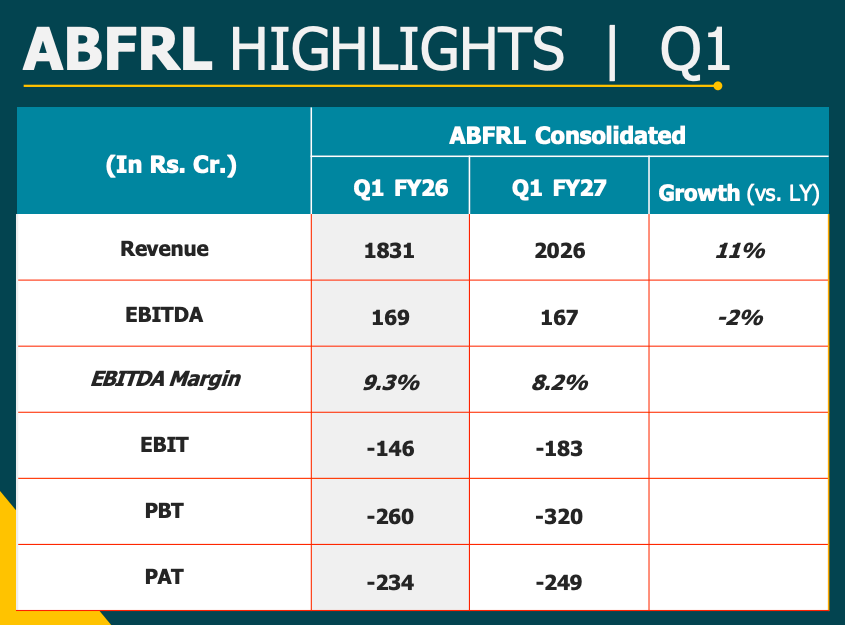
ABFRL’s consolidated revenue grew by 10.65% from Rs 1,831 cr in Q1 FY26 to Rs 2,026 cr in the recent quarter. Its EBITDA declined by 2% to Rs 167 cr while its EBITDA margin declined from 9.3% in the year-ago quarter to 8.2% in the recent quarter. The PAT also declined from Rs -234 cr in Q1 FY26 to Rs -249 cr in Q1 FY27.
We can clearly see a big difference in margin trajectory of Trent and ABFRL. While Trent’s PAT margin has increased to 9.24% from 8.8% in the year-ago quarter, ABFRL’s PAT margin is a negative 12.2%. ABFRL has also reported a decline in store count of key Pantaloons segment to 399 in the recent quarter from 405 stores in the year-ago quarter.
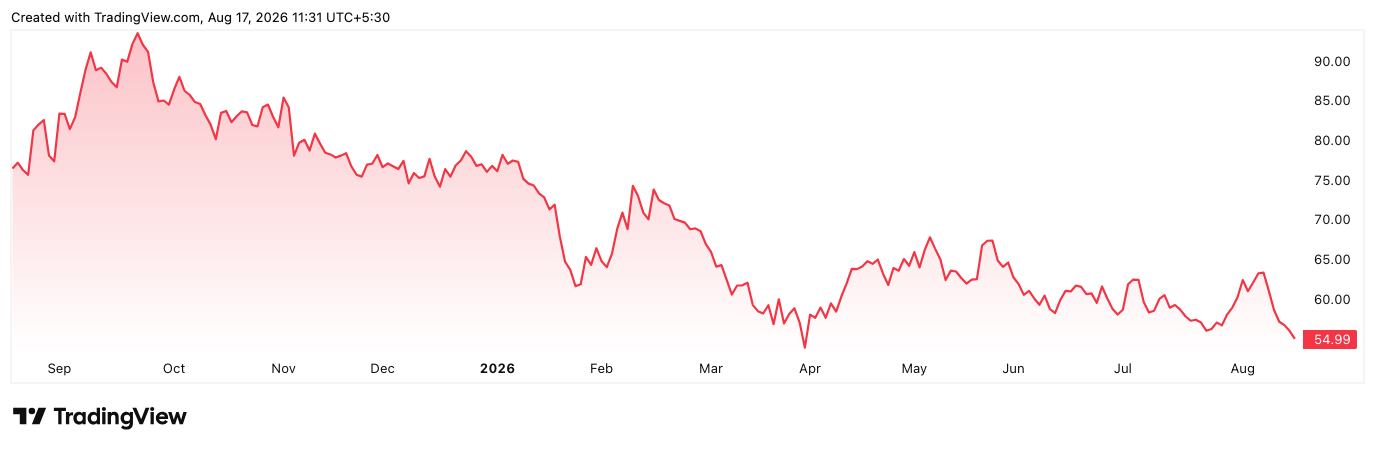
ABFRL’s stock price has declined by 26% in the last 1 year and is now trading at close to Rs 55.
ABFRL’s 1-year price chart
Trent and ABFRL comparison
| Particulars | Trent Limited | ABFRL |
| Q1 FY27 revenue | Rs 5,755 cr | Rs 2,026 cr |
| YoY growth | 17.8% | 10.6% |
| PAT | Rs 532 cr | (Rs 249 cr loss) |
| PAT margin | 9.24% | -12.2% |
| Store footprint | 1,200+ (982 Zudio, 301 Westside) | 399 Pantaloons stores |
| Geographic reach | Aggressive expansion in Tier-2, Tier-3 cities | Pan-Indian retail network |
Peer Comparison: Why Trent Commands a 39x EV/EBITDA Premium
Trent’s EV to EBITDA ratio is 39.58 compared to 12.89 for ABFRL and the industry median of 12.74. Trent’s EBITDA is growing at a faster pace with a 33% YoY growth in operating EBITDA in the recent quarter. Trent’s Return on Capital Employed (ROCE) is 28.34%, which is higher than ABFRL’s -3.76% and above the industry median of 14.11%. Trent’s Return on Equity (ROE) is 27.74%, which is higher than ABFRL’s -13.63% and the industry median of 14.07%.
| Peer comparison | |||
| Company | EV/EBITDA | Return ratios (%) | |
| ROCE (%) | ROE (%) | ||
| Trent | 39.58 | 28.34 | 27.74 |
| ABFRL | 12.89 | -3.76 | -13.63 |
| Industry Median | 12.74 | 14.11 | 14.07 |
To conclude, Trent stock might appear a bit expensive compared to peers, but it offers a better growth runway, better moat and a rapidly expanding margin.
Whether the stocks deliver from here on, only time will tell. It may be a good idea to add Trent Limited and ABFRL to the watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Rohit is a seasoned financial writer with over a decade of experience covering Indian and international stocks. He specializes in converting complex financial data into actionable insights that can help readers make better calls. He covers macroeconomic trends globally, which gives a better analysis of the growth runway for companies in key sectors.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.