



For years, SML Isuzu was a niche player in India’s commercial vehicle market, best known for its buses and light trucks. That changed after Mahindra & Mahindra acquired a controlling stake of nearly 59% in the company from Sumitomo Corporation and Isuzu Motors in 2025.
The company was subsequently renamed SML Mahindra. Now, Mahindra is taking the next big step in scaling the business.
On July 29, 2026, SML Mahindra’s board approved the ₹525-crore acquisition of Mahindra & Mahindra’s Truck and Bus Division (MTBD) through a slump sale. If completed, the deal could almost double SML Mahindra’s volumes and strengthen its commercial vehicle lineup.
The plan is straightforward: take a niche CV maker and turn it into a serious rival to Tata Motors and Ashok Leyland.
Join now
From a Niche Player to a Full-range CV Maker
The acquisition of Mahindra’s commercial vehicle business changes the business proposition of SML Mahindra overnight. Mahindra sold 14,832 trucks and buses in FY26. SML Mahindra, meanwhile, sold 16,632 vehicles during the period. Put together, the two businesses would have sold 31,464 vehicles in FY26.
Volume is only one part of the story. The bigger change is in the product mix. Traditionally, SML Mahindra focused on light and intermediate commercial vehicles, particularly buses, whereas Mahindra MTBD has a presence in the heavy commercial vehicle (CV) segment.
This gives the combined company exposure across light, intermediate, and heavy commercial vehicles, along with buses. That matters because product breadth is one of the biggest advantages enjoyed by the larger CV players.
The acquisition process is expected to close by January 31, 2027, subject to shareholder and regulatory approvals.
SML Mahindra has Bigger Ambitions
For Mahindra & Mahindra, the acquisition of SML Isuzu was not a standalone bet. It was part of a broader plan to build a stronger commercial vehicle business and take on the industry’s two giants, Tata Motors and Ashok Leyland.
In FY26, Mahindra’s Truck and Bus Division generated ₹2,989 crore in revenue, while SML Mahindra generated ₹2,838 crore. Combined, the two businesses had revenue of ₹5,827 crore.
Now, SML Mahindra is targeting more than double that figure, ₹12,500 crore in revenue by FY31. It also wants to increase its domestic CV market share from around 6% currently to 10-12% by FY31, with a longer-term target of crossing 20% by FY36.
The numbers show the scale of Mahindra’s ambition. For investors, the question is whether SML Mahindra can execute on it.
The Gap with Tata Motors and Ashok Leyland is Still Huge
India’s commercial vehicle market is dominated by Tata Motors and Ashok Leyland by a huge margin. In Q1FY27, Tata Motors’ commercial vehicle business generated ₹19,300 crore in revenue and sold 108,700 vehicles. It had a 36.8% share of the domestic CV market. Its dominance is even stronger in heavy commercial vehicles, where it had a 56.3% market share. The business reported an EBITDA margin of 10.9%.
Ashok Leyland also had a strong quarter. It sold 48,763 commercial vehicles in Q1FY27. It reported revenue of ₹9,634 crore, with an EBITDA margin of 10.1%.
SML Mahindra, in comparison, sold just over 7,000 vehicles during April-July of FY27. The MTBD acquisition will significantly increase that scale. But even after combining the two businesses, SML Mahindra will remain much smaller than either Tata Motors or Ashok Leyland.
CV Market: The Scale Gap
| Company | Q1FY27 Revenue (₹ crore) | EBITDA Margin (%) | Q1FY27 Sales Volume |
| Tata Motors CV | 19,300 | 10.9 | 1,08,700 |
| Ashok Leyland | 9,634 | 10.1 | 48,763 |
| SML Mahindra | 958 | – | 7,041 |
So the acquisition may create a third player. It does not, by itself, create a third equal.
Why the Opportunity is Worth Watching, If Execution Holds
None of this makes SML Mahindra’s growth story automatic. But there are specific reasons the combination could work, provided the company executes well on integration:
A Genuinely Complementary Portfolio
SML’s strength has historically been in light and intermediate commercial vehicles and buses, while MTBD’s Blazo and Furio ranges extend into heavy trucks. There are very few Indian CV makers that have this full spectrum of commercial vehicles along with buses. If SML manages to knit these product lines into one coherent go-to-market strategy, it gains a completeness of range that smaller rivals lack.
M&M Backing
With M&M holding roughly a 59% stake, SML Mahindra now sits inside a large, well-capitalised group. That matters for a capital-intensive business like commercial vehicles, where product development, emission-norm transitions and dealer network expansion all require sustained investment. SML Mahindra is therefore no longer trying to scale on its own.
A Favourable Demand Backdrop
SML Mahindra is also entering the market at a time when several factors are supporting commercial vehicle demand. The biggest catalyst has been the GST rate cut on commercial vehicles from 28% to 18% in September 2025. The lower tax rate reduced the cost of buying and operating a vehicle.
Another structural driver has been continued government spending on roads, highways, and metro projects, which is supporting demand for medium and heavy commercial vehicles. A pickup in mining and cement activity could provide another boost to freight and heavy-vehicle demand.
Growing Average Age of CV Fleet in India
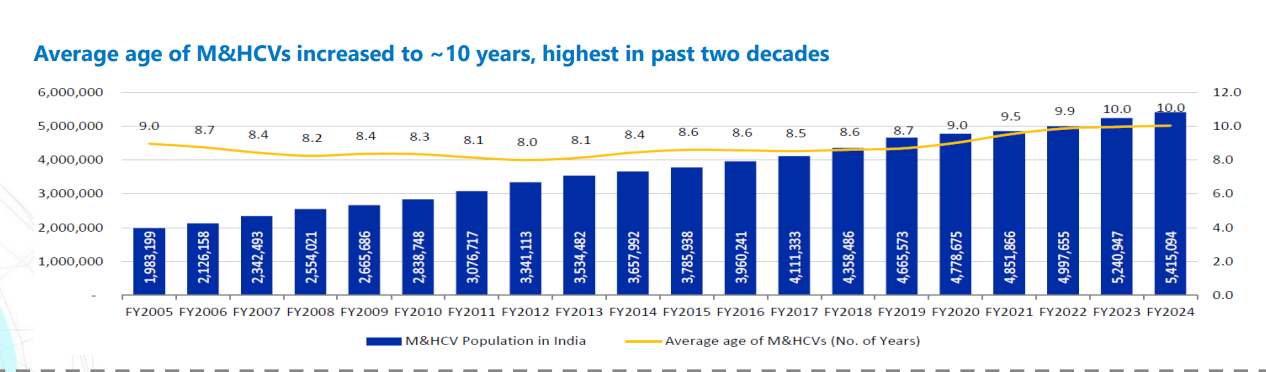
There is also a large replacement opportunity. India’s medium and heavy commercial vehicle fleet is ageing. According to an Ashok Leyland presentation, the average age of India’s M&HCV fleet has increased to nearly 10 years, the highest in the past two decades. The voluntary vehicle scrappage policy, which targets older and more polluting commercial vehicles, could accelerate replacements. Government fleet-modernisation programmes, particularly by state transport undertakings, could also support demand for new buses.
Market Rewards Scale
India’s CV market is dominated by a handful of large players, where scale, product range and distribution strength matter. A larger SML Mahindra could be in a better position to compete for fleet orders and government tenders than it was as a standalone niche player.
The Market is Already Pricing in a Turnaround
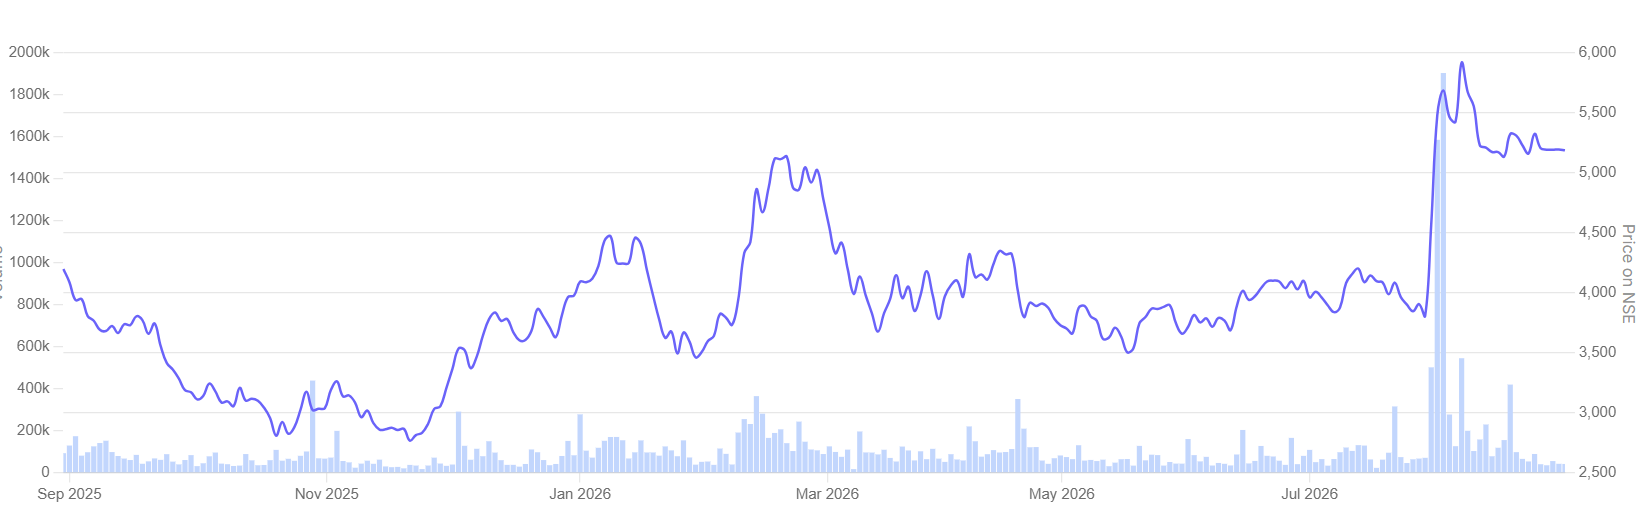
SML Mahindra’s growth story may still be at an early stage, but the stock market has re-rated the stock. On the announcement of the MTBD acquisition, SML Mahindra’s share price rose more than 40% in just two days.
SML Mahindra: 1 Year Stock Price Chart
Valuation Trend
| Metrics | Trailing P/E | 5-yr Median PE | Industry PE |
| SML Mahindra | 48.0 | 32.6 | 27.8 |
| Tata Motors CV | 23.1 | 38.0 | |
| Ashok Leyland | 27.7 | 27.1 |
Post the rally, SML currently trades at a trailing price-to-earnings of around 48 times, well above its five-year median of 32.6 times and the industry P/E of 27.8 times. It also trades at a significant premium to Tata Motors CV at 23.1 times and Ashok Leyland at 27.7 times.
The re-rating suggests that investors are already anticipating a meaningful improvement in SML Mahindra’s earnings as the company integrates MTBD and scales up its commercial vehicle business.
This creates an important distinction for investors. The question is no longer whether SML Mahindra can grow; the market appears to be pricing in that growth already. The bigger question is whether the company can deliver enough earnings growth to justify the premium valuation.
If the combined business delivers on its revenue and market-share targets, the current valuation could eventually look more reasonable as earnings catch up. But if the turnaround takes longer than expected, the stock’s premium multiple leaves less room for disappointment.
Can SML Mahindra Deliver?
SML Mahindra has the ingredients to become a credible third or fourth force in India’s commercial vehicle market. It possesses a wider product portfolio, M&M’s backing, and a favourable demand environment.
But the real test is execution. The company needs to integrate MTBD smoothly, unlock synergies, improve margins and take market share from Tata Motors and Ashok Leyland. With the stock already trading at a premium valuation, the market is clearly expecting a turnaround.
If SML Mahindra delivers on its FY31 targets, the current premium could be justified. If execution falls short, both the growth story and the valuation could come under pressure. Add the stock to your watchlist and monitor how they execute their growth plans.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.