



Free cash flow is the cash a company has left after meeting its operating needs and capital expenditure. It shows how much real cash the business is generating after reinvesting in itself. This matters because free cash flow can be used to reduce debt, pay dividends, fund expansion, or strengthen the balance sheet.
Price-to-free-cash-flow, or PFCF, compares a company’s market value with the free cash flow it generates. It shows how much investors are paying for each rupee of cash left after operating needs and capital expenditure. This is useful because a company may report profit, but still have little cash left after reinvestment. PFCF helps check whether the stock is reasonably priced against the cash the business actually retains.
In this article, we look at companies with strong free cash flow. But the focus is not only on the latest year’s number. A high free cash flow figure can sometimes come from one-off events. These may include asset sales, unusually low capex, tax refunds, working-capital reversals, or a temporary commodity cycle benefit.
To screen for companies, we used a cash-flow and valuation-based query. The filters included market capitalisation above Rs 1,000 crore, free cash flow of more than Rs 500 crore in the latest year, positive free cash flow over three years, and positive cash from operations in both the latest year and over three years.
The screen also required a positive price-to-free-cash-flow ratio below 15. Debt-to-equity had to be below 1. Five-year sales growth had to be above 5%. This helped narrow the list to companies with cash generation, reasonable valuation, manageable leverage, and some growth record.
We further cleaned the list for sector specific issues. A note on the same is shared later in the article.
Now, let’s focus on the stocks that made the cut.
#1 Oil and Natural Gas Corporation: Can a ₹33,075-Cr Offshore Bet Reverse Flat Output?
Oil and Natural Gas Corporation (ONGC) is the largest crude oil and natural gas company in India, contributing around 71% to Indian domestic production.
ONGC Financial Performance
| Metric | FY26 |
| Revenue growth | -0.2% YoY |
| Net profit growth | 29.9% YoY |
| Free cash flow | Rs 59,510 crore |
| 3-year free cash flow | Rs 1,70,629 crore |
| Price-to-free-cash flow | 5.37x |
| EV/EBITDA | 3.8x |
ONGC’s FY26 numbers showed a business where cash generation remains the main comfort, even as core production growth stayed modest. Consolidated gross revenue was almost flat at Rs 6,62,247 crore, down from Rs 6,63,262 crore a year earlier. Consolidated net profit rose 29.9% to Rs 49,793 crore from Rs 38,329 crore, supported by stronger performance from subsidiaries such as HPCL, MRPL, ONGC Videsh and OPaL.
ONGC generated free cash flow of Rs 59,510 crore in the latest year. Its three-year free cash flow stood at Rs 1,70,629 crore. The stock’s price-to-free-cash-flow ratio was 5.37 times, making cash valuation the central point of the ONGC case.
The cash-flow story is important here. ONGC remains a large upstream producer with steady operating cash potential. Its FY26 dividend payout also reflects this. The company announced total dividend of Rs 13.25 per share for FY26, with a total payout of Rs 16,669 crore. This is a direct sign of cash earned being returned to shareholders, rather than only being reported as accounting profit. It also explains why ONGC often appears in discussions around dividend-paying stocks.
Production Dynamics: Stabilizing Volumetric Output Amid Flattish Upstream Growth
The company’s production picture was stable but not strong. Standalone crude oil production stood at 18.355 million metric tonne (MMT) in FY26, compared with 18.558 MMT in FY25. Natural gas production was 19.533 BCM, against 19.654 BCM a year earlier. Management said production has remained broadly flat in recent years. It is now focusing on structural steps to revive output.
A key part of that plan is gas. ONGC said new well gas formed 17% of production and 21% of revenue from its nomination gas portfolio in FY26. Revenue from new well gas stood at Rs 6,678 crore. This added Rs 1,223 crore over what the company would have earned at the APM gas price. This matters because higher-priced gas can support future cash flows if volumes scale up.
Project Pipeline: Western Offshore and Gas-Led Growth
Project execution is now the main monitorable. ONGC has projects worth Rs 33,075 crore under progress in Western Offshore. The Daman Upside Development Project has started gas monetisation. It is expected to add meaningfully to gas production over time. The company has also expanded BP’s technical service provider role across the Western Offshore after early results in Mumbai High.
There are global and non-core growth levers too. ONGC Videsh has seen Sakhalin production normalise, while Mozambique LNG work has restarted. The group is also building renewable, petrochemical, shipping and port-linked ventures. These are still secondary to the core upstream story, but they may add future cash streams.
Valuation is best read through price-to-free-cash-flow here. ONGC’s PFCF of 5.37 times shows that the stock is priced modestly against the free cash flow it generated. Its EV/EBITDA also stands at 3.8 times, compared with the industry median of 16.4 times. Its return on capital employed (RoCE) stands at 14.2% and return on equity (RoE) at 11.7%. The low multiple suggests the market is still pricing in production risks and commodity cyclicality. For now, the stock’s appeal rests on whether ONGC can sustain free cash flow as gas-led projects and offshore investments start contributing.
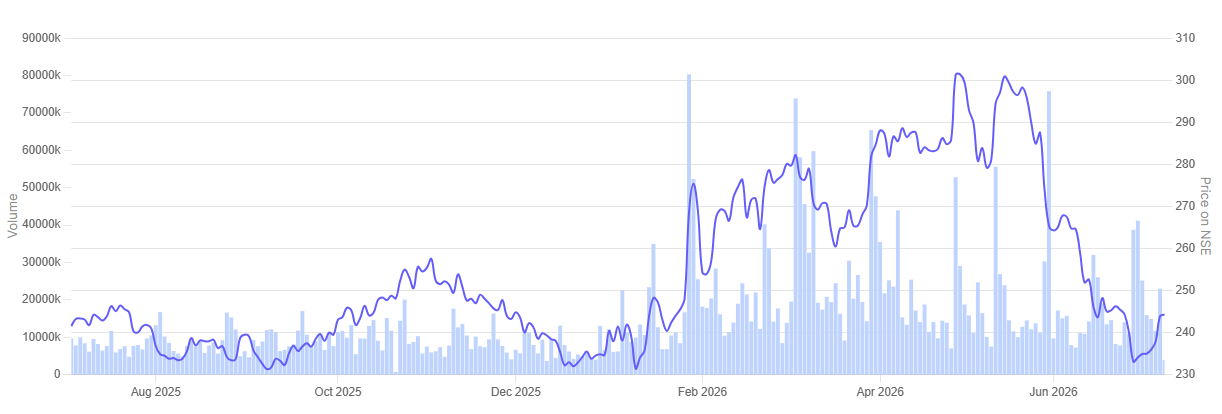
In the past year, the share price of ONGC is up 0.8%.
ONGC 1 Year Share Price Chart
#2 Wipro: Can Strong Cash Flow Revive Growth After a Soft FY26?
Wipro is a global information technology, consulting and business process services (BPS) company.
Wipro Financial Performance
| Metric | FY26 |
| Revenue growth | 4% YoY |
| Net profit growth | 0.4% YoY |
| Free cash flow | Rs 13,447 crore |
| 3-year free cash flow | Rs 46,041 crore |
| Price-to-free-cash flow | 11.3x |
| EV/EBITDA | 8.4x |
Wipro ended FY26 with modest rupee revenue growth but steady cash generation. The company’s consolidated revenue for the year stood at Rs 92,624 crore up 4% year-on-year (YoY). Net profit stood at Rs 13,266 crore up marginally by 0.4% YoY.
Cash Conversion: Asset-Light Model Supports Free Cash Flow
The center of the Wipro story is free cash flow. Wipro generated free cash flow of Rs 13,447 crore in the latest year. Its three-year free cash flow stood at Rs 46,041 crore. The stock traded at a price-to-free-cash-flow ratio of 11.3 times.
The cash-flow case is supported by Wipro’s asset-light IT services model. The company does not need heavy capital expenditure in the same way as manufacturing or infrastructure businesses. In FY26, operating cash flow stood at 112.6% of net income. This means reported profit converted well into operating cash. Management also said it did not see any large build-up of unbilled revenue or unusual balance sheet stress.
Wipro also continued returning cash to shareholders. In Q4 the board approved a Rs 15,000 crore buyback at Rs 250 per share. This is expected to cover 5.7% of paid-up capital, subject to shareholder approval. The company also distributed dividends of $ 1.3 billion in FY26. Its payout ratio for the three-year block ending FY26 stood at about 88%, well above the 70% minimum under its capital allocation policy.
Growth Monitorable: Large Deals and AI Push Need Revenue Conversion
Growth remains the main challenge. Wipro’s Q4 order booking stood at $ 3.5 billion, while it won 14 large deals worth $ 1.4 billion during the quarter. The company also highlighted the Olam Group deal, expected to exceed $ 1 billion in contract value, with a committed spend of $800 million. This is one of Wipro’s largest engagements in the APMEA region.
AI is the key growth monitorable. Wipro has launched a dedicated AI-native business and platforms unit. The aim is to move beyond a services-only model towards a services-as-a-software approach. The company is also working on AI model operations, semiconductor engineering services, AI advisory and agentic workflows. These initiatives may support future growth, but conversion into revenue will take time.
Valuation should be read through free cash flow here. Wipro’s price-to-free-cash-flow ratio stood at 11.3 times. Its RoCE stood at 17.8%, while RoE was 15.5%. For now, Wipro’s case rests on cash conversion, buyback support and large deal ramp-ups. The risk is that revenue recovery may remain slow if client spending stays cautious or in case AI destroys demand for traditional IT services.
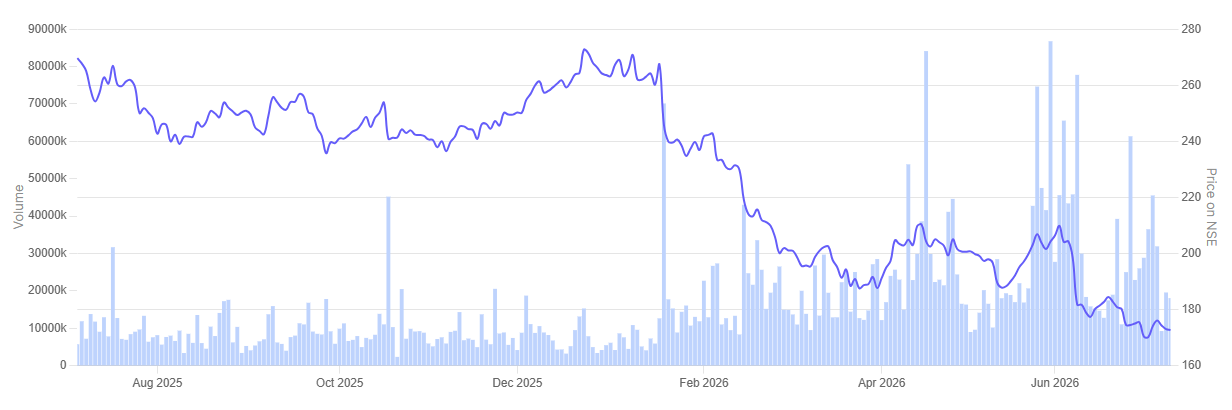
In the past year, the share price of Wipro tumbled 35.8%.
Wipro 1 Year Share Price Chart
#3 Indus Towers: Will a 2,64,500 Tower Base Offset Customer Risks?
Indus Towers is engaged in the business of, inter-alia, setting up, operating and maintaining wireless communication towers.
Indus Towers Financial Performance
| Metric | FY26 |
| Revenue growth | 7.9% YoY |
| Net profit growth | -28.1% YoY, 13% normalized |
| Free cash flow | Rs 7,786 crore |
| 3-year free cash flow | Rs 24,310 crore |
| Price-to-free-cash flow | 12.81x |
| EV/EBITDA | 6.6x |
Indus Towers ended FY26 with steady operating growth and strong cash generation. The company’s reported gross revenue rose 7.9% YoY to Rs 32,500 crore. Profit after tax stood at Rs 7,140 crore, down 28.1% YoY. The decline was mainly because FY25 had a large write-back of Rs 5,100 crore linked to collections from a major customer. On a normalised basis, PAT grew 13%. Indus Towers generated free cash flow of Rs 7,786 crore in the latest year. Its three-year free cash flow stood at Rs 24,310 crore. The stock’s price-to-free-cash-flow ratio was 12.81 times.
The free cash flow number is central because Indus is a tower infrastructure business. Once towers are built and tenancies rise, the business can generate recurring cash from rentals. The board recommended a final dividend of Rs 14 per share. Management said this reflected better visibility on cash flows and its intent to return cash to shareholders, while still keeping capital allocation disciplined.
Operational Scale: Expanding Co-Locations Across a 2,64,500 Macro Base
Operationally, the company benefited from strong telecom network rollout. In Q4, it added 4,892 macro towers and 6,192 co-locations. For the full year, tower additions stood at around 15,200, while co-location additions were about 22,500.
The total macro tower base reached nearly 2,64,500. Co-locations stood at around 4,28,000. Including leaner towers, the portfolio was about 4,42,000 at the end of FY26. This matters for cash flow because higher co-locations improve asset utilisation. A tower with more tenants can generate better returns without the same level of fresh tower capex.
The wider industry backdrop also remained favourable. India’s 5G BTS base stood close to 5,31,000. The 5G subscriber base crossed 391 million by December 2025. TRAI data showed total data consumption grew 29% year-on-year, while average monthly data usage per user rose 21%. This rising data traffic is pushing telecom operators to add capacity on existing infrastructure. That supports loading-led revenue growth for tower companies. For Indus, the key is whether this demand converts into billings, collections and free cash flow.
Margin Optimization: Reducing Diesel Overhead via 42,400 Solar Sites
Cost efficiency was another focus area. Indus added about 2,500 sites with solar access during Q4, taking the total to nearly 42,400 sites. Diesel consumption fell 7% YoY in Q4, despite a 6% rise in co-locations and continued equipment loading. The company also said energy margins improved from negative 5.2% in Q4 FY25 to negative 3.6% in Q4 FY26. Lower diesel use can support margins and protect operating cash flow if energy costs remain volatile.
The company is also preparing for expansion outside India. In Africa, it has secured an operating licence in Zambia. Uganda and Nigeria are in the final stages of regulatory approvals. Initial orders are in place with the primary customer. Rollouts are expected to begin soon and then ramp up gradually. The cash-flow impact will depend on rollout pace, capex and collections.
Valuation should be read through PFCF. Indus Towers trades at a price-to-free-cash-flow ratio of 12.81 times. It trades at an EV/EBITDA of 6.6 times, compared with the industry median of 9.7 times. Its RoCE stands at 19.5%, while RoE is 19.8%.
For now, the cash flow case rests on three things. Telecom operators must keep adding capacity. Customer collections must remain steady. Capex must stay disciplined. If these hold, Indus Towers can continue turning network expansion into free cash flow. The risks are customer concentration, supply-chain delays and any slowdown in telecom capex.
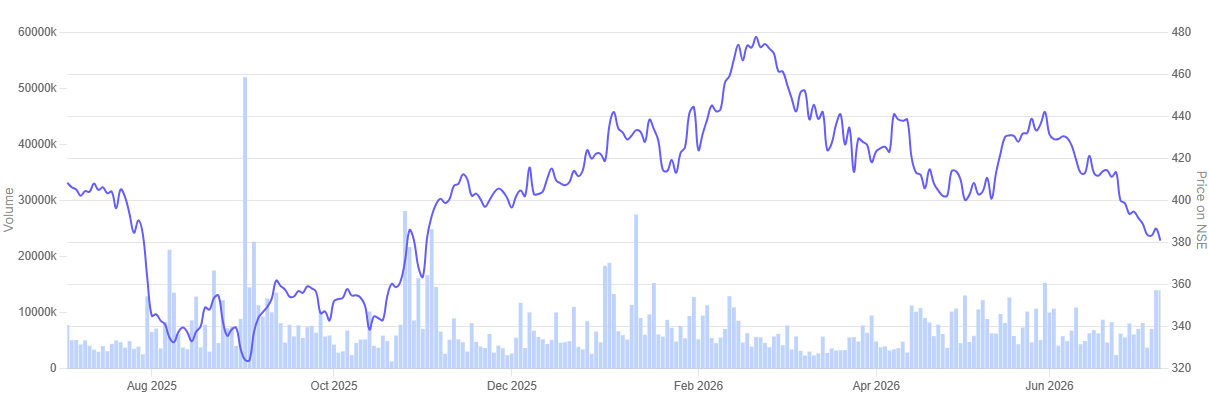
In the past year, the share price of Indus Towers is down 6.3%.
Indus Towers 1 Year Share Price Chart
Conclusion
In the end, this screen is about one simple question. Which companies are actually earning cash, and not just showing profit on paper…and are still available at perhaps reasonable valuations (P/CF)?
ONGC, Wipro and Indus Towers come from very different businesses. ONGC depends on oil, gas and production growth. Wipro depends on global technology spending, and, deal with the risk of AI hurting long term demand for its services. Indus Towers depends on telecom network expansion and timely customer payments.
So, the risks are different for each company. But the common point is cash. All three have shown the ability to generate free cash flow from their main business.
That makes price-to-free-cash-flow a useful metric here. It helps investors see how much they are paying for the free cash flow a company retains after capex. But the number still needs context. A low valuation only matters if the cash flow can continue.
For investors, the real test is not just who generated the most cash last year. It is whether that cash flow looks steady, repeatable and backed by the core business.
India’s Cash Rich Companies: Free Cash Flow vs Returns vs Valuation
| Metric | ONGC | Wipro | Indus Towers |
| FY26 revenue growth | -0.2% | 4.0% | 7.9% |
| FY26 profit growth | 29.9% | 0.4% | -28.1% reported; 13% normalized |
| RoCE | 14.2% | 17.8% | 19.5% |
| RoE | 11.7% | 15.5% | 19.8% |
| Free cash flow | Rs 59,510 crore | Rs 13,447 crore | Rs 7,786 crore |
| 3-year free cash flow | Rs 1,70,629 crore | Rs 46,041 crore | Rs 24,310 crore |
| Price-to-free-cash flow | 5.37x | 11.3x | 12.81x |
| Industry median Price to free cash flow | NA | 16.6x | NA |
| Key theme | Upstream oil and gas cash generation | Asset-light IT services cash conversion | Telecom tower cash flows |
For now, the cash-flow theme looks steady. These companies are not just profitable. They are also generating real cash.
The test now is consistency. ONGC must manage commodity cycles. Wipro must convert large deals into growth. Indus Towers must keep turning network expansion into free cash flow.
You can track how these are progressing by adding stocks to your watchlist.
Note: The Mechanics of the Quality Screen
The initial list was then cleaned further. Banks, NBFCs, and insurance companies were excluded. Their cash flow is not calculated in the same meaningful way as it is for regular businesses. Realty companies were also removed. In real estate, one large project handover can inflate cash flow for a year. That may not show steady business quality. Holding companies were removed too, since their cash flow often comes from dividends or stake value in another listed business, not their own operations.
Oil companies dominated the remaining list. Fuel retailers were excluded because they collect cash immediately at the pump. This can make cash flow look strong because of collection speed. It may not fully reflect business performance. Upstream oil companies were treated differently because their cash flow is linked more directly to oil prices, production, and cost efficiency.
The next step was to avoid one-year spikes. Some companies had free cash flow in the latest year that was much higher than their three-year average. These were skipped. The aim was to avoid companies where cash flow looked strong only because of a favourable cycle.
Very small companies were also filtered out, even when their valuation looked cheap. A low price-to-FCF ratio on a tiny cash flow base does not fit a screen built around companies generating meaningful, large-scale cash. Some large IT services companies also appeared on the list. But including many companies from the same sector would repeat the same story. So the final selection was kept diversified. The focus was on companies where free cash flow looked meaningful, more repeatable, and still reasonably valued on a PFCF basis.
Discalimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.