



India’s semiconductor opportunity is creating a new set of beneficiaries beyond chipmakers and electronics companies. Chemical and materials manufacturers are now positioning themselves to supply critical inputs to this emerging ecosystem.
Two lesser-followed chemical companies are taking different routes into this opportunity. One is building a large silicon carbide manufacturing and packaging facility. The other is expanding its semiconductor chemicals capabilities into photoresist chemicals alongside its existing specialty chemicals business.
Silicon carbide (SiC) is a semiconductor material made from silicon and carbon. Its high thermal conductivity, high breakdown voltage and the ability to operate at high temperatures make SiC key in semiconductors. Photoresist, on the other hand, is used to create small patterns on a semiconductor wafer. Their properties make them key to the semiconductor value chain.
The opportunity is still at an early stage, with meaningful revenue contributions likely to take time. But the scale of investments, government support and rising demand from Artificial Intelligence, electric vehicles, renewable energy and data centres could make these businesses worth watching.
Join now
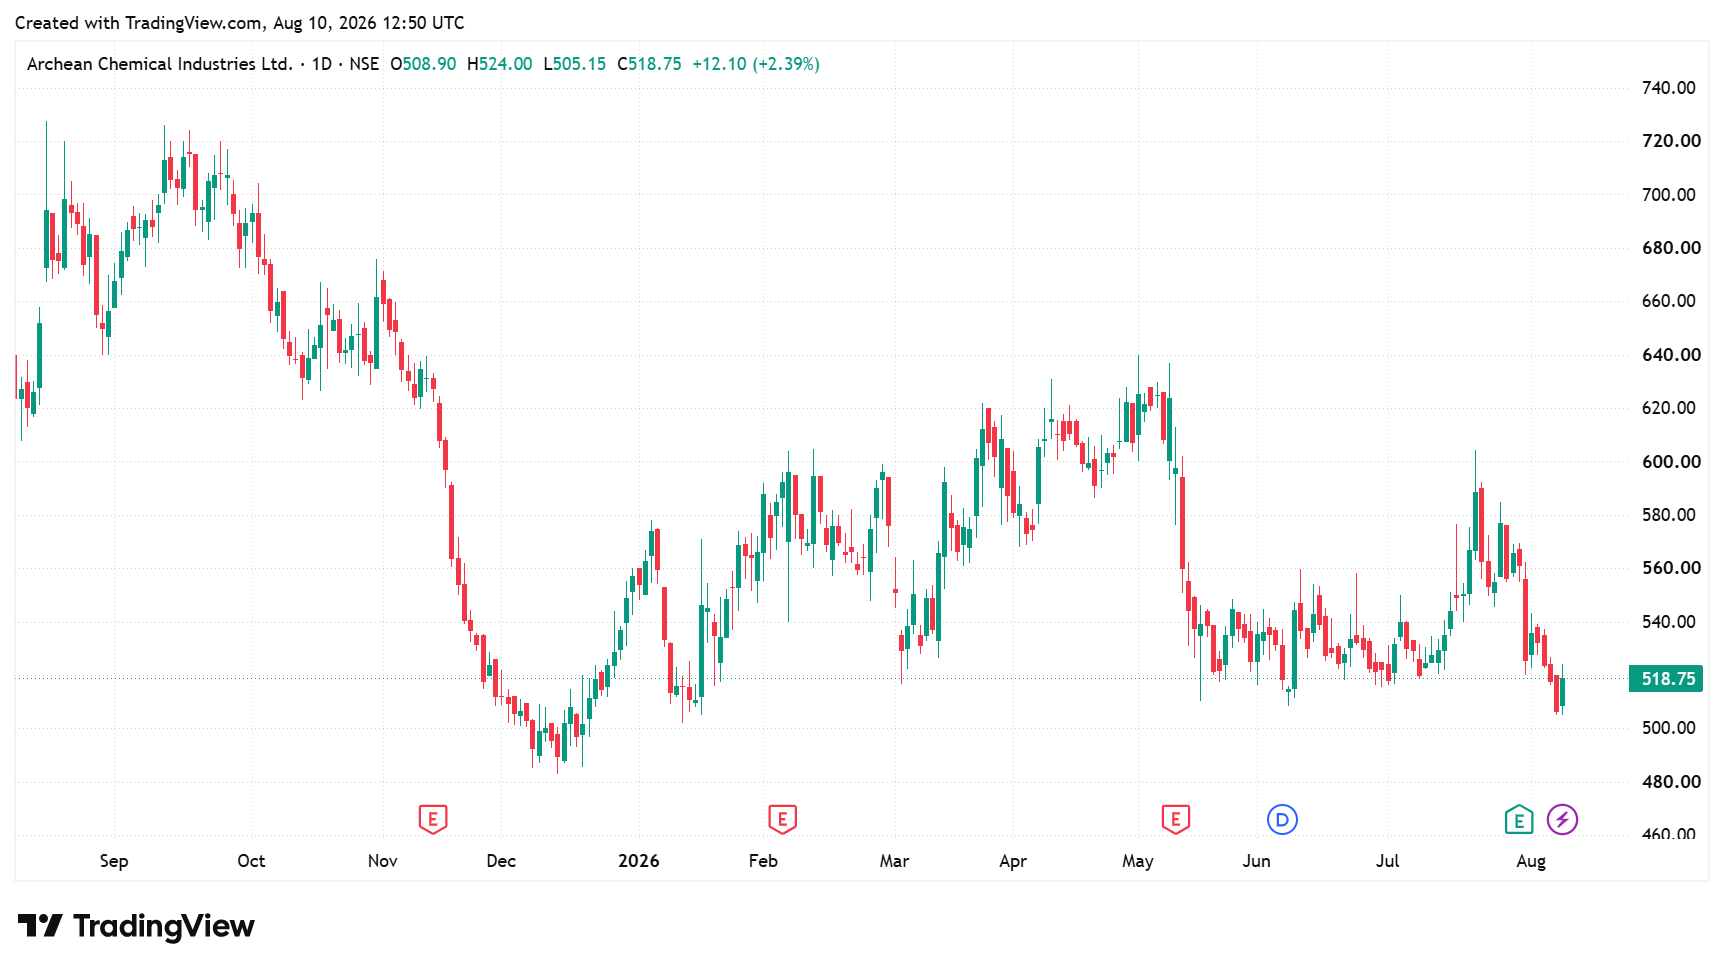
#1 Archean Chemicals
Archean Chemical Industries (ACIL) manufactures speciality marine chemicals. It operates India’s first integrated facility producing Bromine (42% of revenue), Industrial Salt (54%), and Sulphate of Potash (4%) from natural sea brine. The company leads in Indian merchant bromine sales and is India’s largest exporter of both Bromine and Industrial Salt.
The ₹2,067 Crore Silicon Carbide Wager
The company is diversifying into high-growth sunrise sectors through its step-down subsidiary, SiCSem Private Limited. It is setting up India’s first commercial compound semiconductor fabrication and Assembly, Test, Marking, & Packaging plant at Bhubaneswar, Odisha.
It receives technology support from UK-based Clas-SiC Wafer Fab Ltd. The integrated fab and packaging unit can produce 60,000 wafers and 960 lakh packaged units of SiC MOSFETs and power devices annually.
These SiC devices aim to serve key sectors including electric vehicles, renewable energy systems, railways, fast chargers, defence, and data centres. The company executed its formal Fiscal Support Agreement (FSA) with the India Semiconductor Mission (ISM) on 11 May, 2026.
Navigating Execution and Capex Timelines
Construction is scheduled to begin in early September. Production is targeted to begin within 24 to 27 months from the date of the FSA. Under the FSA, the project is eligible for fiscal support from the central and state governments for up to 75% of the eligible capital expenditure. Phase 1 alone is estimated to cost ₹2,067 crore.
Q1FY27 Performance: Logistics Costs Bite Margins
From a financial perspective, total income grew by 10.7% year-on-year to ₹332.8 crore in Q1FY27. Growth was led by a richer product mix and higher bromine sales. EBITDA (Earnings Before Interest, Tax, Depreciation and Amortisation) fell by 15.5% to ₹72.9 crore due to high logistics costs. As a result, net profit declined by 24.2% to ₹30.4 crore.
Archean operates a liquid bromine capacity of 42,000 to 43,000 Metric Tons Per Annum. In Q1 FY27, bromine sales volumes reached 4,175 tons. Management has guided for an annualised exit volume run rate of 20,000 to 25,000 tons by the end of FY27 and 25,000 tons by FY28.
#2 Acutaas Chemicals
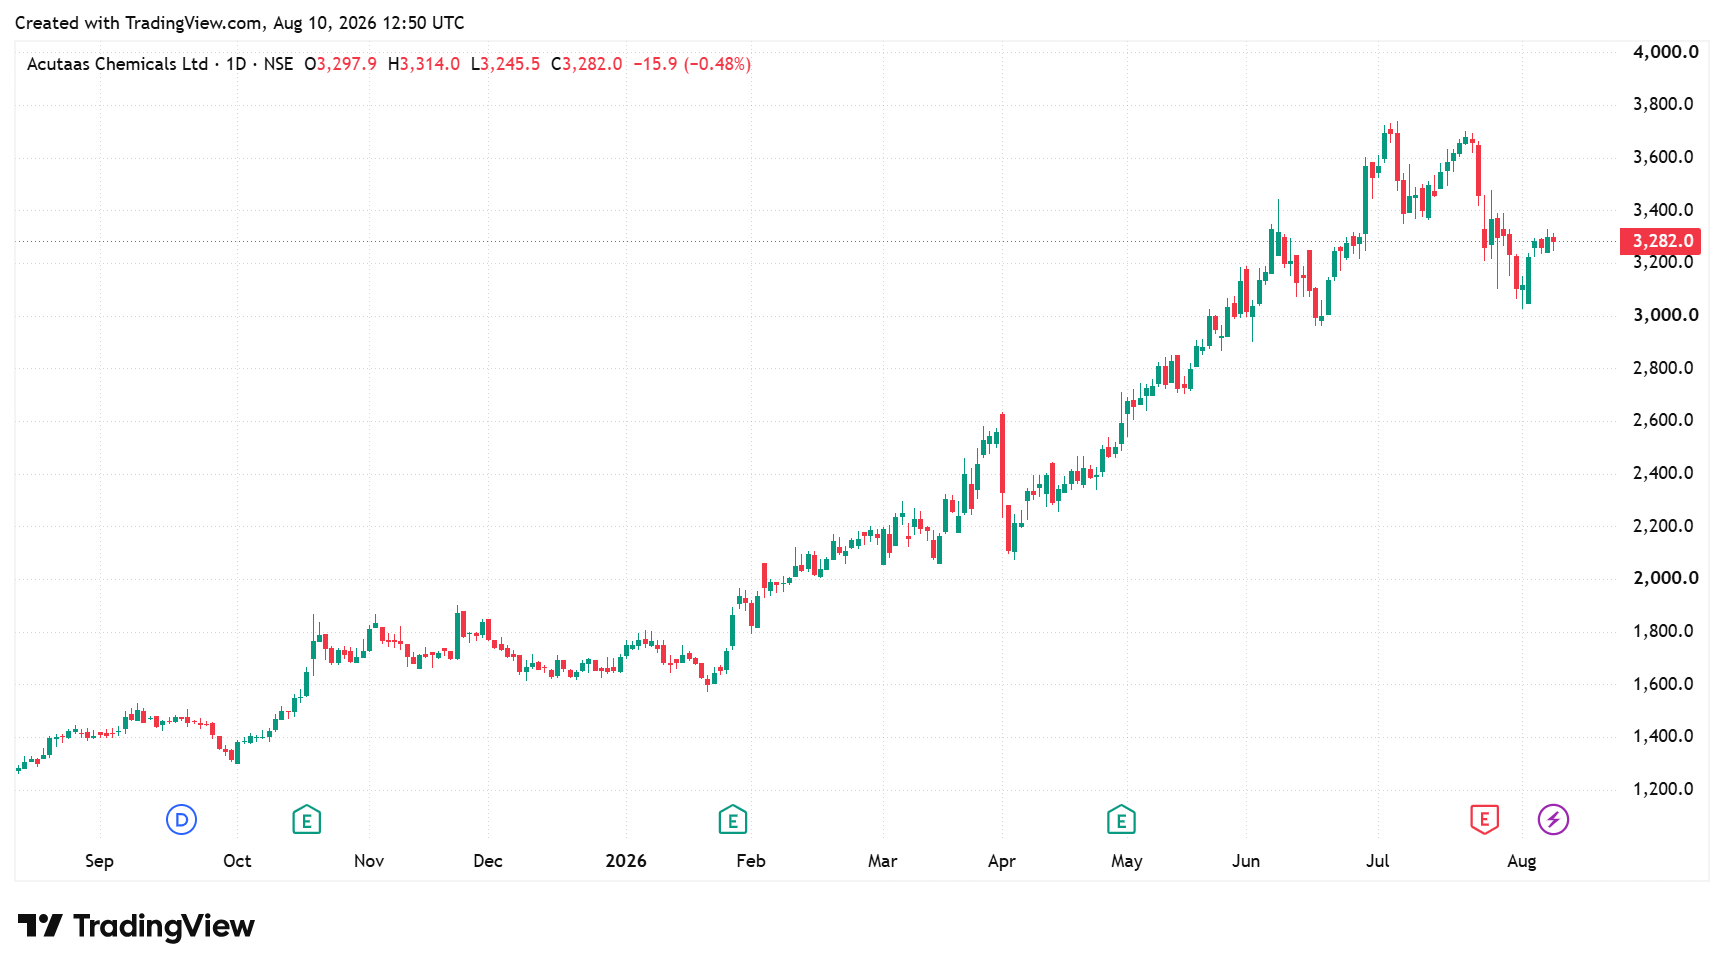
Acutaas Chemicals is seeing higher demand in its semiconductor chemicals business driven by artificial intelligence. Management views this as a structural growth trend. This trend is already translating to a strong demand outlook for the photoresist chemicals it currently manufactures.
Riding the AI Wave with Photoresist Chemicals
Acutaas’s subsidiary, Indichem, is constructing a plant in South Korea. In Q1FY27, out of a total capital expenditure of ₹56 crore, ₹15 crore was deployed at the Indichem site. Construction is expected to be completed by the end of Q2FY27.
Acutaas expects the revenue from the Indichem plant to start contributing from FY28. Management expects a relatively slow start initially due to a new business. Acutaas estimates full ramp-up within 3-4 years.
In terms of profitability, management expects the margin profile of Indichem’s semiconductor products to be compared with the margins of Specialty Chemicals (which operate at roughly 24%). In the specialty chemicals segment, battery chemicals and semiconductor business are two high-growth areas in which it is building capabilities.
Revenue Shifting: The Ascent of Specialty Chemicals
Over the next 3 years, Acutaas expects these two segments to shift Acutaas’s consolidated revenue mix. The Specialty Chemicals revenue share is projected to expand from 13% in FY26 to approximately 20%. At the same time, Pharma Intermediates revenue contribution is projected to fall from 87% to roughly 80%.
CDMO Pipeline and Q1 Financial Surge
Financially, revenue from operations surged 59.1% year-on-year to ₹329.7 crore in Q1FY27. Higher revenue contribution from the Pharmaceutical Intermediates business drove the revenue growth. EBITDA grew 122.1% to ₹113.1 crore with margins at 34.3%. Net profit grew 70.4% to ₹75 crore. Management projects revenue growth of 25% in FY27 with stable margins.
Management expects 4 validated CDMO products to begin contributing to revenue from H2FY27. Each of these four products is expected to generate between ₹50-100 crore annually at their peak. Acutaas’ pharmaceutical business alone contributed ₹1,174 crore in FY26. It is now targeting ₹1,000 crore revenue from CDMO only by FY28.
Why Acutaas Leads in Return on Capital
Acutaas, with its strong financial growth, has a return on capital employed (RoCE) of 31.6% and a return on equity (RoE) of 24%. Archean’s volatile financials mean its return ratios significantly lag behind sector peers. In terms of valuation, the company is trading at a premium to both its 3-year historical and industry median.
| Peer Valuation | |||||
Particulars | Price-to-Earnings Multiple (X) | Return Ratios | |||
| Company | 3Y Median | Industry | ROCE (%) | ROE (%) | |
| Acutaas Chemicals | 69.6 | 63.0 | 33.2 | 31.6 | 24.0 |
| Archean Chemicals | 66.2 | 33.9 | 28.6 | 7.4 | 5.4 |
| Source: Screener.in (Source: 10 August 2026) | |||||
India’s semiconductor build-out could open a new growth avenue for both companies, but the opportunity is still developing. Archean is making a larger capital commitment to silicon carbide manufacturing, while Acutaas is expanding its semiconductor chemicals portfolio.
But the journey will not be without risks. Archean faces high capex and execution risk as it builds a new semiconductor facility. Acutaas faces ramp-up and customer validation risks. For both, the key will be converting investments into sustainable revenue and returns.
Meanwhile, it’s worth keeping them on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was not available have we used an alternate but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.