



India’s water infrastructure is entering a new phase of investment as rising urbanisation, industrial growth, data center boom, and increasing water stress drive demand for water supply and wastewater systems.
According to CRISIL Intelligence, India’s water and wastewater market is expected to increase from ₹3.95 lakh crore during FY20-FY24 to ₹6.31-6.51 lakh crore during FY25-FY29, driven by higher municipal and industrial investments.
The need for reliable water infrastructure has become more urgent as many regions face groundwater depletion, ageing water pipelines, water losses, and stricter wastewater treatment norms.
At the same time, programmes such as Jal Jeevan Mission, AMRUT, Namami Gange, and other urban water projects continue to create a large pipeline of new projects across the country. Although this sector faced some challenges under the Jal Jeevan Mission in FY26, those issues are now a thing of the past.
That said, as the sector gears up for a recovery, companies across the water value chain, from pumps and flow control systems to water treatment and turnkey infrastructure projects, stand to benefit from the next investment cycle.
This article focuses on three such companies:
| Company | Core Business | Growth Driver | Order Book | Risks |
| WPIL | Pumps, flow control products, turnkey water & wastewater projects | JJM Phase 2 revival, South Africa acquisition, higher-margin wastewater projects | ₹4,936 crore order book and ₹3,000+ crore order in South Africa | Delays in government fund releases and domestic project execution |
| EMS | Urban water supply, sewerage, and wastewater EPC | Recovery in urban projects, margin normalization, and fresh order inflows | ₹1,837 crore order book with over two years of revenue visibility | High dependence on government-funded urban projects and payment cycles |
| Welspun | Water treatment plants, transmission pipelines, tunnelling, and 15-year O&M | Large wastewater projects, O&M revenue, SmartOps technology | ₹13,817 crore water order book (70% of total order book) | Slower execution of large EPC projects and higher valuation |
| Source: Management Commentary, Investor Presentation | ||||
#1 WPIL: International Orders Drive Margin Growth
WPIL is a global provider of pumps, flow control products, and turnkey water solutions. These specialized pumps and flow control products are used in heavy-duty and critical applications. WPIL also acts as a contractor for large-scale, turnkey infrastructure projects.
Its water work includes building smart, large-scale irrigation networks with canals and reservoirs that help farmers maximize water efficiency and grow crops. For towns and cities across India and Africa, WPIL designs large-scale water supply and drainage systems to deliver clean water to households.
It plays a key role in major government initiatives such as the Jal Jeevan Mission. Further, they tackle highly complex environmental challenges by building advanced wastewater treatment and water recycling plants for industrial and municipal clients. Its presence spans India (41% of revenue), Italy (27%), South Africa (26%), and Australia (6%).
Diversified Footprint Offsets Domestic Headwinds
WPIL delivered a resilient performance in FY26, driven by a diversified global footprint despite short-term headwinds in its domestic operations. The domestic business faced difficulties in due to delays in the receipt of government funds, stalled work, and rising trade receivables.
Still, its revenue rose 3% year-on-year to ₹1,855 crore in FY26. EBITDA increased by 9% to ₹318.3 crore, while the margin expanded by 97 bps to 17.2%. Net profit grew by 2% to ₹199.7 crore.
The major growth driver was the international operations, which now account for 61.2% of the total revenue. International revenues jumped to ₹1,136 crore in FY26 from ₹668 crore in FY25. EBITDA surged 72.7% to ₹152 crore.
Order Book Visibility: The Impact of JJM Phase 2
WPIL entered FY27 with an order book of ₹4,936 crore. However, with the Jal Jeevan Mission (JJM) Phase 2 recently cleared by the cabinet, fresh funds are already being allocated to states like West Bengal and Uttar Pradesh.
Management expects a strong revival in project execution and the release of new tenders by Q2FY27. Given that JJM Phase 2 has a strict completion deadline of December 2028, the next 30 months will require substantial, concentrated investments in pump supplies and water infrastructure.
High-Margin Tailwinds via PCI Africa Acquisition
The company recently acquired PCI Africa internationally. Through this acquisition, WPIL has secured project orders worth over ₹3,000 crore in South Africa. Unlike Indian contracts, these South African projects are highly complex and involve technology-based wastewater and water reuse plants.
As a result, it has relatively higher profit margins, is cash-positive, and offers better commercial payment terms. Revenues from these 3- to 4-year contracts will ramp up significantly starting in H2 of FY27, providing revenue visibility and margin expansion. Management expects WPIL to report a sustainable EBITDA margin of 15-20%.
#2 EMS: Revenue Drops Amid Payment Delays
EMS Limited is an engineering, procurement, and construction (EPC) company that serves as a sewerage solutions provider, handling water supply systems and water and waste treatment plants. The company generates about 70-75% of its business from the water sector, a focus it plans to rigorously maintain.
The Strategic Pivot From Rural to High-Value Urban Programs.
EMS focuses on government-funded schemes, specifically targeting urban infrastructure. The company actively executes projects such as the Atal Mission for Rejuvenation and Urban Transformation and the Namami Gange program. The company targets the urban sector rather than rural schemes such as the Jal Jeevan Mission or the Swachh Bharat Mission.
Inside the FY26 Revenue Drop: Pinpointing the External Financial Strains
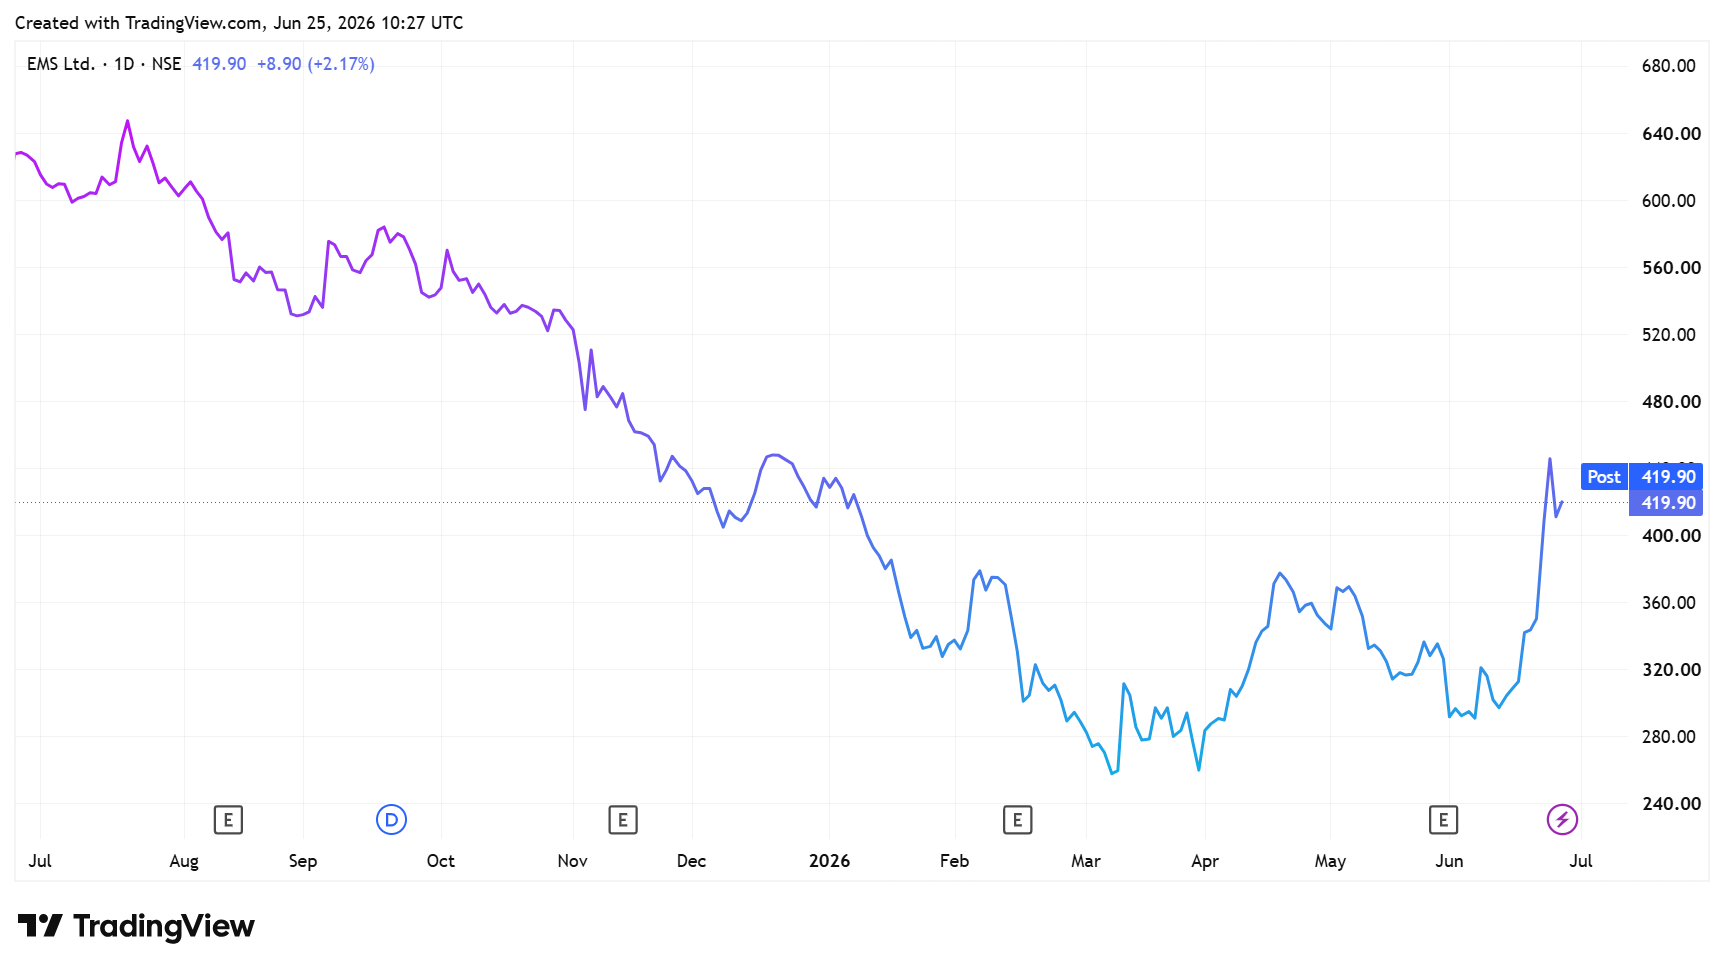
EMS faced external challenges that severely impacted its finances. Consolidated revenue fell by 24% year-over-year to ₹733 crores in FY26. Operating profit fell by approximately 44.9% to ₹140 crore, as margins contracted by 710 bps to 19%. Net profit was nearly halved to ₹91 crore, down from ₹184 crore in FY25.
The SPARSH Portal Disruption: How Working Capital Tied Up in Escrow Accounts
Not only EMS but the broader sector faced a slowdown due to multiple factors. The government introduced a new internal payment portal called SPARSH, which serves as a common escrow account that combines Central and State government shares. This system is still in its gestation period, causing payment delays.
A major ₹780 crore project in West Bengal was halted during the elections. Heavy rainfall and landslides damaged transmission lines and property in Uttarakhand, forcing the company to pivot to restoration work before continuing core operations. These days pushed the inventory by approximately ₹100 crores because certain billing milestones could not be achieved.
Turning Point FY27: Management’s Blueprint for a 25% Margin Normalization
However, the company views this as a temporary cycle inherent to the civil engineering industry and expects margins to normalize. Management expects the margins to rebound to around 25% in FY27. Revenue recovery to ₹1,000 crore in FY27 is likely, according to management.
Translating a ₹1,837-Crore Pipeline into Two-Year Revenue Visibility
Its order book is strong enough to support revenue growth if execution improves. As of 31 March 2026, the unexecuted order book stood at ₹1,837 crore, providing revenue visibility of over two years. EMS aims to secure projects worth ₹1,500 crores this year from a pipeline of ₹2,500- ₹3,000 crores.
The management remains highly optimistic about the structural tailwinds in India’s urban water and wastewater sector. It noted that the current market offers “tremendous and huge scope”. Because the company has captured only about 1% of the pan-India urban scope, it has no plans to diversify away from the government water sector.
#3 Welspun Enterprises: Mega Order Book Drives Visibility
Welspun Enterprises operates an integrated water vertical (water, pumping, tunneling, and rehabilitation) that currently accounts for 70% of its ₹19,739 crore order book. Within the water sector, Welspun focuses on complex EPC projects and long-term Operations & Maintenance (O&M) lifecycle management.
This company designs, constructs, and operates water treatment plants for municipalities. It is currently building India’s first multi-storied wastewater treatment plant in Dharavi, Mumbai, designed to treat 41.8 crore liters (CLD) of wastewater daily.
Welspun is also building large-scale municipal water treatment complexes, such as the 2,000 MLD Bhandup Complex and the 91.0 CLD Panjarpur facility in Maharashtra. The company is a pioneer in trenchless technology and complex tunnelling.
Sub-Surface Engineering: Breaking Ground via Complex Tunnelling Tech
It constructs underground water conveyance systems, such as an 8.48 km, 3,500 mm-diameter bored tunnel that will transfer tertiary-treated water from Dharavi to Ghatkopar. Welspun also specializes in pipeline rehabilitation for water and wastewater infrastructure
Welspun also restores aging urban drainage systems. For example, it is using innovative geopolymer lining technology to rehabilitate Mumbai’s 17-kilometer-long stormwater drainage channels. The company is also utilizing a 2.5-kilometer glass-reinforced polymer lining for mega trunk drains in Vadodara to mitigate severe urban flooding.
Additionally, Welspun has developed a specialized technology called SmartOps. SmartOps uses technology that requires minimal space and enables fast deployment of wastewater treatment. This technology is being employed for tasks such as cleaning natural water sources and upgrading sewage treatment plants.
Lifecycles and Long-Term Yields: Unpacking the 15-Year O&M Segments
Moreover, Welspun is also involved in the long-term management of these assets. For major projects such as the Dharavi, Bhandup, and Panjarpur treatment plants, Welspun is contracted to provide 15 years of continuous O&M after construction is complete.
This broader scope at Welspun allows it to offer comprehensive, end-to-end project execution. It’s a major player in JJM in Uttar Pradesh, constructing water supply systems that will serve 2,544 villages across five key districts. As of the end of FY26, Welspun had executed 80% of UP JJM projects and anticipates completing construction in FY27.
Welspun’s current order book for the water business stands at ₹13,817.3 crore, providing strong multi-year revenue visibility. In FY26, the water segment witnessed a 3% year-on-year revenue decline due to slower project execution. Its water subsidiary, Welspun Michigan Engineers, is expected to grow at a CAGR of over 25% over the next three years.
Evaluating the Growth Pillars: Margin Structures and Pipeline Conversion
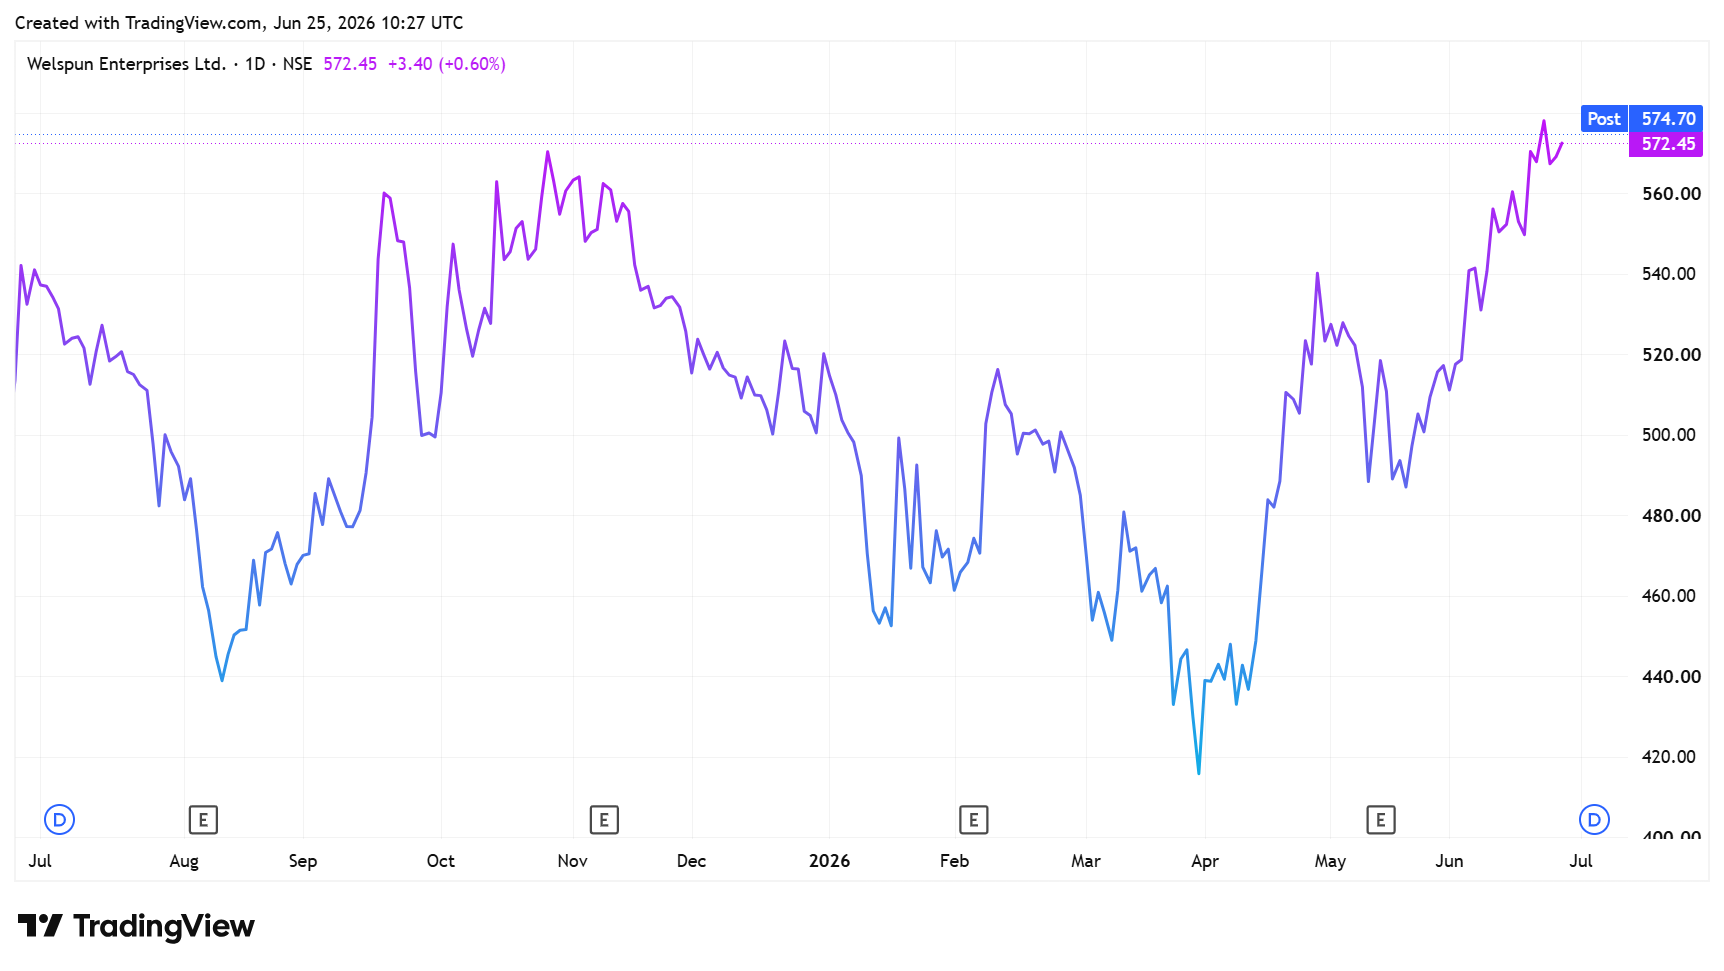
Coming to consolidated financials, Welspun’s revenue declined by 2% to ₹3,615 crore in FY26. Despite the slight decline, this was in line with the management’s revenue guidance of ₹3,600 crore. However, operational performance was strong with EBITDA growth of 16% to ₹845 crore as margins expanded by 350 bps to 23%. Net profit grew 11% to ₹393 crore.
Valuation Matrix: Pricing Efficiency Against Historic Multiples.
Welspun has a higher Return on Capital Employed (ROCE) than WPIL and EMS, indicating more efficient use of capital. From a valuation perspective, all three players are trading at a premium to their three-year historical median multiple. Compared to the industry multiple, WPIL is trading at a slight discount, EMS at roughly the same level, and Welspun at a premium.
| Peer Comparison (X) | |||||
Company | Price-to-Earnings Multiple | Return Ratios | |||
| Company | 3Y Median | Industry | ROCE (%) | ROE (%) | |
| WPIL | 31.0 | 26.2 | 32.6 | 14.6 | 10.7 |
| EMS | 26.0 | 19.1 | 25.6 | 12.5 | 8.9 |
| Welspun | 20.1 | 19.4 | 17.9 | 16.8 | 14.1 |
| Source: Screener.in (Data as of 25 June 2026) | |||||
After a temporary slowdown in FY26, India’s water infrastructure cycle appears to be regaining momentum. With Jal Jeevan Mission Phase 2, rising investments in urban water and wastewater projects, and multi-year order books already in place, execution is expected to improve over the next few years.
Companies that can convert these large order pipelines into profitable and timely execution are likely to be the biggest beneficiaries of the next phase of growth. However, as these companies are highly exposed to government spending, project execution and payment cycles remain key factors to watch.
Nonetheless, these names could be kept in your watchlist to track their execution.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.