



Dolly Khanna Portfolio Update: The June 2026 Quarter Purge
Dolly Khanna does not do interviews. The Chennai based investor, whose portfolio is managed by her husband Rajiv Khanna, has been picking small companies since 1996. Fertilisers, sugar, textiles, chemicals. Her name on a shareholding list is often enough to move a stock.
That is why her June 2026 filings drew so much attention. In March 2026, public records showed nine companies where she held 1% or more. By the end of June, that list had shrunk to three. Six names, Emkay Global, Rain Industries, Som Distilleries, Sharda Cropchem, Southern Petrochemical Industries and Coffee Day Enterprises, dropped below the 1% disclosure mark for the first time.
What survived the cut is a compact book worth Rs 308 cr at current prices. A refiner, a steelmaker and a hotel. Three businesses that could not look more different on the surface. Look closer, though, and they share one habit. All three pay their shareholders to wait.
Join now
The Big Purge: Why Khanna Dropped 6 Names
The departures tell their own story. Emkay Global, a broking house, stood at 1.7% in March 2026. Som Distilleries, a beer maker, was at 1.5%. Sharda Cropchem, an agrochemical firm, at 1.1%. Southern Petrochemical Industries, a fertiliser producer she owned 3% of as recently as September 2025, at 1.8%. Rain Industries, a carbon products maker, at 1.1%. Coffee Day Enterprises, the parent of the cafe chain, at 1.7%.
By June, all six had slipped below the 1% reporting threshold. A word of caution here. Falling below 1% does not always mean a full exit. Companies only have to name shareholders above that line, so she may still hold small residual stakes in some of these names. What the filings confirm is that she chose not to stay above the line in any of them.
The survivors were not left untouched either. She trimmed Prakash Industries from 2.3% to 2.1%. And in the quarter’s quietest move, she raised her stake in Savera Industries from 1.1% to 1.7%. More on that later.
#1 Chennai Petroleum Corporation (CPCL): The Refiner Dominating 82% of Her Book
With a current market cap of Rs 20,025 cr, Chennai Petroleum Corporation, or CPCL, refines crude oil into petrol, diesel, LPG, kerosene and aviation fuel at its Manali refinery near Chennai. Its parent, Indian Oil Corporation, markets most of its products, and promoters together hold 67.29% of the company.
Khanna holds 18.99 lakh shares, a 1.3% stake worth about Rs 257 cr. That single position accounts for nearly 82% of her disclosed portfolio. For an investor known for spreading her bets across small, unloved companies, this is a striking level of concentration in one large public sector refiner.
The stock has rewarded that faith. It is up 109% over the past year, and the company earned Navratna status earlier this year, a government tag that gives public sector firms more freedom to invest on their own.
How Refining Margins Dictate Profit Growth
The business swings with refining margins, the gap between what a refiner pays for crude and what it earns on the fuels it sells. Those swings show up plainly in the numbers.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 22,222 | 43,068 | 76,271 | 66,024 | 58,983 | 63,148 | 23% |
| EBITDA (Rs cr) | 2,012 | 2,732 | 5,698 | 4,476 | 1,038 | 4,757 | 19% |
| Net Profit (Rs cr) | 257 | 1,352 | 3,532 | 2,745 | 214 | 3,103 | 64% |
EBITDA refers to operating profit before other income. A note on the table. FY21 was depressed by the pandemic, and FY20 before it was a Rs 2,056 cr loss year. The 64% profit growth rate is flattered by that low base, so the year-by-year numbers matter more than the compound rate here.
FY25 shows how brutal the cycle can be. Net profit collapsed to Rs 214 cr as margins thinned. FY26 swung right back to Rs 3,103 cr. The June 2026 quarter kept up the pace. Sales came in at Rs 27,369 cr with a net profit of Rs 1,031 cr, against a Rs 40 cr loss in the same quarter last year. The gross refining margin for the quarter stood at $8.78 a barrel. One caveat applies. The quarter included a one-time gain from a retrospective revision in petroleum product prices, so the full amount is not repeatable.
The balance sheet has been repaired alongside. Borrowings fell from Rs 9,167 cr in FY21 to Rs 1,964 cr in FY26. Return on capital employed (ROCE) stands at 35% and the management has spoken of Rs 2,000 cr in capital spending over the next two to three years on new projects.
Share Price Target and 4.6% Dividend Yield
The share price of Chennai Petroleum was around Rs 101 in August 2021 and as on 17th August 2026 it was Rs 1,345
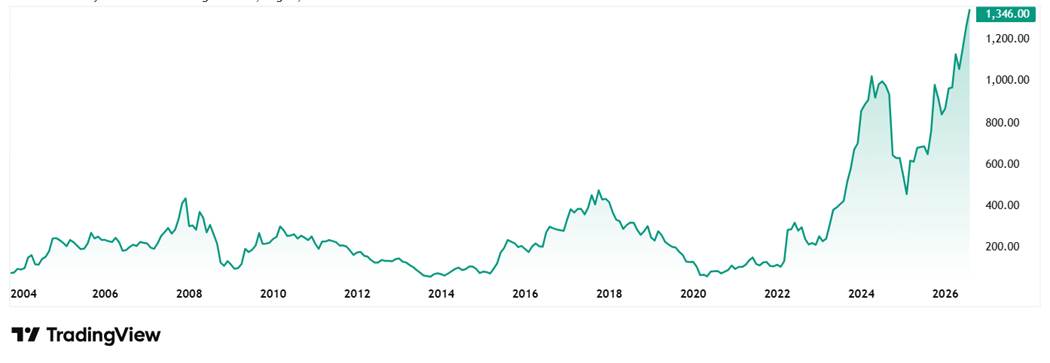
On valuation history, the stock is trading at a PE of just 5x currently and the industry median is 10x. 10-year median PE stands at 5x as well, while the industry median for the same period is 9x.
Then there is the dividend, the thread that ties this portfolio together. The stock offers a 4.6% yield, double of the industry average of 2.3%, and the company has paid out close to 30% of profits in each of the last three years. Honesty demands a caveat here too. CPCL paid nothing in its loss years between FY19 and FY21. The dividend is generous when refining is good and absent when it is not.
Foreign institutional investors have taken note as well, raising their stake from 12.6% in March 2026 to 15% in June. The number of retail shareholders, meanwhile, has come down from over 2 lakhs in March 2025 to about 1.5 lakh in June 2026, even as the stock doubled.
#2 Prakash Industries: Expanding Margins Through Captive Coal and Power
Prakash Industries, with a current market cap of Rs 2,316 cr, makes sponge iron, steel billets and ferro alloys, and generates its own power at its Chhattisgarh plants. It also mines its own coal now, extracting 3.3 lakh tonnes from its captive mine in the June quarter alone.
Khanna holds 37.94 lakh shares, a 2.1% stake worth about Rs 49 cr. She has been here a while, building the position from 1.2% in mid-2024 to a peak of 2.9% in September 2025, before trimming to the current level.
The financials explain some of that caution.
Financial Metrics: Sales, EBITDA, and Profit Trends
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 3,216 | 3,929 | 3,444 | 3,678 | 4,014 | 3,479 | 2% |
| EBITDA (Rs cr) | 315 | 391 | 413 | 493 | 520 | 513 | 10% |
| Net Profit (Rs cr) | 95 | 169 | 190 | 348 | 355 | 333 | 29% |
EBITDA refers to operating profit before other income. Sales have gone nowhere in five years, compounding at just 2%. Profits are a different story, compounding at 29%, though the weak FY21 base flatters that number as well. The real driver is margins. Operating margins improved from 10% in FY21 to 15% in FY26 as captive coal and power cut costs.
Share Price Performance and Current Valuation
The share price of Prakash Industries was around Rs 67 in August 2021 and as in 17th August 2026 it was Rs 129.
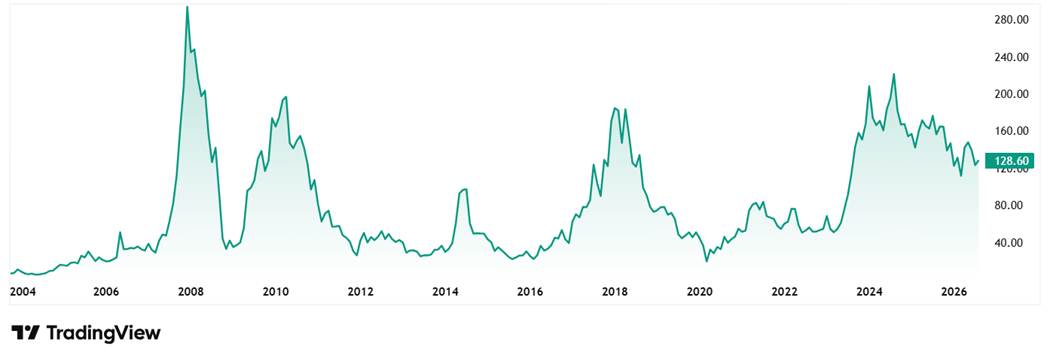
As for valuation, the company’s share is currently trading at a PE of 7x and the industry median is 18x. The 10-year median PE for the company is 8x while the industry median for the same period is 14x.
How the New 23% Tax Rate Impacted Prakash Industries
The June 2026 quarter came with a plot twist. Sales rose to Rs 1,032 cr and operating profit hit Rs 147 cr, the highest in years. Yet net profit fell to Rs 71 cr. The reason sits in one line of the results. Tax. For years the company’s tax charge was close to nil, a point long flagged in its financials. In the June quarter it paid tax at 23%, a full normal rate.
Investors will now watch whether earnings settle at this lower, taxed level. The market’s first response was upbeat all the same, with the stock jumping 12.36% on 14th August 2026, days after the results.
The dividend record is the thinnest of the three, but it is moving in the right direction. The payout ratio has climbed from 6% in FY24 to 8% in FY25 and 10% in FY26. The current yield is 1.2%, while industry peers average about 0.2%.
Promoters hold 44.38% and have nudged their stake up over recent quarters, while the public holds a large 51.9%.
#3 Savera Industries: The Debt-Free Chennai Hotel She Bought More of
While six names fell away and Prakash was trimmed, Savera Industries, the only microcap with a market cap of Rs 194 cr in Khanna’s portfolio, was the one company where Khanna added. Her stake rose from 1.1% in March 2026 to 1.7% in June, or 2.03 lakh shares worth about Rs 3.3 cr at Rs 165 as on 13th August 2026.
In rupee terms, it is a rounding error next to her CPCL position. As a signal, it is harder to ignore. This is a Chennai investor adding to a Chennai institution.
Business Model and Post-Pandemic Sales Growth
Savera Industries has run the 4-star Hotel Savera in the city since 1969. It also operates seven health centres under the O2 Health brand, and in December 2024 it stepped into packaged drinking water with a new manufacturing plant on leased premises. The company is almost debt free.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 |
| Sales (Rs cr) | 20 | 32 | 61 | 72 | 80 | 102 |
| EBITDA (Rs cr) | -1 | 2 | 14 | 13 | 15 | 18 |
| Net Profit (Rs cr) | -4 | -1 | 12 | 10 | 13 | 13 |
EBITDA refers to operating profit before other income. The growth needs to be looked at differently here. FY21 was a lockdown year for hotels. Sales fell to Rs 20 cr and the company posted losses in FY21 and FY22, so any five-year rate built on that base misleads more than it informs. The cleaner read is this. Sales have grown from Rs 61 cr in FY23 to Rs 102 cr in FY26, a 19% compound rate over three years.
The momentum has carried into the new year. June 2026 quarter sales came in at Rs 28.8 cr, up 30% from a year earlier, with a net profit of Rs 3.81 cr.
Share Price History and Dividend Payout Ratio
The share price of Savera industries was about Rs 45 in August 2021 and as on 17th August 2026 it was Rs 163.
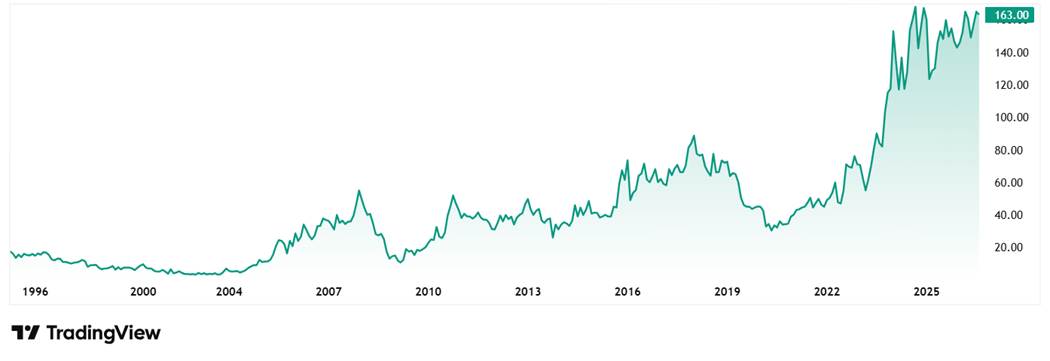
The stock trades at a PE of 18x currently which is lower than the current industry median of 28x. The 10-Year median PE for the company is 14x while the industry median for the same period us 36x. With about 5,322 shareholders on the register and a small market cap, trading volumes here can be thin, and thin volumes cut both ways.
On dividends, the hotel has an old habit of sharing. Payout ratios ran between 50% and 74% in the middle of the last decade, went to zero in the two pandemic loss years, and have held between 27% and 35% since FY23. The current yield is at 1.85% in a flat market, as peers average a yield of zero. Promoters raised their holding from 62.8% to 64.6% in the March 2026 quarter and have held it there since.
Of Hard Assets and Reliable Dividend Yields
Step back and the pattern is hard to miss. A refiner yielding 4.6%. A hotel paying out roughly 3 of every 10 rupees it earns. A steelmaker whose payout ratio has risen for three straight years. Khanna has let go of broking, beer, agrochemicals and coffee, and kept the three names that send cash back to shareholders.
There are other family traits. Promoters hold 67.29%, 44.38% and 64.62% of the three companies. All three own hard assets, a refinery, steel plants, a hotel. And all three are cyclical, which cuts both ways. CPCL’s FY25 showed how fast refining profits can vanish. Prakash has just started paying tax at the full rate. Savera leans on a single property in one city.
None of this tells us more than the June filings can. Whether this is conviction or caution, only the September quarter will say. A good idea would be to add these stocks to a watchlist and keep an eye on how the story unfolds.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.