



Artificial Intelligence has not only created a supply bottleneck for memory chips but is now creating a power problem. JLL estimates the global data centre capacity to almost double from 103 gigawatts (GW) in 2025 to 200 GW by 2030. Meeting this demand could require up to $3 trillion of investment.
At the same time, data centre electricity consumption is expected to rise 26% in 2026 alone. The bottleneck is pushing developers to look beyond the grid. In the US, data centre projects are increasingly being paired with gas-fired power plants to secure reliable electricity. The US gas power project pipeline has surged sharply in 2026 as AI drives demand for dedicated power.
This creates a less obvious opportunity in the AI infrastructure chain: pipes. Gas-fired plants need pipelines to transport fuel, while data centres need specialised piping for cooling and thermal management. This is bringing pipe manufacturers into a capex cycle, even though they do not manufacture a single semiconductor chip or server.
Two Indian companies are already positioned to capture this opportunity. One has up to 35% of the US large-diameter line pipe market and has its US capacity booked through FY28. The other supplies specialised piping for data centre cooling and gas turbine applications, with its Thailand plant fully booked for the next three years.
#1 Welspun Corp: Resolving Grid Bottlenecks Across North American Tech Hubs
Welspun Corp is the largest player globally in the large-diameter line pipe industry. Its presence spans India, the US, and Saudi Arabia, providing critical infrastructure solutions for energy and water transport. Large-diameter pipe transports oil and gas over long distances. Welspun holds 33%-35% of the US line pipe market.
The company’s Large-Diameter Line Pipes span three types: Longitudinal Submerged Arc Welded (LSAW), Helical Submerged Arc Welded (HSAW), and High-Frequency Induction Welded (HFIW). For Welspun, the expansion of AI data centers in the US has become a big catalyst.
How AI data centers are fuelling pipeline demand
Data center developers are building on-site gas power plants to run them. Welspun is directly benefiting from this trend because these dedicated power plants require pipeline connections to supply them with natural gas. The demand is such that the order book for gas turbines in the US has surged to 300+ for the next 4-5 years from only about 5-10 turbines sold two years back.
This highlights the strength of the demand. Welspun pipes connect these turbines to the gas supply. This positions the company as an integrated player in this energy value chain. There is another tailwind. US data centers are moving away from congested metropolitan areas to rural regions like the Midwest and Arizona.
Why the rural shift accelerates long-distance pipeline needs
As data centers move into rural regions, they must transport natural gas over long distances. Welspun supplies both Spiral (HSAW) and LSAW steel pipes for data center connections. Currently, Welspun’s US pipeline portfolio is divided between approximately LNG export lines (75%), while 25% aligned with the data center theme.
However, management expects order bookings to progressively shift further in favor of data centers. Historically, Welspun’s normalized EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortisation) guidance for its US operations has been US$300 per ton. Management now expects the EBITDA to be much higher than the historical trend.
FY28 capacity booked amidst surging order execution
Welspun’s US capacity is booked through FY28. The pipeline of data center-related projects is already giving the company visibility and clarity emerging for FY29. As of 20 August, 2026, the company’s global order book stood at ₹42,100 crore. It secured a major order worth ₹17,200 crore to supply pipes from its US plant. This order is to be executed between FY28 and FY29.
To capture the strong momentum in the US market, the company is executing two major plant expansions in Little Rock. High-Frequency Induction Welded and Electric Resistance Welded mills are fully commissioned. LSAW Plant is on track to be fully operational by the end of FY27. The full financial and volume impact of these expansions will be visible starting in FY28.
Why India’s national gas grid expansion offers indirect tailwinds
In India, management stated that the infrastructure rollout will differ from the US. Here, unlike the US, Indian data centers will likely tap into the existing National Gas Grid. This still benefits Welspun indirectly. Grid operators (like GAIL) are forecasting plans to add 10,000 kilometers of pipeline to complete the grid infrastructure. This will drive domestic pipe demand.
Welspun delivered robust growth in Q1FY27. Revenue increased 15% year-on-year to ₹4,081 crore. EBITDA surged 35% to a record ₹756 crore as margins expanded by 270 bps to 18.5%. Adjusted net profit (without exceptional items) jumped 42% to 499 crore. The company held net cash of ₹2,336 crore. Welspun has guided to reach ₹20,000 crore in revenue and ₹2,850 crore in EBITDA in FY27.
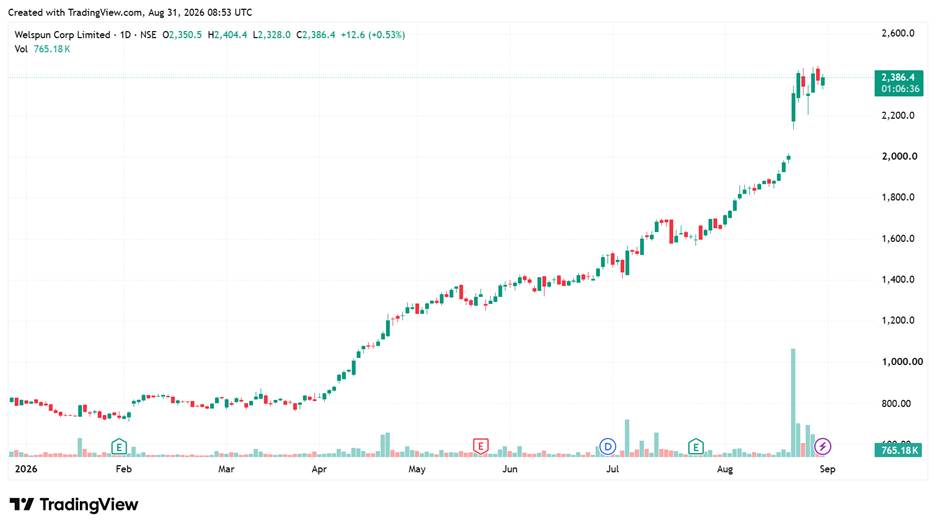
Welspun Corp Share Price is up 200% in 2026 YTD
#2 DEE Development Engineers: Capitalizing on Global Gas Turbine Backlogs
DEE Development Engineers (DDEL) is India’s largest company in process piping solutions in terms of installed capacity and ranks among the top five companies globally. It serves customers across 27+ countries and 4 continents, including the USA, Canada, Italy, and Japan.
How Global Manufacturing Scales High-Barrier Engineering Solutions
This company provides engineering solutions to high-entry-barrier sectors like oil and gas, petrochemicals, power, and infrastructure. DDEL operates 7 manufacturing facilities across India and Thailand. Its annual capacity stands at 93,500 metric tonnes (MT) of Process Piping capacity and 32,400 MT of Heavy Fabrication capacity.
Data centers require cooling infrastructure to operate server racks at optimal temperatures, as they generate significant heat. To support these cooling systems, DDEL supplies rigid and metal piping solutions. These pipes are used in chillers and thermal management networks inside data centers.
Why the Data Center Boom Represents a Massive Revenue Pool
The size of the opportunity is substantial. Global data center capacity is projected to double to 200,000 MW by 2030. Management estimates a substantial revenue opportunity of ₹25 crore in piping solutions for every 25 MW of data center capacity. This translates into a vast addressable market for the company’s core engineering products.
This positions DDEL to tap into a global capex cycle, with overall data center capital expenditure projected to expand from US$0.5 trillion to US$1 trillion by 2026. Management notes that their pipeline for data center jobs is quite strong and expects these opportunities to materialize in the near-to-medium term.
How High-Pressure HRSG Demands Keep the Thailand Plant 100% Booked
Additionally, a Heat Recovery Steam Generator (HRSG) is an energy-recovery heat exchanger. It captures hot exhaust gases and uses them to boil water, thereby generating high-pressure steam. This high-pressure steam is then conveyed via piping to a steam turbine to generate further electricity.
Transporting such intense heat and high-pressure steam from the HRSG to the steam turbine requires specialized piping systems. DDEL’s Thailand plant (14,500 MTPA) supplies specialized HRSG piping to global OEMs like Siemens, GE, and Nooter Eriksen. The plant is 100% booked for the next three years.
Why ₹2,428 Crore in Orders Secures Long-Term Revenue Visibility
Financially, Q1FY27 revenue rose by 31.6% year-on-year to ₹294.5 crore, driven by 33% growth in the core business. EBITDA surged 38.7% to ₹49.7 crore, while margins expanded 86 bps to 16.9%. Net profit grew by 22.4% to ₹16.1 crore.
As of 30 June 2026, the order book stood at ₹2,428 crore, providing two years of revenue visibility. DDEL anticipates an additional ₹1,300-1,800 crore in new order inflows in 9MFY27. DDEL has projected a revenue target of ₹1,500 crore for FY27. The long-term strategic target is to unlock ₹2,500 crore in consolidated revenue with 20% margins by FY30.
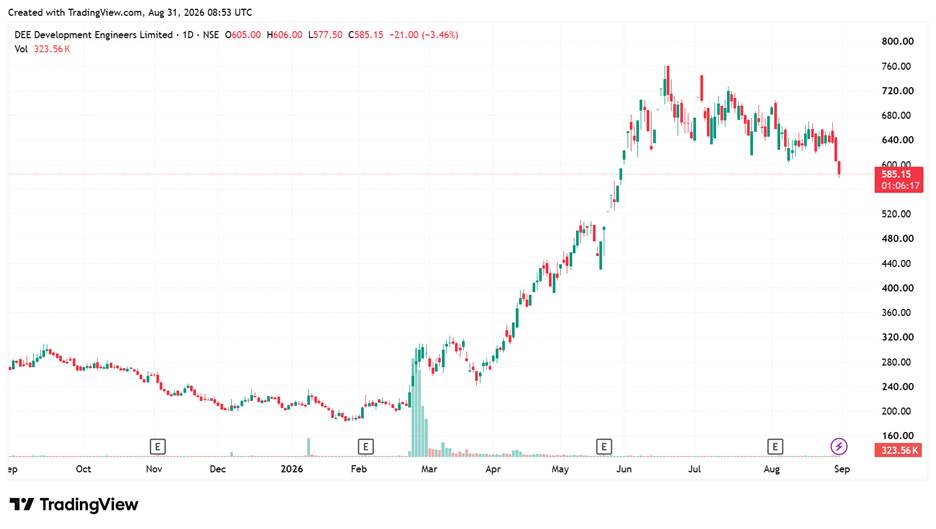
DDEL Share Price Up 179% in 2026 YTD
Here’s a snapshot of the Q1FY27 financial performance:
| Particulars | Welspun Corp | DEE Development |
| Revenue (Growth YoY) | ₹4,081 crore (+15%) | ₹294.5 crore (+31.6%) |
| EBITDA (Growth) | ₹756 crore (+35%) | ₹49.7 (+38.7%) |
| EBITDA Margin | 18.5% | 16.9% |
| Net Profit | ₹499 crore (+42%) | ₹16.1 crore (+22.4%) |
| Order Book | ₹42,100 crore | ₹2,428 crore |
| FY27 Outlook | ₹20,000 Crore Revenue, ₹2,850 crore EBITDA | ₹1,500 crore Revenue |
Both companies reported strong Q1FY27 results, but their profiles differ. Welspun offers greater scale and a ₹42,100 crore order book. DEE Development is growing faster from a smaller base, with a ₹2,428 crore order book.
Piping Valuations: Analyzing the Sector Premia and Returns
Welspun boasts a stronger Return on Capital Employed (ROCE) and Return on Equity (ROE) due to superior growth and execution. On the other hand, DDEL’s return ratios are moderate due to recent capacity additions. However, they are expected to improve as utilization increases. In terms of valuation, after a multibagger run in 2026, both are now trading at a premium to the industry and their historical median.
| Peer Comparison (X) | |||||
| Particulars | Price-to-Earning Multiple | Return Ratios | |||
| Company | 3Y Median | Industry | ROE (%) | ROCE (%) | |
| DDEL | 53.2 | 39.0 (2.2Y) | 32.9 | 9.3 | 10.9 |
| Welspun | 27.2 | 17.4 | 22.2 | 19.4 | 22.9 |
The opportunity is becoming visible in the numbers. Welspun Corp’s ₹42,100 crore order book and US capacity booked through FY28 provide a strong execution runway.
While DDEL’s ₹2,428 crore order book offers nearly two years of revenue visibility. The bigger trigger could come from rising data centre power requirements, which are creating demand for both gas pipelines and specialised piping.
However, the market has already recognised this opportunity. Welspun and DDEL are up 200% and 179%, respectively, in 2026 and trade above their historical median valuations. As strong contenders, these stocks are worth keeping on your watchlist.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data was unavailable have we used an alternative, widely used, and accepted source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.