



The “Boring” Business of 100% Returns
While the market spent the year arguing over which electric-vehicle maker would win, two suppliers sitting a couple of layers below the carmakers quietly handed shareholders gains north of 100%. No glossy launch events. No founder on every business channel. Just metal, machining and steady order books.
Both these are relatively unknown names and they are the kind of names that rarely trend. One stamps and welds safety-critical parts that go under two-wheelers and cars. The other forges and machines precision components like connecting rods and crankshafts for engines, and increasingly for aerospace and farm equipment. Both carry low debt. Both make stable margins. And over the past year, both have left the broader market far behind. For scale, the whole Auto Parts and Equipment group per Trendlyne rose about 29% over the year. These two roughly doubled.
So, is this a clean case of quiet compounders being discovered? Partly. The deeper you go into the numbers, the more you see two businesses that rhyme but do not match. One has a five-year record to lean on. The other has barely a year on the tape. Let us look at each on its own terms.
#1 Belrise Industries: The Safety-Critical Challenger
Incorporated in 1988, Belrise Industries makes sheet-metal and casting parts, polymer components, suspension and mirror systems for two-wheelers, three-wheelers, cars and commercial vehicles. It claims roughly a 24% share of India’s two-wheeler metal-components segment, and it supplies a long list of original equipment makers at home and abroad.
With a market cap of Rs 21,993 cr, the company is a market newcomer listed only in May 2025. It is a premier automotive component manufacturer specializing in safety-critical systems for two-wheelers, passenger vehicles, and agricultural machinery.
Peeling Back the 40% Profit Jump
Here is where we must read carefully. Screener.in carries Belrise’s consolidated numbers only from the year ending March 2022, so a clean five-year growth rate is not actually available. Instead, here is the year-by-year picture.
| Financial Year | FY22 | FY23 | FY24 | FY25 | FY26 | 4Y CAGR |
| Sales (Rs cr) | 5,397 | 6,582 | 7,484 | 8,291 | 9,509 | 15% |
| EBITDA (Rs cr) | 755 | 875 | 928 | 1,021 | 1,154 | 11% |
| Net Profit (Rs cr) | 262 | 314 | 314 | 355 | 497 | 17% |
Sales have grown at a steady 15% over four years. But EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) has moved slower, near 11% in comparison. Net profit barely budged across FY23 and FY24, both stuck around Rs 314 cr, but calculated for the last 4 years, compounded at 17%. Operating margins have held in a tight 12% to 14% band, which is fine, not thrilling.
The eye-catching bit is the profit of Rs 497 cr in FY26, up about 40% from the last year. A big part of that lift is not from selling more parts. It is from paying less interest. Belrise used its IPO money to repay debt, and the interest line fell sharply after listing. So, a chunk of the recent profit surge is a deleveraging effect, not a sudden jump in the core business.
A 175% Listing Premium: Is the Growth Priced In?
The share price of Belrise was about Rs 90 on listing in May 2025 a year ago, and as on 22nd of June 2026 it was Rs 247, which is a 175% jump in just a year. Rs 1 lac invested in the stock on listing would have been close to Rs 2.75 lacs today.
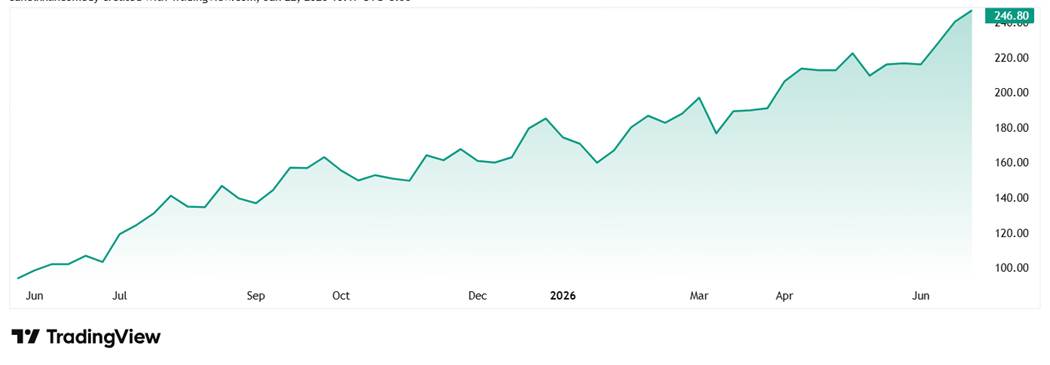
Regarding valuation, Belrise shares are trading at a PE of 44x against the current industry median of 28x. So, the stock is priced at a premium to its peer group; the market probably is banking in the return stream to continue.
A ten-year median PE is meaningless for a stock that has traded for barely a year, so I have left it out rather than guess.
On capital returns, Belrise posts a return on capital employed (ROCE) of about 15% and a return on equity near 13%. In plain terms, for every Rs 100 the business put to work last year, it earned about Rs 15 before interest and tax. Promoter holding stood at 66.46% in March 2026, down from 73% before the listing dilution.
Domestic institutions (DIIs) increased their stake from 7% at listing to over 10% in March 2026, with names like SBI Small Cap Fund, Mahindra Manulife Multicap Fund and Nippon India Smallcap Fund on the list
The Catch: Heavy Acquisitions and Crowded Markets
Free cash flow was negative in FY25, at about minus Rs 163 cr, as the company spent heavily on capacity and acquisitions. However, in March 2026, this changed to Rs 258 cr.
It also operates in a crowded field, going up against larger listed peers like Uno Minda, Motherson and JBM Auto, so pricing power is limited and customers can switch. The growth bet now leans on newer areas like defence and aerospace, where Belrise has set up a dedicated arm and bought a UK precision-engineering business. These are early-stage and unproven at scale. And with only a year of trading history, the stock has no track record across a full cycle.
#2 Sansera Engineering: Supplying to 9 out of 10 Automakers in India
Incorporated in 1981, Sansera Engineering is an engineering-led maker of complex, high-precision forged and machined parts. Think connecting rods, crankshafts, rocker arms and gear-shifter forks.
With a market cap of Rs 18,509 cr, the company has been among the top 10 global suppliers of connecting rods for light and commercial vehicles, and it is steadily building a non-automotive book across aerospace, off-road and agriculture.
No wonder the company supplies to 9 out of the top 10 automakers in India, with clientele including names like Honda, Maruti Suzuki, Toyota, Royal Enfield, KTM , Yamaha, Volkswagen etc. It also supplies to Boeing and UTAS, a leading European OEM, in the Aerospace division.
Steady Margins and a Post Covid Recovery
Let us look at the financials to try and find out the math behind the returns.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 1,549 | 1,989 | 2,338 | 2,811 | 3,017 | 3,498 | 18% |
| EBITDA (Rs cr) | 274 | 336 | 380 | 482 | 517 | 632 | 18% |
| Net Profit (Rs cr) | 110 | 132 | 148 | 188 | 217 | 327 | 24% |
One honest caveat on that 24% profit growth. The base year, FY21, was following a Covid-hit low, with profit of Rs 110 cr. So, part of the five-year rate reflects a recovery off a soft start. Even so, the trend is clean. Operating margins have held steady in a 16% to 18% range right through, which is the real tell. This is a business that protects its pricing and its mix rather than chasing volume at any cost.
A 267% Surge Fueled by Falling Debt
The share price of Sansera Engineering was about Rs 810 when listed in September 2021 and as on 22nd June 2026 it was Rs 2,969, which is a jump of 267% in about 5 years. Rs 1 lac invested in the stock at listing would have been about Rs 3.7 lacs today.
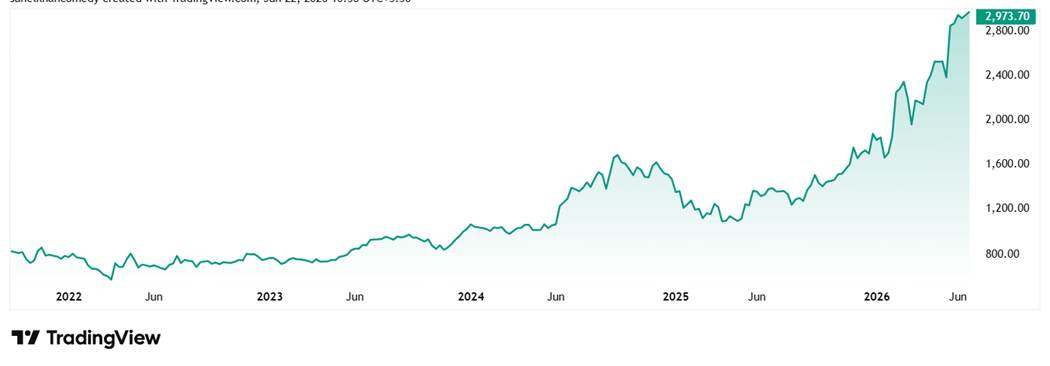
The stock has logged returns of over 125% just in the last 1 year.
On valuation, the company’s share is trading at a PE of 55x which is almost double of the industry median of 28x, as already seen with Belrise above. That is a clear premium to the auto-parts industry’s peer median. As with Belrise, a ten-year price-to-earnings band is not available, since the stock has traded only since 2021. So, we are paying up today for a record that, while good, is still short.
The capital-returns picture is the quieter weakness in the popular “capital efficiency” story. Sansera’s return on capital employed is about 14%, and its return on equity is a modest 12%. For every Rs 100 of shareholder money, the business earned only about Rs 12 last year. Both figures sit below the industry averages. The strength here is the balance sheet, not the returns ratio. Borrowings have come down sharply, from about Rs 891 cr in FY24 to roughly Rs 316 cr by March 2026, helped by an equity raise. Debt is low and falling.
The EV Risk and the Institutional Takeover
The ownership shift is something that has to be looked at seriously. Promoter holding has slipped to about 30% from roughly 35% a few years ago, while domestic institutions have piled in, lifting their stake to over 35% from just 12.6% in March 2022.
So, the quiet re-rating has been led by Indian mutual funds, not retail. One genuine long-term question hangs over the engine-parts core. A chunk of Sansera’s automotive sales comes from components tied to internal-combustion engines, which could shrink over time amid the shift to electric vehicles.
Management’s answer is to grow the non-automotive book in aerospace, defence and off-road, where parts are engine-agnostic, but that pivot is still a work in progress. The other watch items are the rich valuation and heavy capex, which pushed free cash flow to about minus Rs 123 cr in FY26.
Efficiency Myths and the Price of Admission
Put the two side by side and the headline number is the same, a double in about a year. The substance underneath is however something to think about. Sansera is the proven one with five years of steady margins and genuine double digit profit growth, but you are paying a full price for it today, at well above the industry multiple. Belrise is the fresh face which is larger by revenue and cheaper on the multiple, but its recent profit jump leans heavily on cutting interest costs after listing, and it has no cycle-tested record yet.
There is also a myth worth puncturing. Both stocks are often filed under “capital efficiency.” On the actual return ratios, both sit below their industry’s average on capital and on equity. What they share is not best-in-class efficiency. It is disciplined, falling debt, stable margins and a wave of institutional buying that retail mostly missed.
But one must remember that the biggest winners in a manufacturing upcycle are not always the brands you see on television. Sometimes they are the suppliers two layers below, doing unglamorous work. The smart move is not to chase the chart. It is to ask whether the price you pay today leaves room for the business to deliver. For both these names, that is a question worth sitting with before you act. Adding them to a watchlist seems like a good idea now.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.