



India spent years managing surplus sugar. It also became the world’s second-largest sugar exporter. Now, the situation has reversed. India has permitted duty-free imports of 10 lakh tonnes of raw sugar. This is the country’s first such move in nearly a decade.
The real problem was a large production miss. The Indian Express reported that gross production was initially estimated at 343.5 lakh tonnes. The latest estimate is only 309 lakh tonnes. Excess rainfall damaged cane in Maharashtra, Karnataka and Gujarat. Disease and pest attacks affected Uttar Pradesh. After ethanol diversion, net output is expected at around 279 lakh tonnes. This is slightly below annual consumption of around 280 lakh tonnes.
India also exported around eight lakh tonnes during the season. Closing stocks are consequently expected at around 41 lakh tonnes. This would be the lowest level since 2016-17. Stock-building by traders and bulk consumers added to the pressure. Some mills also held back supplies. The production shortfall created the squeeze. Speculative buying then made it worse.
How is all this impacting the sugar companies? , We decided to dig in to find out. For the purpose of our study, we considered only profitable sugar companies. We ranked them by Return on Capital Employed (ROCE), a measure of capital efficiency. Stocks with low trading activity were removed. The final list includes five profitable, capital-efficient and sufficiently liquid sugar stocks that could potentially benefit from higher sugar prices.
Join now
#1 Uttam Sugar Mills: Direct Domestic Price Play and Ethanol Expansion
Incorporated in 1993, Uttam Sugar Mills manufactures sugar, industrial alcohol and is engaged in power generation.
Uttam Sugar Mills is a direct play on rising domestic sugar prices. Sugar remains the company’s largest business. Uttam Sugar Mills’ FY26 annual report shows that sugar turnover rose 16% to Rs 1,525.95 crore. Average realisation improved to Rs 4,143 per quintal from Rs 3,984.
Growth is also being built around ethanol. Subsidiary Uttam Distilleries plans to expand its grain-based unit from 40 kilo litres per day (KLPD) to 160 KLPD. The existing plant was running at 95% utilisation when the Rs 110-crore project was approved. A BSE disclosure made by the company set March 2027 as the completion target. The annual report shows project spending under capital work-in-progress. It gives no fresh update on clearances. The company had no international operations or direct exports in FY26.
Near-term earnings were weak. Uttam Sugar Mills’ June-quarter filing shows consolidated revenue fell 3.6% year-on-year (YoY) to Rs 606.37 crore. Profit after tax dropped 91.1% to Rs 1.3 crore.
According to Screener, return on capital employed (ROCE) stands at 11.5% while P/E stands at 13.7 times. The peer P/E stands at 16.8 times suggesting that the stock is trading at reasonable valuations. Higher sugar prices can support realisations. However, cane costs, seasonal swings and timely project delivery will determine the impact on earnings.
Uttam Sugar Mills Financial Performance
| Metric | Value |
| P/E | 13.7x |
| ROCE | 11.5% |
| Q1FY27 revenue growth | Down 3.6% |
| Q1FY27 profit growth | Down 91.1% |
In the past year the share price of Uttam Sugar Mills is up 19.1%.
Uttam Sugar Mills 1 Year Share Price Chart
#2 Balrampur Chini Mills: Margin Leverage Meets Long-Term PLA Diversification
Balrampur Chini Mills is one of the largest integrated sugar companies in India. The allied businesses of the company comprise distillery operations and cogeneration of power.
Balrampur Chini Mills has sizeable earnings leverage to firmer domestic sugar prices. It held 45.67 lakh quintals of sugar at an average cost of Rs 37.19 a kg on June 30. Management said firm prices offered a favourable base for the coming quarters in the Q1 FY27 earnings-call transcript. It also cautioned that supply, while tight, may not be as scarce as market speculation suggests.
Beyond sugar, the Rs 3,080-crore, 80,000-tonne polylactic acid plant is its main growth bet. The Q1 FY27 presentation said operations remain scheduled for the second half of FY27. The transcript puts lactic acid commissioning in October and PLA commissioning in December. About Rs 2,180 crore had been spent by end-July. Saleable output is expected from January. Management is targeting around 40% average utilisation during January-March. The FY26 annual report names Sulzer AG, Alpine Engineering GmbH and Jacobs as global project partners.
Results were mixed. The company’s published Q1 results show consolidated revenue rose 6.1% YoY to Rs 1,636.79 crore. Net profit fell 14.4% to Rs 44.15 crore.
According to Screener its ROCE stands at 9.3% and P/E stands at 38.3 times. The stock is trading quite higher compared to its peer P/E ratio of 16.8 times.
Balrampur offers near-term exposure to higher sugar prices and a longer-term diversification opportunity through PLA. Its next phase will depend on moving the new business from commissioning to stable commercial production.
Balrampur Chini Mills Financial Performance
| Metric | Value |
| P/E | 38.3x |
| ROCE | 9.3% |
| Q1FY27 revenue growth | Up 6.1% |
| Q1FY27 profit growth | Down 14.4% |
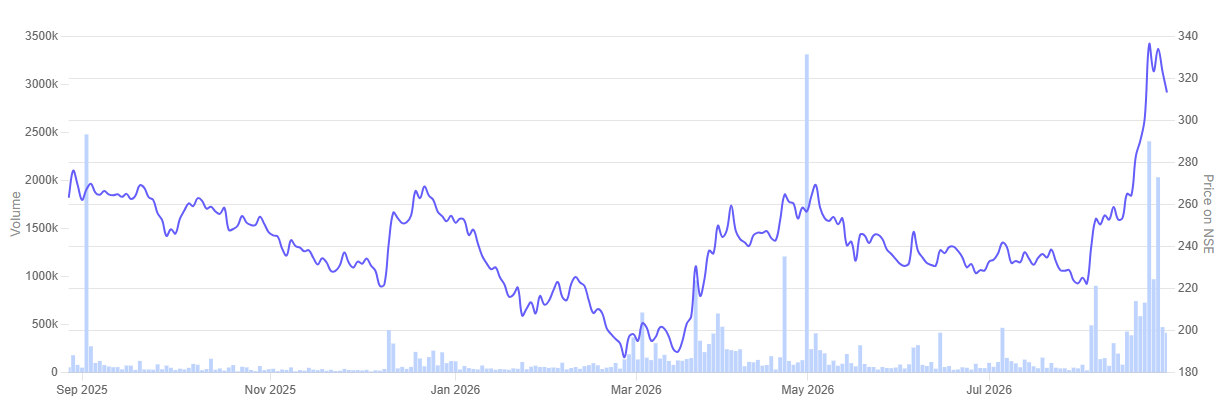
In the past year the share price of Balrampur Chini Mills is up 20.3%.
Balrampur Chini Mills 1 Year Share Price Chart
#3 Triveni Engineering & Industries: Post-Demerger Focus on Core Operations
Triveni Engineering and Industries is an Integrated and diversified conglomerate in areas of sugar, ethanol and engineering. It is located strategically in sugarcane-rich western and central belt of UP. The company is among the Top 3 manufacturers in India for sugar & second highest supplier for ethanol.
Triveni Engineering has direct leverage to rising sugar prices. It carried 3.59 lakh tonnes of sugar at Rs 38.41 a kg at June-end. Refined sugar was selling near Rs 46 a kg when management spoke in July. The spread should support margins. However, higher cane costs will absorb part of the benefit, according to the Q1 FY27 earnings-call transcript.
Growth now depends on better cane availability and a turnaround at Shamli. Triveni expects higher crush and recovery in the 2026-27 sugar season. Capex at Shamli and other units targets better steam efficiency, higher bagasse savings and lower production costs. The NCLT-approved restructuring became effective on May 19. Sir Shadi Lal merged into Triveni, while the power transmission business was demerged.
Water provides its main international exposure. The FY26 annual report says an EXIM Bank-funded project across six Maldives islands was completed. ADB-funded sewage projects in Bangladesh made substantial progress. However, Q1 water revenue fell 21% because of slower work at Prayagraj and Vadodara.
The company’s Q1 investor brief shows consolidated revenue rose 2.1% YoY to Rs 1,581 crore. Profit after tax turned positive at Rs 4 crore from a Rs 7 crore loss. The reported change was 155.1%, though the negative base makes this percentage less meaningful.
The power transmission business was demerged into Triveni Power Transmission during the year. The business was transferred with effect from April 1, 2026. Shareholders received one TPTL share for every three Triveni shares, according to the company’s official filing. Triveni Engineering is now mainly focused on sugar, alcohol and water.
At 24 times earnings, Triveni trades above the peer P/E of 16.8 times. Its ROCE stands at 9%, according to Screener. This premium leaves limited room for disappointment.
The demerger has made Triveni a more focused sugar, alcohol and water business. Its performance must now be judged on these continuing operations.
Triveni Engineering Financial Performance
| Metric | Value |
| P/E | 24x |
| ROCE | 9% |
| Q1FY27 revenue growth | Up 2.1% |
| Q1FY27 profit | Rs 4 crore versus a Rs 7 crore loss |
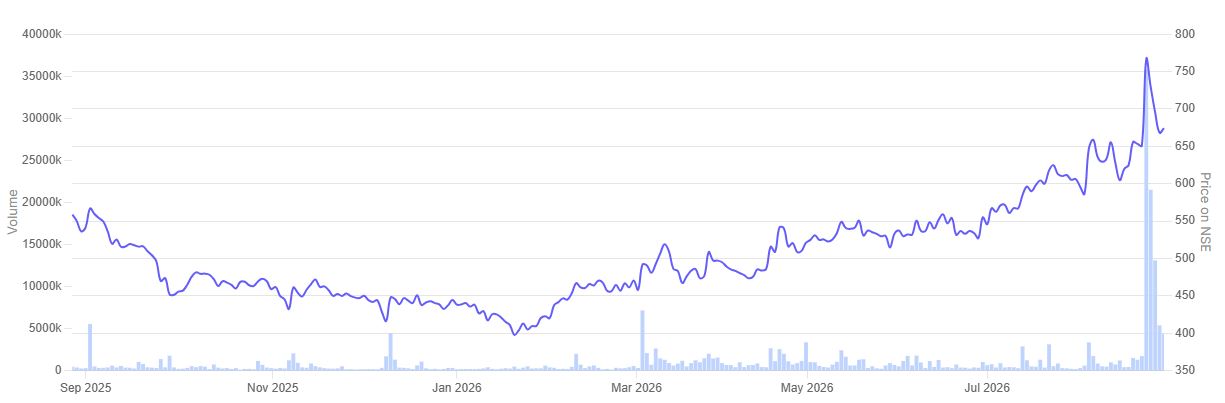
In the past year the share price of Triveni Engineering & Industries is down 32.8%.
Triveni Engineering & Industries 1 Year Share Price Chart
#4 Dalmia Bharat & Sugar Industries: Global Footprint and Biogas Projects
Dalmia Bharat Sugar & Industries is mainly engaged in manufacturing of sugar, generation of power, manufacturing of Industrial alcohol and manufacturing of refractory products. The company is among the youngest and largest sugar companies in India. It is the fastest-growing sugar company with its presence in UP and Maharashtra.
Dalmia Bharat Sugar could benefit from firmer domestic sugar prices. It held 2.36 lakh tonnes of sugar inventory at the end of June. This was valued at Rs 36.9 a kg. Sugar realisation improved from Rs 40.6 a kg in the June quarter to Rs 43-44 in July, according to the company’s Q1 FY27 press release. However, higher cane costs could limit the margin benefit.
The company is also expanding beyond conventional sugar. According to the same company release, its compressed biogas plant at Kolhapur is scheduled to start operations in November 2026. The Ramgarh distillery will be converted into a 100-KLPD dual-feed unit. The project will cost Rs 49 crore. Commissioning is expected by April 2027.
Tanzania is its main overseas growth bet. The approved $132-million project includes a 10,000-hectare cane plantation. It will also have a 70,000-tonne sugar plant and 20 MW of cogeneration capacity. The project plan allows sugar capacity to expand to 150,000 tonnes.
Near-term performance remained weak. Revenue from operations fell 9.9% year-on-year to Rs 848 crore in Q1 FY27. Net profit declined 78.1% to Rs 8.6 crore, the financial release showed.
According to Screener, the stock trades at 19.2 times earnings, above the peer P/E of 16.8 times. ROCE stands at 8.2%.
Dalmia combines sugar-price exposure with an ambitious expansion programme. This creates more growth avenues than a pure sugar play. It also makes timely project execution central to the investment case
Dalmia Bharat Sugar Financial Performance
| Metric | Value |
| P/E | 19.2x |
| ROCE | 8.2% |
| Q1FY27 revenue growth | Down 9.9% |
| Q1FY27 profit growth | Down 78.1% |
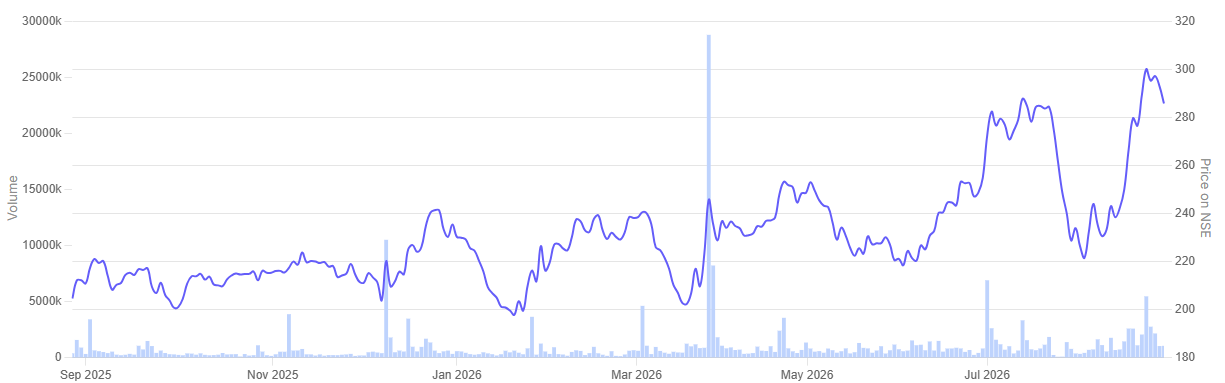
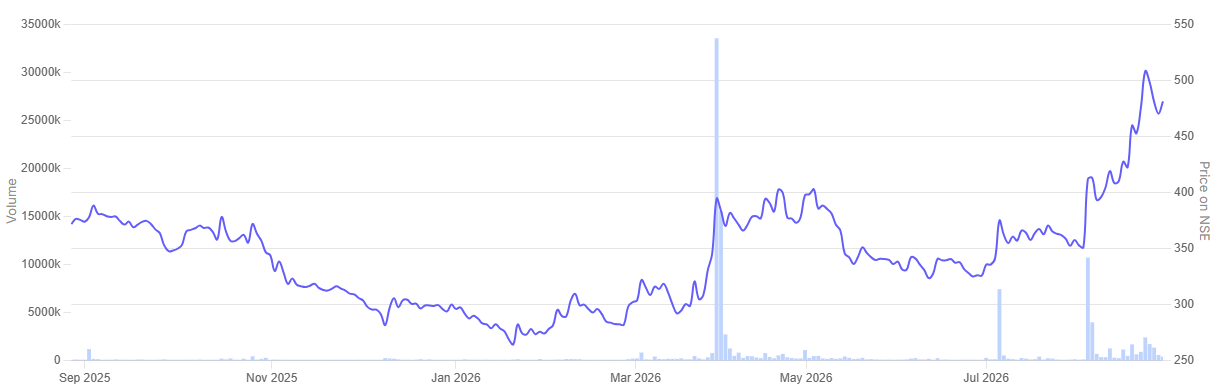
In the past year the share price of Dalmia Bharat Sugar & Industries is up 30.3%.
Dalmia Bharat Sugar & Industries 1 Year Share Price Chart
#5 Avadh Sugar & Energy: Unlocking Value via Existing Distillery Capacity
Incorporated in 2015, Avadh Sugar & Energy manufactures and sells sugar and its by-products, spirits and power.
Avadh Sugar has begun to see the benefit of firmer sugar prices. It held 18.26 lakh quintals of sugar inventory at the end of June. This was valued at Rs 3,790 a quintal. Average sugar realisation rose 2% year-on-year to Rs 4,088 a quintal in Q1 FY27. Sales volume increased 10%, according to the company’s investor presentation.
The company has not announced a large new project or an overseas venture in the presentation. Near-term growth rests on better use of its existing assets. Avadh has 325 KLPD of distillery capacity. Management said a higher ethanol-blending mandate could activate idle capacity without fresh capital expenditure. The company is also shifting towards value-added and refined sugar. It is introducing higher-yield and disease-resistant cane varieties, the presentation showed.
Revenue rose 9% YoY to Rs 779 crore in Q1 FY27. Profit after tax improved to Rs 0.24 crore from a loss of Rs 8.41 crore, according to the financial update.
According to Screener, the stock trades at 24.2 times earnings, against a peer P/E of 16.8 times. ROCE stands at 6.8%. The premium appears demanding given the modest capital efficiency. Higher sugar prices could support earnings.
Avadh has sizeable inventory to sell into a firmer sugar market. However, its earnings cushion remains thin. The company’s recovery will therefore depend on sustained sugar prices and better use of its existing distillery capacity
Avadh Sugar Financial Performance
| Metric | Value |
| P/E | 24.2x |
| ROCE | 6.8% |
| Q1FY27 revenue growth | Up 9% |
| Q1FY27 profit | ₹0.24 crore versus a ₹8.41 crore loss |
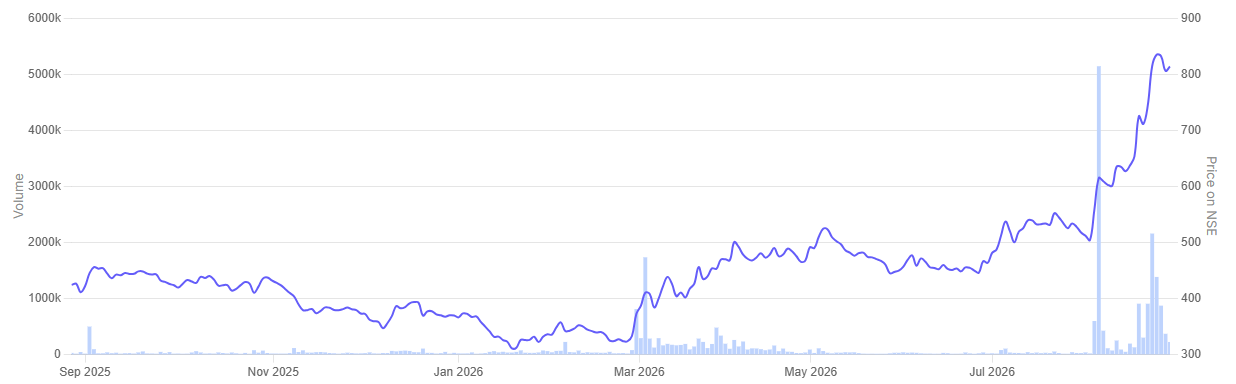
In the past year the share price of Avadh Sugar & Energy is up 92.1%.
Avadh Sugar & Energy 1 Year Share Price Chart
Conclusion
Higher sugar prices can improve realisations for mills carrying inventory. However, the benefit will not be equal across companies. Inventory cost, cane expenses, ethanol exposure and debt will decide how much of the price increase reaches the bottom line.
The five stocks offer different opportunities. Some provide more direct exposure to sugar prices. Others are investing in ethanol, bioenergy, PLA or overseas capacity. These projects can reduce dependence on the sugar cycle, but they also bring execution risk.
Since the sharp price increase came in Q2, its earnings impact is not visible in the June-quarter numbers. The next few quarters will show which companies converted higher prices into stronger margins and cash flows. The screening process identifies profitable, liquid and capital-efficient businesses. It does not remove the risks attached to commodity cycles or company-specific expansion plans.
You can track how these are progressing by adding stocks to your watchlist.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.