



A soap maker needs the right fragrance. A factory needs a way to reuse wastewater. A construction site needs equipment for working safely at heights. And a business needs protection from cyberattacks. Each requirement creates an opportunity for a company that specialises in solving that particular problem.
For investors, the appeal lies in whether these focused businesses can turn customer needs into growing profits and strong returns on capital. Limited borrowing adds another useful check on how that growth is being financed.
To identify potential candidates, we screened SME-listed companies with a market capitalisation above Rs 100 crore. Both their latest return on capital employed (ROCE) and three-year average ROCE had to exceed 15%. Annualised sales and profit growth over three years had to exceed 10%, while the debt-to-equity ratio had to remain below 0.5 times.
The screen also required positive operating cash flow in the last financial year, operating margins above 10% and debtor days below 150. Promoter ownership had to exceed 30%, with stable or rising holdings and no pledged shares. Each company also needed more than 100 shareholders.
From this broader screening exercise, we selected fourteen companies for their specialised businesses. Then, we picked top 4 companies with highest RoCE.
Here is a closer look at the businesses behind those returns and the factors that could shape their next phase of growth.
#1 Apex Ecotech: Scaling Industrial Wastewater Treatment
Incorporated in 2009, Apex Ecotech specializes in turnkey water and wastewater treatment projects.
Apex Ecotech’s industrial wastewater niche is supported by a screening ROCE of 41.4% and debt-to-equity of 0.02 times.
The company designs water recycling and zero liquid discharge systems for factories. Sales compounded at 63% annually over three years as its business expanded. India remains the main growth market. The company’s investor presentation also lists a presence in Bangladesh and Vietnam.
Project execution will determine the next phase of growth. Management said contracts typically take 10–12 months. Its July 17 business update reported an executable order book of approximately Rs 146 crore. This included Rs 25 crore of new Q1FY27 orders.
Revenue Doubles as Order Book Expands to Rs 146 Crore
The expansion has translated into higher earnings. FY26 revenue rose 109.5% year-on-year (YoY) to Rs 148.6 crore. Net profit increased 98.8% to Rs 17 crore, according to the earnings-call transcript. Profits compounded at 69% annually over three years. FY26 operating margin stood at 15%, although higher metal and logistics costs weighed on profitability.
Apex reports financial results half-yearly. Its voluntary Q1FY27 update disclosed invoicing of about Rs 34 crore. These figures were based on unaudited internal accounts.
Funding larger contracts will require attention to cash generation. FY26 operating cash flow was positive at Rs 6.77 crore. Debtor days stood at 41. However, deposits supporting bank guarantees tie up funds as the project pipeline expands.
Promoter ownership remained at 69.29% in March 2026, unchanged from a year earlier. The company has 658 shareholders. Sustaining growth will require timely execution and cost control. Investors must also account for the liquidity and price-volatility risks associated with SME stocks.
Apex Ecotech Financial Performance
| Metric | FY26 |
| Revenue | Rs 148.6 crore |
| Revenue growth | 109.5% YoY |
| Net profit | Rs 17 crore |
| Profit growth | 98.8% YoY |
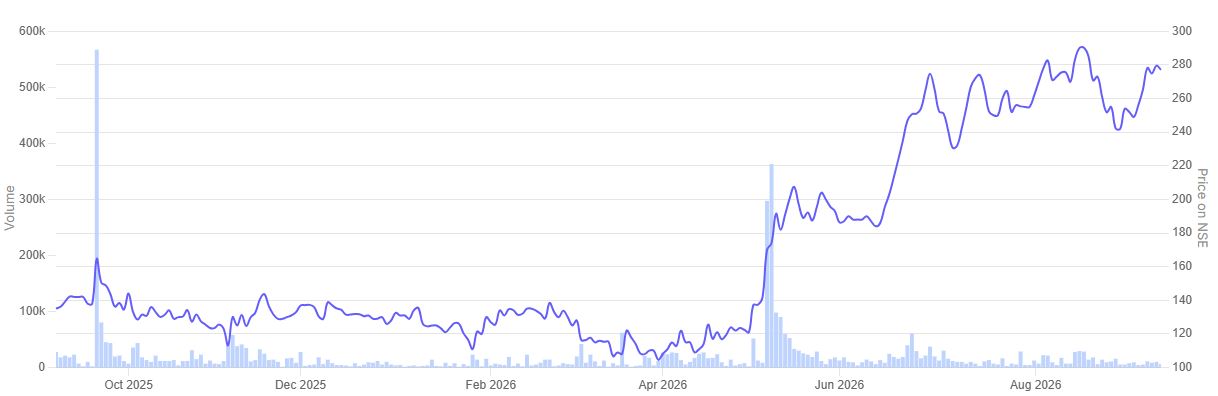
In the past year, the share price of Apex Ecotech rallied 112.9%.
Apex Ecotech 1-Year Share Price Chart
#2 TechD Cybersecurity: High-Margin Recurring Subscriptions
Established in January 2017, TechD Cybersecurity is a cybersecurity firm specializing in safeguarding digital assets for organizations worldwide.
TechD Cybersecurity’s niche spans security audits, threat monitoring and compliance services. It has CERT-In empanelment and a screening ROCE of 40.9%. Borrowings and debt-to-equity were both nil in March 2026, according to its annual report.
Sales compounded at 90% annually over three years. Management reported a 98% renewal rate and plans to sell more services and software to existing customers. Its TechD One platform, launched in May 2026, is intended to expand recurring subscription income.
Subscription Platform and New Capacity Drive 146% Profit CAGR
Expansion includes a 60,000 square feet Ahmedabad centre for security monitoring and research. Management had targeted an August-end or September 2026 start. The annual report still describes it as upcoming. Subsidiaries incorporated in Canada and GIFT City in May support its international expansion plans.
In the May earnings call, management targeted FY27 revenue of Rs 75–80 crore, excluding acquisitions. It reported Rs 43 crore of orders and committed renewals.
TechD reports financial results half-yearly. FY26 revenue rose 73.9% YoY to Rs 51.8 crore. Net profit increased 67.6% to Rs 14 crore, according to the annual report. Its three-year profit CAGR was 146%, while FY26 operating margin stood at 36%.
Cash generation will matter as the business expands. FY26 operating cash flow was positive at Rs 8.5 crore. However, debtor days of 136 show that collections remain an important working-capital consideration.
Promoters held 63.24% in June 2026, unchanged from March. The number of shareholders stood at 1,677. Sustaining growth will depend on converting product launches into paying subscriptions and delivering expansion plans. SME investors also face liquidity and price-volatility risks.
TechD Cybersecurity Financial Performance
| Metric | FY26 |
| Revenue | Rs 51.81 crore |
| Revenue growth | 73.9% YoY |
| Net profit | Rs 14.04 crore |
| Profit growth | 67.6% YoY |
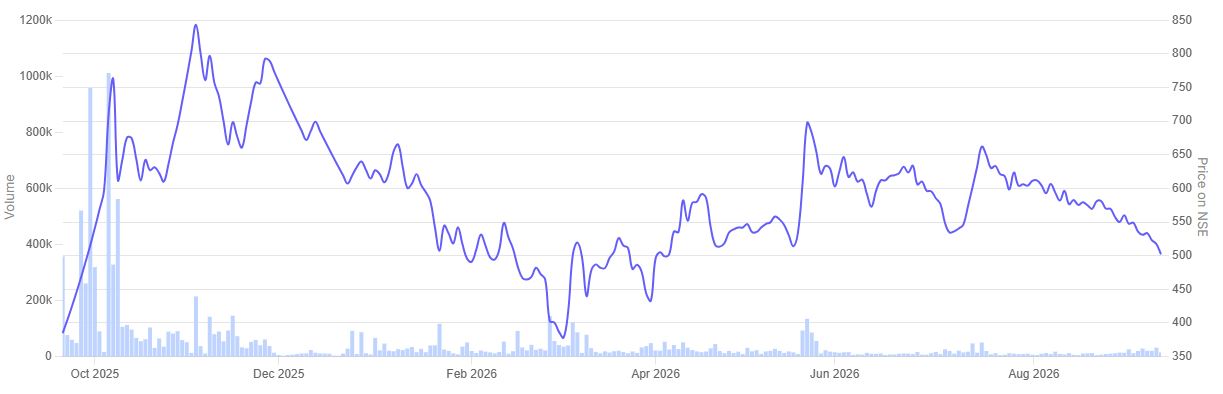
The share price of TechD Cybersecuity since its listing in September is up 38.5%.
TechD Cybersecurity 1-Year Share Price Chart
#3 Msafe Equipments: Expanding Rental Capacity in Construction
Incorporated in 2019, Msafe Equipments is engaged in the manufacturing, sales, and rental of access and height-safety equipment used for safe working at heights.
Msafe Equipments manufactures and rents scaffolding and ladders for construction and industrial maintenance. Its ROCE of 37.2% and March 2026 debt-to-equity ratio of 0.39 times support its selection.
The lower leverage followed fresh equity raised through its IPO. Borrowings increased to Rs 38.5 crore from Rs 32.6 crore a year earlier. However, debt-to-equity fell from 1.27 times as the equity base expanded, according to its annual report.
Sales compounded at 56% annually over three years. Its rental model generates repeat income from the same equipment. Rentals contributed 46% of Q1FY27 revenue, supported by 21 warehouses across India. The screening data put FY26 operating margin at 43%.
Rental Model and Capacity Expansion Boost Cash Flow
Expansion is now the focus. Construction has begun at its Mathura factory, with operations targeted for May 2027. An aluminium formwork initiative targets 500 tonnes of annual capacity from December 2026. These systems provide reusable moulds for concrete construction. Management targets about 50% revenue growth in FY27, according to its September presentation.
FY26 revenue rose 45.1% YoY to Rs 103.50 crore. Net profit increased 72.3% to Rs 22.42 crore. The company’s three-year profit CAGR stood at 89%. Msafe also published Q1FY27 results. Revenue rose about 40% YoY to Rs 31.8 crore. Net profit grew 44.3% to Rs 7.3 crore.
Cash generation needs attention as capacity expands. FY26 operating cash flow fell to Rs 11.53 crore from Rs 14.35 crore. Inventory growth absorbed funds. Debtor days stood at 84.
Promoter ownership rose to 73.23% in June 2026 from 72.84% in March. No promoter shares were pledged. The company has 1,014 shareholders.
Growth will depend on commissioning capacity and keeping rental equipment deployed. Investors should also account for the liquidity and price-volatility risks associated with SME stocks.
Msafe Equipments Financial Performance
| Metric | FY26 |
| Revenue | Rs 103.5 crore |
| Revenue growth | 45.1% YoY |
| Net profit | Rs 22.4 crore |
| Profit growth | 72.3% YoY |
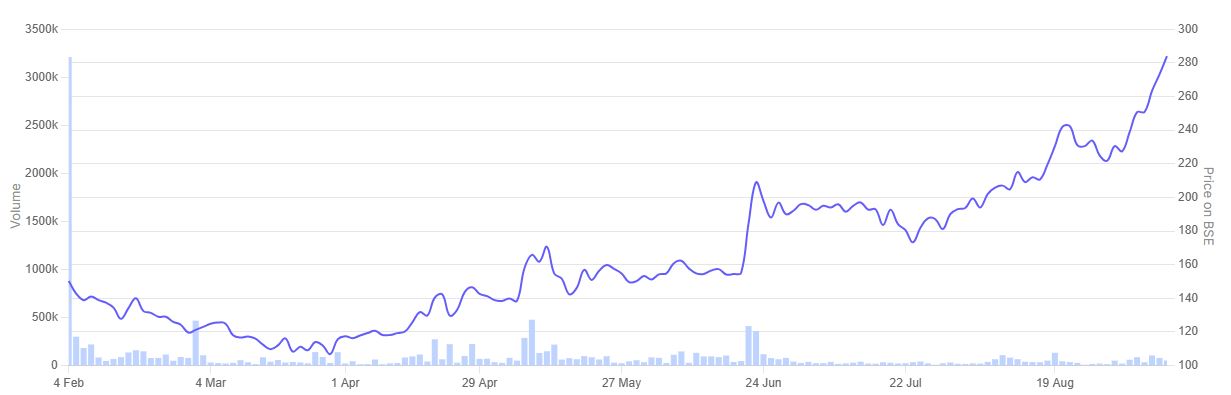
In the past year, the share price of Msafe Equipments is up 45%.
Msafe Equipments 1-Year Share Price Chart
#4 Sacheerome: Quadrupling Capacity to Serve Global Markets
Incorporated in 2009, Sacheerome is in the business of designing & manufacturing fragrance and flavours.
Sacheerome supplies fragrances and flavours used in soaps, cosmetics, packaged foods and beverages. Its screening ROCE of 35.7% supports its selection. Borrowings were nil in March 2026, with debt-to-equity at zero, according to its investor presentation.
The business relies on customised formulations and application testing. Sales compounded at 29% annually over three years. Existing customers contributed Rs 31.24 crore of the Rs 44.85 crore increase in FY26 revenue. This highlights the importance of repeat business.
Rs 184-Crore Factory Expansion Underpins Rs 200-Crore Revenue Target
Capacity expansion is the next test. The Rs 184 crore Yamuna Expressway Industrial Development Authority (YEIDA) factory in Uttar Pradesh is intended to roughly quadruple production capacity. In its June earnings call, management targeted an August 2026 start following vendor delays. The supplied documents do not confirm commissioning.
Funding could change its debt profile. Management indicated that around Rs 60 crore of borrowing would support the project, drawn as required. It had invested Rs 76.59 crore by March 2026 through IPO proceeds and internal accruals.
International expansion remains a smaller part of the business. FY26 exports stood at Rs 9.4 crore, contributing 6.2% of sales. Dedicated research and sales teams are targeting Middle Eastern and Gulf markets.
Sacheerome reports results half-yearly. FY26 revenue rose 41.7% YoY to Rs 152.4 crore. Net profit increased 78% to Rs 28.4 crore. Its three-year profit CAGR stood at 68%. FY26 operating margin was 24% on the screening data. Operating cash flow reached Rs 26.15 crore, according to the annual report. Debtor days improved to 47 from 52 a year earlier.
Promoters held 71.54% in March 2026, unchanged from June 2025. The company has 1,158 shareholders.
Management targets FY27 revenue of Rs 200 crore. Delivering that growth will depend on commissioning the factory and securing orders for the expanded capacity. Future borrowing also warrants attention. SME investors face liquidity and price-volatility risks.
Sacheerome Financial Performance
| Metric | FY26 |
| Revenue | Rs 152.39 crore |
| Revenue growth | 41.7% YoY |
| Net profit | Rs 28.44 crore |
| Profit growth | 78% YoY |
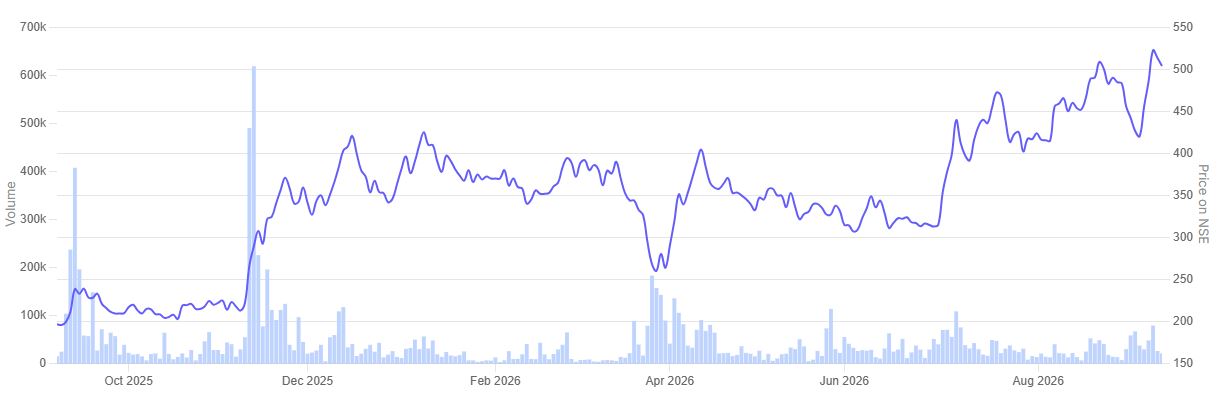
In the past year, the share price of Sacheerome rallied 154.3%.
Sacheeromme 1-Year Share Price Chart
Conclusion
These four SMEs combine specialised businesses with strong returns on capital and relatively low debt. Their growth highlights the opportunities in serving specific needs across industry and everyday consumption.
The next phase will test those strengths. New factories, larger rental fleets and software products require capital. Timely execution and customer demand will determine whether that spending translates into higher earnings. Debt levels and cash generation will need watching as expansion gathers pace.
For investors, valuations deserve as much attention as profit growth. SME shares also carry liquidity risks and can see sharp price swings. Sustained returns will depend on these companies turning their expansion plans into steady operating cash flow.
Four Niche SMEs: Growth and Operating Performance
| Metric | Apex Ecotech | TechD Cybersecurity | Msafe Equipments | Sacheerome |
| 3-year Sales CAGR | 63% | 90% | 56% | 29% |
| 3-year Profit CAGR | 69% | 146% | 89% | 68% |
| FY26 operating margin | 15% | 36% | 43% | 24% |
| FY26 debtor days | 41 | 136 | 84 | 47 |
| FY26 operating cash flow (Rs crore) | 6.77 | 8.55 | 11.53 | 26.15 |
You can track how these are progressing by adding stocks to your watchlist.
Disclaimer
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.