



India’s power infrastructure story is creating an opportunity one step below transformer makers. As renewable capacity, data centres, artificial intelligence, and electric vehicles increase electricity demand, pressure is shifting to the transmission and distribution network that must carry that power.
That is where Continuously Transposed Conductor (CTC) becomes relevant. Vidya Wire’s management estimates India’s CTC demand at around 30,000 to 40,000 tonnes and is growing as transformer manufacturing expands. In fact, India’s transformer capacity is expected to rise from 110 GVA to nearly 300 GVA by FY28E.
The opportunity is not limited to India. Grid modernisation across Europe, North America, the Middle East and Southeast Asia is driving demand for transformers as countries replace ageing networks and strengthen electricity infrastructure. For CTC players, however, the opportunity is not simply about selling more copper.
The Copper Pass-Through Advantage: De-risking Margin Volatility
Copper accounts for 85% to 90% of CTC costs and is largely passed through to customers. The real entry barrier lies in precision manufacturing, quality consistency and utility approvals. It can take 5-7 years for a new entrant to move from medium-voltage distribution to high-voltage transmission and eventually HVDC applications.
This creates a relatively concentrated opportunity within a much larger power infrastructure cycle. India has around ₹9 lakh crore of transmission grid capex planned between FY23 and FY32. As transformer manufacturers expand capacity to meet this demand, CTC suppliers could be positioned to capture the next leg of the power transmission cycle.
Against this backdrop, this article examines three CTC manufacturers that could benefit from the growing demand for transformers.
#1 KSH International: Scaling capacity with strong CTC exposure
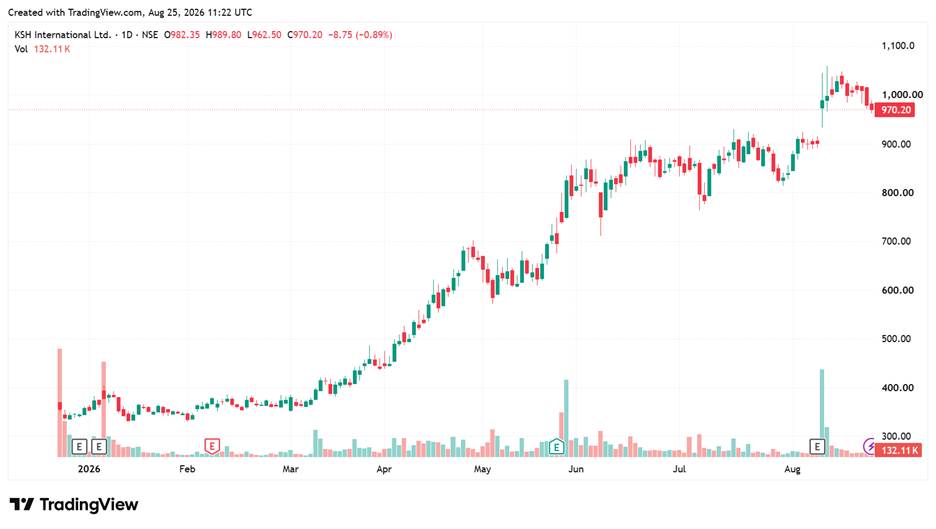
KSH International manufactures magnet winding wires, critical components of coils used in electric machines ranging from large power transformers to AC compressors. It is India’s leading manufacturer of specialised winding wires and the largest exporter. Specialised winding wires are the largest business, accounting for 75.3% of FY26 revenue.
Within Specialised Winding Wires, its key product is Continuously Transposed Conductors (CTC). CTC is used in large power transformers for transmission and distribution. Other products include special rectangular magnet wire for electric vehicles, paper-insulated rectangular copper/aluminum wire, and standard winding wire (24.7% of revenue).
Pass-Through Cost Model Insulates Margins from Metal Price Swings
The company manufactures products only after receiving a purchase order, which protects it from volatility in raw materials and exchange rates. Copper metal costs are passed directly through to customers. This means absolute EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortisation) per ton remains structurally stable.
Q1FY27 Financials: 108% Topline Surge Drives Net Profit to ₹42.2 Crore
In Q1FY27, KSH International experienced strong financial growth driven by ongoing demand in the transmission and distribution sector and high-value product contributions. Specialised Wire revenue grew by 113% year-on-year in Q1FY27. Revenue grew 108.4% year-on-year to ₹1,164.2 crore, driven by 30% higher sales volume.
EBITDA increased 85.1% to ₹74.4 crore, while margins fell 81 bps to 6.4%. Net Profit rose 85.9% to ₹42.2 crore. EBITDA per ton also expanded by 41.6% to ₹93,325. Net average working capital days also improved by 11 days to 60 days. Management expects a 26% volume growth, with sustainable EBITDA of ₹75,000 per tonne in FY27.
Supa Plant Scaling to 59,045 MT with Long-Term Hitachi Offtake Tied Up
KSH’s total installed capacity stood at 43,445 metric tons (MT) as of 30 June 2026. The company is adding a 30,000 MT capacity at Supa in Maharashtra. Of this, 14,400 MT is complete (included in 43,445 MT), and the next phase of capacity addition is on track to come online in Q2FY27. The remaining capacity is expected to come online by March 2027.
KSH expects to exit FY27 with a total installed capacity of 59,045 MT. In addition, it has existing space at the Supa plant to add another 10,000 to 12,000 MT of capacity. Management plans to evaluate this expansion once overall capacity utilisation reaches approximately 85%. Current capacity utilisation is 73.5%.
Beyond direct power transformers, KSH is seeing strong demand in backup power systems, specifically alternators for diesel generator sets used in data centres. KSH has signed a long-term supply framework agreement with Hitachi Energy Global to service their Indian and select international plants.
#2 Vidya Wires: Moving up the CTC value chain
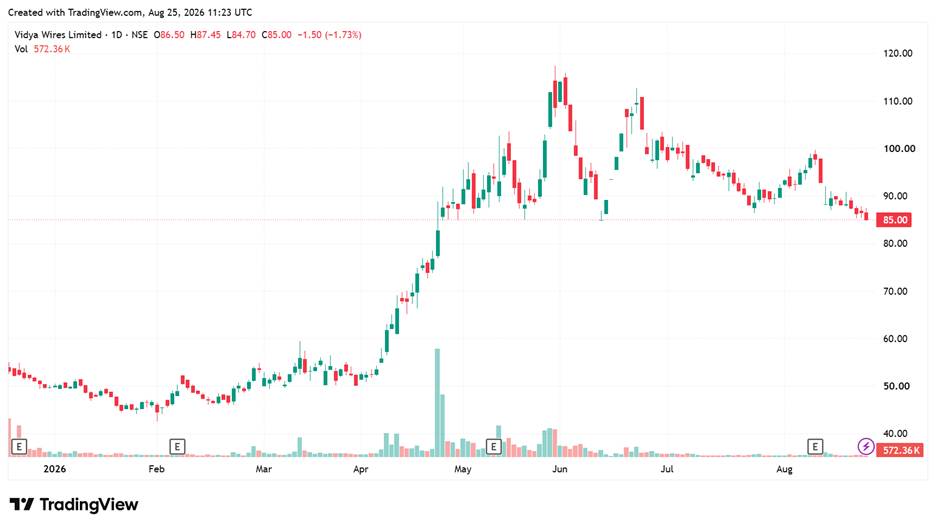
Vidya Wires specialises in manufacturing insulated copper and aluminium conductors. The company has moved up the value chain by introducing several specialised product categories. This includes CTC, which is a key component of Vidya Wires’ transition into higher-margin, specialised product lines.
Margin Expansion: Dedicated 3,000 MTPA CTC Rollout
The company is setting up a dedicated capacity of 3,000 MT per annum (MTPA) for CTC. This is expected to be rolled out in Phase 1. Management has indicated they have sufficient land and resources to expand this capacity further in the future based on incoming demand.
CTC wires carry better profit margins compared to the company’s traditional offerings, such as general enamelled copper wires or paper-covered copper conductors. Along with other new specialised products (like PV ribbons), the introduction of CTC is expected to drive overall EBITDA per metric ton and consolidate higher profit margins for the company.
Capacity Roadmap: Doubling Output to 36,000 MTPA by December 2026
Additionally, Vidya Wires is expanding its total manufacturing capacity from approximately 19,000 metric tons per annum (MTPA) to 36,000 MTPA. Of this, approximately 6,000 to 7,000 MTPA has already been installed. The company expects the entire expansion to be fully operational before December 2026.
As the newly added facility stabilises and undergoes customer qualification audits, management expects to achieve 50% to 60% capacity utilisation. FY28 will be the first full year of consolidated operations at the expanded 36,000 MTPA scale, with management targeting optimum capacity utilisation of 80%.
Export Strategy: Targeting 25% Global Share with Faster Working Capital Cycles
While domestic infrastructure currently represents the highest demand (88% of total volume), Vidya Wires has expanded its international marketing team to increase exports. The company’s long-term target is to achieve a balanced mix of 75% domestic sales and 25% exports. The company also plans to reduce its working capital cycle from 60 days to 50-52 days.
Q1FY27 Financials: Net Profit Jumps 41% to ₹17.1 Cr as Capacity Scales Up
Financially, revenue grew 33.5% year on year to ₹549.7 crore in Q1FY27. EBITDA grew by 26.1% to ₹25.2 crore while margins stood at 4.6%. Net profit surged 41.4% to ₹17.1 crore. The growth was driven by the phased ramp-up of recently added capacity.
#3 Apar Industries: Premium conductors driving growth and margins
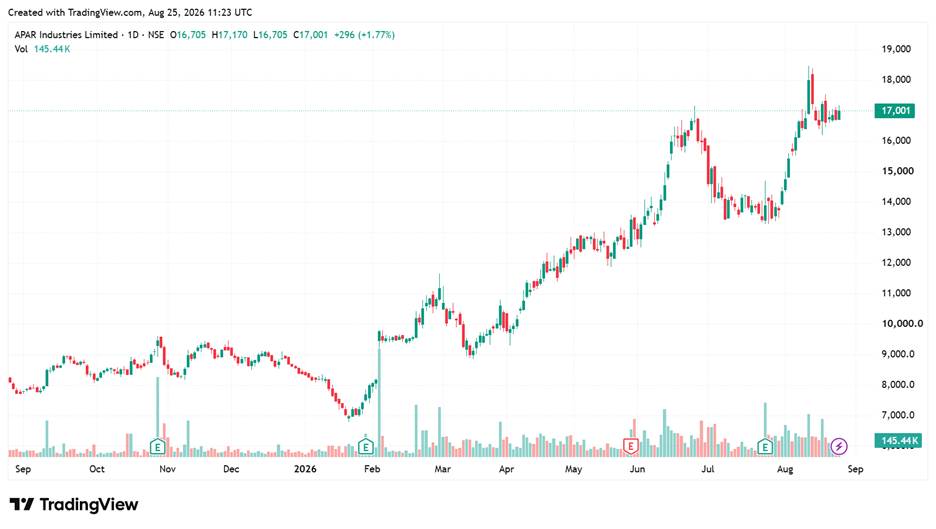
APAR Industries operates in the power transmission, distribution, and infrastructure sectors. The company’s business has three divisions. The Conductor Division focuses on power transmission infrastructure, producing both conventional and high-value premium conductors.
The division’s products include conventional conductors and premium conductors, including CTC. During Q1FY27, APAR witnessed strong growth across its entire copper product range. Alongside the growing demand for CTC, APAR expanded supplies across its broader copper portfolio, including key deliveries of copper products to the railways and heavy-duty busbars.
Premium Conductors: Share Climbs to 50.3% as EBITDA per MT Expands
This increase in copper products reflects a significant, multi-year demand from worldwide grid infrastructure and transformer manufacturing. The share of premium products (including CTC) in the division’s total revenue increased to 50.3%, up from 43.7% in Q1 FY26.
This also drove the unit’s profitability, with EBITDA per MT rising 22.3% to ₹53,418. In the revenue mix, conductors accounted for 48.5% in Q1FY27, followed by cables (26.7%) and Oils (24.8%). The domestic market contributed 72.5% of the revenue, and the rest came from exports (27.5%).
Order Book: ₹10,190 Cr Backlog Anchored by US and European Utilities
The APAR Conductor Division had a pending order book of ₹10,190 crore. Of this, 56.8% are export orders. This backlog includes two large multi-year utility orders totalling over ₹2,800 crore from electric utilities in the US and Europe. Deliveries are expected over the next 4 years.
Management said a large part of the remaining backlog is executable within about one year, with a few orders potentially spilling into the following year.
Financials: Q1 Net Profit Jumps 78% on Domestic Grid Demand
From a consolidated perspective, revenue grew 29.1% year-on-year to ₹6,591 crore, supported by a 36.9% increase in domestic revenue. EBITDA (post-forex) increased 62.7% to ₹814 crore, while margins expanded 260 bps to 12.4%. Consequently, net profit rose 77.7% to ₹467 crore.
Evaluating Capital Efficiency: Premium Valuations vs Industry Medians
Apar Industries stands out with strong Return on Capital Employed (ROCE) and Return on Equity (ROE), followed by KSH and Vidya Wires. On valuations, following a recent sharp re-rating, both KSH and Vidya Wires are trading at a premium relative to the industry. Apar Industries is also trading at a premium to both the industry and 5-year historical median.
| Peer Comparison (X) | |||||
| Price-to-Earnings Multiple | Return Ratios | ||||
| Company | Company | Industry Median | 5Y Median | ROCE (%) | ROE (%) |
| KSH | 42.3 | 28.1 | NA | 21.5 | 20.1 |
| Vidya Wires | 36.9 | 16.2 | NA | 20.7 | 17.8 |
| Apar Industries | 59.0 | 26.6 | 38.6 | 31.1 | 20.2 |
The CTC opportunity is attractive, but the three companies are at different stages of capturing it. KSH has the strongest existing exposure, with specialised winding wires contributing 75.3% of FY26 revenue and capacity expected to reach 59,045 MT.
Vidya Wires is earlier in its CTC journey, with 3,000 MT of dedicated capacity being added alongside its broader capacity expansion. APAR, meanwhile, brings scale, with premium products already contributing 50.3% of conductor revenue and a ₹10,190 crore order book.
Meanwhile, it would be beneficial to keep these on your watchlist.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.