



A battlefield with 1,000 drones in the air at the same time is no longer just a futuristic scenario. Modern warfare is moving towards large drone swarms, with hundreds or even thousands of unmanned systems operating together. For example, each infantry unit in China is reportedly equipped with around 1,000 drones.
To counter so many drones, forces could need thousands of interceptor drones capable of detecting and destroying hostile drones in mid-air. This is creating a new procurement opportunity for Indian drone manufacturers. The government has planned drone acquisitions worth ₹20,000 crore through the Fast Track Procurement route.
Decentralising Defence: ₹52,000 Crore Approvals and Fast Track Procurement
The procurement process is also becoming more decentralised. The Ministry of Defence has nearly doubled the financial powers available to field commanders. Now, local command centres can directly purchase qualifying Unmanned Aerial Vehicle systems costing up to ₹5 crore per unit.
This could reduce the time taken for traditional procurement and bring orders closer to the field. The opportunity extends well beyond small tactical drones. The Defence Acquisition Council has approved capital acquisitions worth ₹52,000 crore for drones, including jet-powered kamikaze systems.
Before that, in 2025, India cleared two defence procurement packages totalling ₹1.46 lakh crore, including ₹67,000 crore in August and ₹79,000 crore in December. Unmanned and advanced drone systems were integrated as part of these budgets. Thus, the direction of spending is becoming clear.
The opportunity is shifting from basic tactical UAVs toward surveillance, interception, loitering munitions, and autonomous platforms across land, air, and sea. This creates a wider opportunity set than the conventional drone market. Here are three Indian drone companies positioned to benefit from this shift.
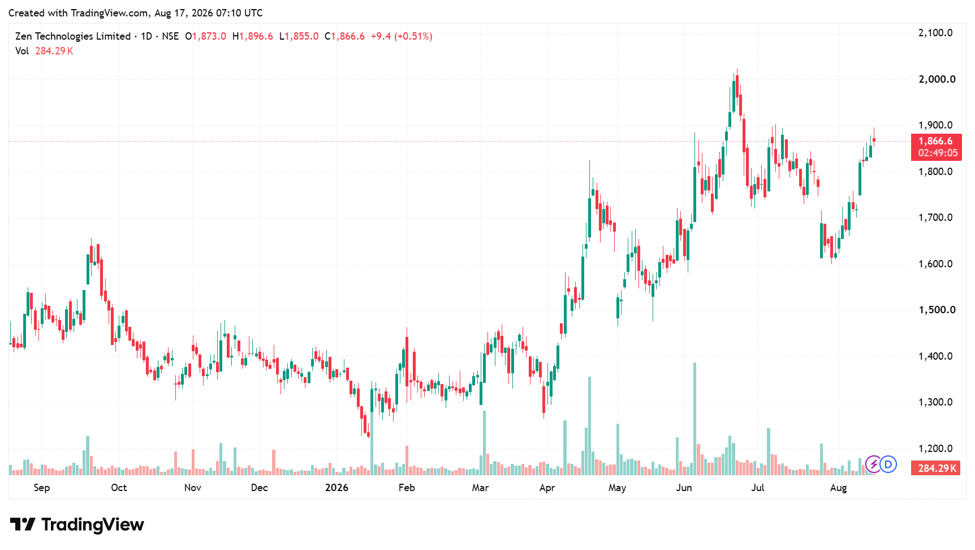
#1 Zen Technologies: The Counter-Drone Play
Zen Technologies has transformed from a provider of advanced military training simulators to a leading drone and counter-drone solution provider. The company serves the Indian Armed Forces, state police forces, and friendly foreign countries. Its portfolio is divided into three main pillars: training systems, drone/counter-drone solutions, and operational equipment.
The company’s main legacy is in simulation. Zen’s training solutions are critical for lower training timelines. For instance, Zen reduced the Agniveer 100-week training program to just 30 weeks by integrating its simulators. Zen is collaborating with global OEMs to cement its position in the air simulator domain.
The company has successfully built a robust counter-drone ecosystem. Zen’s counter-drone systems are battle-tested. The Indian Government recently awarded the company contracts worth approximately ₹800 crore. Zen has built a high-speed interceptor drone that can destroy enemy drones at a range of 20 km.
Join now
Decoding the Q1FY27 Margin Compression and Revenue Dip
The company’s recent results were temporarily impacted due to the early-stage execution cycle of the order book. Revenue declined to ₹141.6 crore in Q1FY27 from ₹158.2 crore in Q1FY26. Reported EBITDA (earnings before interest, tax, depreciation and amortisation) fell 33.9% to ₹57.9 crore as margins shrank 1,380 bps to 40.9%. Net profit declined 27.8% to ₹34.5 crore.
Zen Technologies is completely debt-free. As of June 30, 2026, the company has strong liquidity, with cash and bank balances of ₹1,217 crore. However, due to supplier advances and inventory buildup to help expedite order book fulfilment during FY27, the company’s working capital cycle is currently stretched to 257 days.
Order Book Dynamics: Inside the ₹1,239 Crore Pipeline
As of 30 June, 2026, the order book stood at ₹1,239 crore, comprising ₹920.6 crore in equipment and ₹318.4 crore of Annual Maintenance Contracts. The domestic order book is ₹1,153.8 crore, with ₹85.3 crore in export orders. Management expects to close FY27 with an order book of about ₹2,500 crore.
The Global Blueprint: Charting the Path to a ₹4,000 Crore Milestone
Despite slowing financial growth, Zen has maintained its revenue target of ₹4,000 crore for FY27 and FY28 combined. Simulators are expected to generate ₹2,000 crore of that total. Zen is aggressively targeting high-compliance, high-value markets in North America and the European Union.
In the US alone, Zen’s addressable market is estimated to be $10 billion, and the company aims to achieve a modest $100 million in sales by year 3. While the company is undergoing validation in the US market, it aims to expand there using local partners first.
#2 Ideaforge Technology: The Indigenous Drone Play
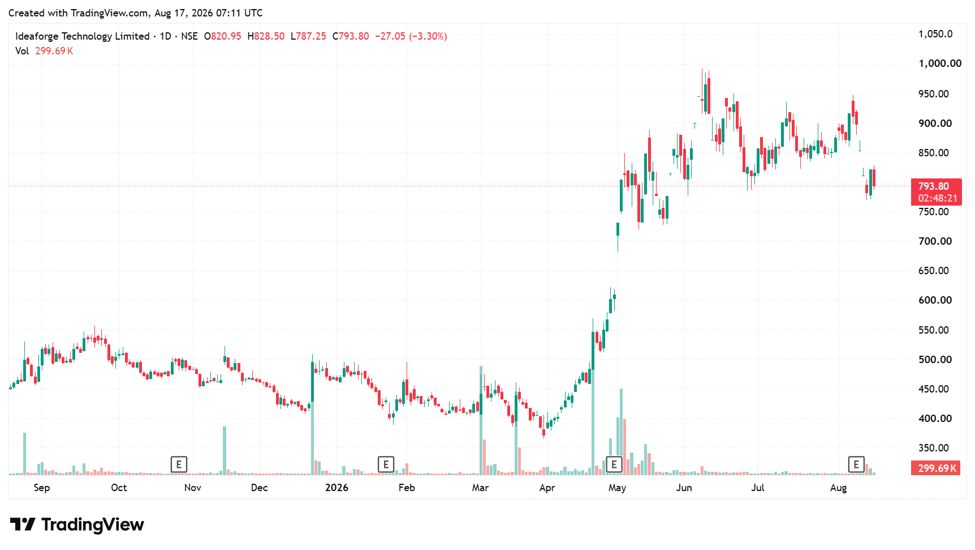
IdeaForge Technology is a leading player in the drone industry, specialised in dual-use (defence and civil). It is considered a pioneer of the Indian drone industry and is ranked #3 globally in the dual-use drones category.
The defence sector is the primary driver of growth and revenue. During Q1FY27, defence accounted for 60% of the revenue and the civil business (40%). The company’s consolidated revenue increased by 436.7% year-on-year to ₹68.6 crore in Q1FY27.
EBITDA turned positive at ₹4.3 crore, up from a loss of ₹15.1 crore in Q1FY26, as margins turned positive (6.2%). Consequently, net loss narrowed to ₹2.6 crore, down from a ₹23.6 crore loss in Q1FY26. This turnaround happened as the Indian drone market saw a sharp rebound in FY26.
Why Executing the ₹256 Crore Order Book is Driving Positive Margins
The proprietary, long-term technical bets and investments IdeaForge made over previous years materialised into an order book. The company prioritised converting part of these orders into revenue. In Q1FY27, IdeaForge executed over 20% of this opening order book. This brought in revenue of ₹68.6 crore and pushed EBITDA back into positive territory.
As of 30 June, 2026, the order book of ₹256.8 crore is heavily skewed toward defence contracts. The company intends to execute and deliver the remainder of this order book by Q3FY27. Operational command-level procurements are expected to fructify and accelerate in Q3 and Q4 FY27. It has also bid for a request for proposal worth ₹20,000 crore to purchase drones.
The Strategic Push for US ‘Blue UAS’ Certification
Expanding outside India could be a major growth pillar for IdeaForge. The company is working with its US partner to operationalise its signed joint venture. The company is applying for Blue UAS certification, a prerequisite for winning defence and federal contracts in the US.
Management noted that major US defence programs, such as the Drone Dominance Gauntlet program, offer significant opportunities. Management highlighted approximately US$3 crore in live participation programs. It is also exploring partnership opportunities in Europe and the Middle East region.
Kamikaze Drones and Swarm Tech: The Next Frontier in ideaForge’s Arsenal
On the expansion side, ideaForge is building variants of its quadcopter platforms to serve as one-way attack (kamikaze) systems and fuel-hybrid platforms. It is also developing Air-Launched Effects (deploying secondary carrier munitions mid-flight) and multi-UAV swarming capabilities. These variants are intended to bid on major programs of the Ministry of Defence.
#3 Astra Microwave Products: The Radar & Electronic Warfare Play
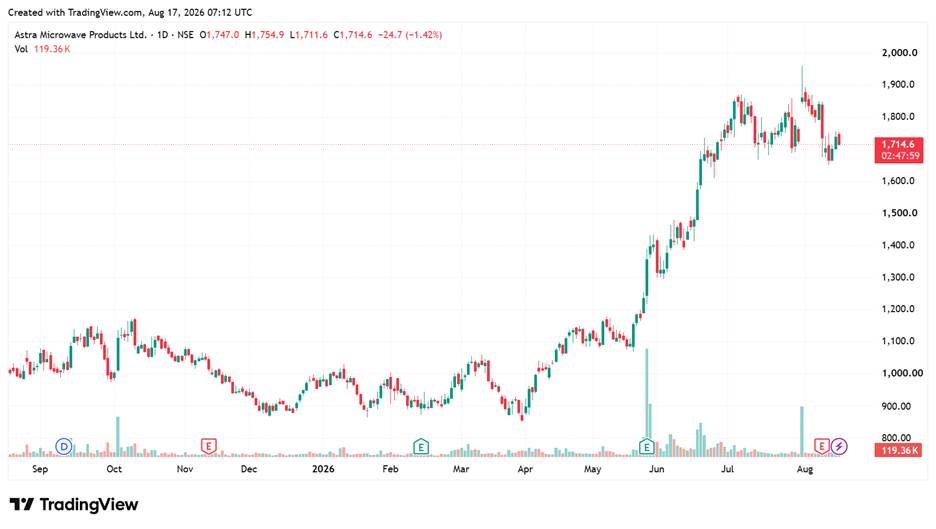
Astra Microwave Products has a robust and expanding footprint in both the aerospace and drone sectors. The drone segment is a high-potential, IP-driven product for the company. Astra does not attempt to manufacture every component of a counter-UAV system. It focuses on its core Research & Development competencies and leverages partner integrations.
Neutralising Aerial Threats: The Push into Anti-Drone & EM Wall Tech
It is focusing on Anti-drone systems, Electronic Warfare, and satellites. Astra has developed several distinct products to neutralise aerial threats and support UAV operations. In July 2026, Astra conducted successful technology demonstrations in Jalandhar for a proprietary Vehicle-Mounted Anti-Drone System.
Another product is the Electromagnetic Wall (EM Wall). It is designed as a complete mobile program with both soft-kill and hard-kill defensive actions. This system is currently an initial-based, first-of-its-kind version that Astra expects to fully customise for specific end-user requirements in the coming months.
The company is preparing to deliver a unique, drone-mounted electronic intelligence payload around Diwali. Along with its anti-drone package, Astra is also preparing to complete at least two of its proprietary radars by Diwali. In addition, Astra designs and supplies the RF and microwave subsystems needed to track drones and UAVs
Notably, management has not projected revenue from the above products in guidance or the current order book. This is because these products are in the customisation and trial phases. Any orders that translate into contracts will directly add to revenue.
Q1Financials: Navigating Temporary Margin Contractions
Financially, consolidated revenue fell 10.7% year-on-year to ₹176 crore. EBITDA declined 13.7% to ₹33 crore with margins at 18.8%. Net profit declined 24.4% to ₹12 crore. Management said the quarter’s performance was in line with internal expectations. Temporary delays in customer approvals and other delays are expected to normalise in the coming quarters.
Multi-Year Visibility: A ₹2,200 Crore HAL Order Book Surge
Astra’s standalone order book stood at ₹2,156 crore. In late July 2026, Astra secured its largest contract worth ₹2,205 crore from Hindustan Aeronautics Limited for the Active Antenna Array Unit subsystem for the indigenous Uttam radar. The order book provides multi-year revenue visibility. The Astra Rafael Comsys (ARC) JV also holds an order book of ₹836 crore.
Looking ahead, Astra expects revenue to grow 15-20% to approximately ₹1,350 crore in FY27 and a further 15-20% to ₹1,600 crore in FY28. From FY29, revenue is expected to be significantly higher as the execution of large production orders for both the Uttam radar and QRSAM starts.
Decoding the Valuation Premium: High Growth at a Steep Price
Astra Microwave has a higher return on capital employed (ROCE) and return on equity (ROE) due to faster growth later in the cycle compared to Zen Technologies.
From a valuation perspective, Zen Technologies and Astra Microwave are trading at a significant premium not only to the industry median but also to their 3-year historical median. IdeaForge is still loss-making on a full-year basis, and thus its valuation is significantly higher due to a lower denominator.
| Peer Comparison (X) | ||||
| Company | Price-to-Earnings Multiple | Return Ratios | ||
| Company | 3Y Median | ROCE (%) | ROE (%) | |
| Zen Technologies | 92.7 | 64.2 | 16.2 | 10.7 |
| Astra Microwave | 86.0 | 63.7 | 20.2 | 16.0 |
| IdeaForge | 1002.0 | 107.7 | NA | NA |
| Industry | 70.0 | 14.5 | 11.7 | |
All three companies offer different ways to play India’s drone transition.
Zen Technologies is already monetising counter-drone demand, with around ₹800 crore of recent contracts and a ₹1,239 crore order book. IdeaForge gives exposure to surveillance, swarming and kamikaze drones, while Astra Microwave is building the radar and electronic warfare layer.
Therefore, the opportunity is not just about a single drone, but now extends across the value chain and across variants. That said, you could keep these names on your watchlist to track execution.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely used, and accepted source of information only when the data was unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.