



For years, stationery has remained a largely unorganized and fragmented market, with local brands competing alongside a handful of established names. That is gradually changing. Consumers are becoming more conscious about quality, product variety, and branding. Organized players are expanding their reach through modern retail and e-commerce.
This change is creating a larger opportunity for branded stationery companies. According to the Technopak industry report, the Indian stationery and art materials market, estimated at ₹38,500 crore in FY23, is expected to grow at around 13% CAGR to ₹71,600 crore by FY28. Within this expanding market, the movement from unorganized to organized players could become an important growth driver.
The share of branded players is also expected to expand to 43% by FY28, up from 36% in FY23. Against this backdrop, this article examines India’s three leading and largest listed stationery players.
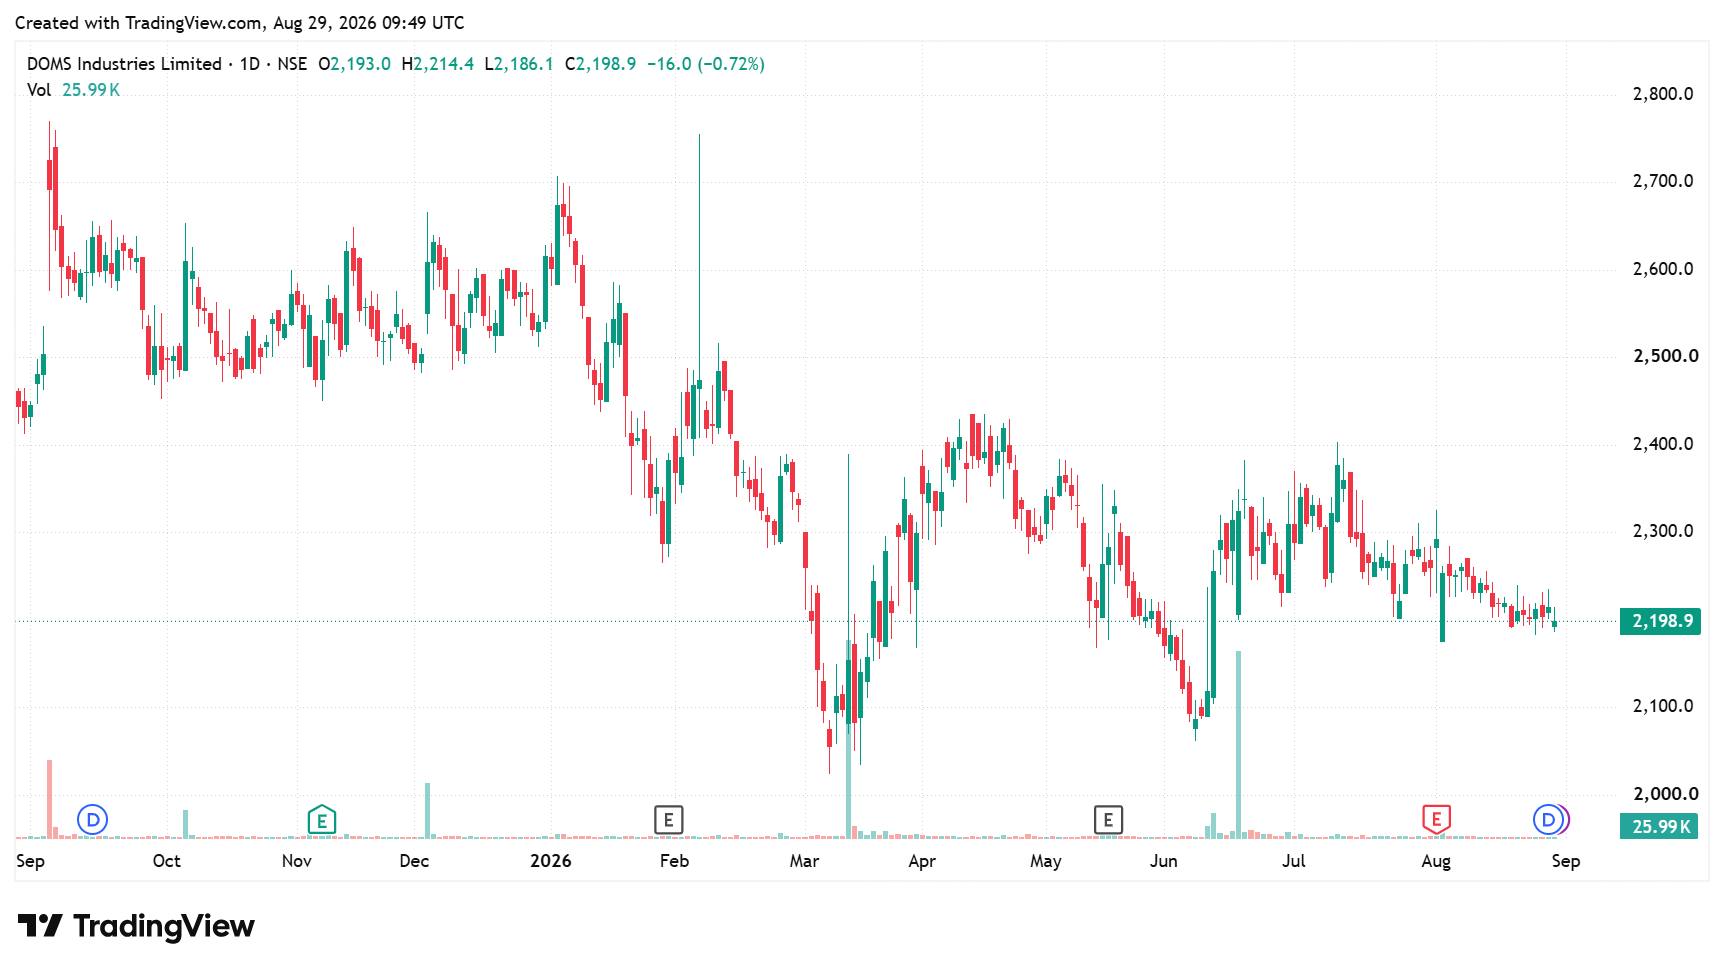
#1 DOMS Industries: Scaling beyond pencils into categories
DOMS Industries designs, manufactures, and distributes a wide range of stationery and art materials. Over the years, the company has scaled from a prominent pencil manufacturer into a multi-category consumer platform.
Join now
DOMS operates across 9 distinct product categories with a portfolio of over 4,800 Stock Keeping Units (SKUs). This includes Scholastic Stationery (Pencils, erasers), Scholastic Art (watercolors, sketch pens), Paper Stationery, Kits & Combos, and Office Supplies. Its integrated end-to-end manufacturing setup is a key business strength.
Why End-to-End Manufacturing Drives DOMS’ Scalability
The company manufactures nearly all key components in-house. For pencils, this spans from wood processing to finished lead pencils. For writing instruments, it includes manufacturing the cap, tip, barrel, back plug, reservoir, ink, and final packaging. DOMS leverages strategic brand relationships like F.I.L.A. and Reynolds (acquisitions).
How the Core Scholastic Segment Dominates the Revenue Mix
Scholastic Stationery accounted for 31% of Q1FY27 revenue, followed by Art Material (21%), Office Supplies (16%), Kits and Combos (10%), Paper Stationery (10%), and others (12%). DOMS Brand accounts for 80% of gross sales in Q1FY27. In the geographic mix, India contributed 88%, and the remaining came from Exports (12%).
Regional sales are well balanced across India: North (30% of domestic sales), West (28%), East (22%), and South (20%). Revenue grew 19.2% year-on-year to ₹670.5 crore, driven by domestic volumes and peak back-to-school demand. However, EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortization) declined 16.4% to ₹82.6 crore as margin fell 530 bps to 12.3%.
Why Geopolitical Tensions Squeezed Q1 Profit Margins
Consequently, net profit declined 23.4% to ₹45.3 crore. Higher raw material costs (up by 20%) due to the Middle East conflict squeezed margins. Looking ahead, DOMS has guided for 18-20% revenue growth for FY27. Management views margin compression as transitory rather than structural.
If raw material spot prices remain at current high levels, the company plans to take a further 4-5% price increase. Management expects this would return consolidated EBITDA margins to its targeted 15% to 16% range in FY28.
The Capex Strategy to Resolve High-Volume Capacity Constraints
To address ongoing capacity constraints, DOMS expects to commission close to 300,000+ square feet of operational area by the end of Q2FY27. This space will immediately ramp up production capacities for high-volume core categories, including wooden pencils, pens, and erasers.
The company invested approximately ₹100 crore in capex in Q1FY27 alone. DOMS targets a 3.0x gross fixed asset turnover. This means that every ₹1 invested in CapEx translates into ₹3 in sales. It typically takes 18 to 24 months of operational ramp-up for a newly commissioned facility to reach this optimal asset utilization rate.
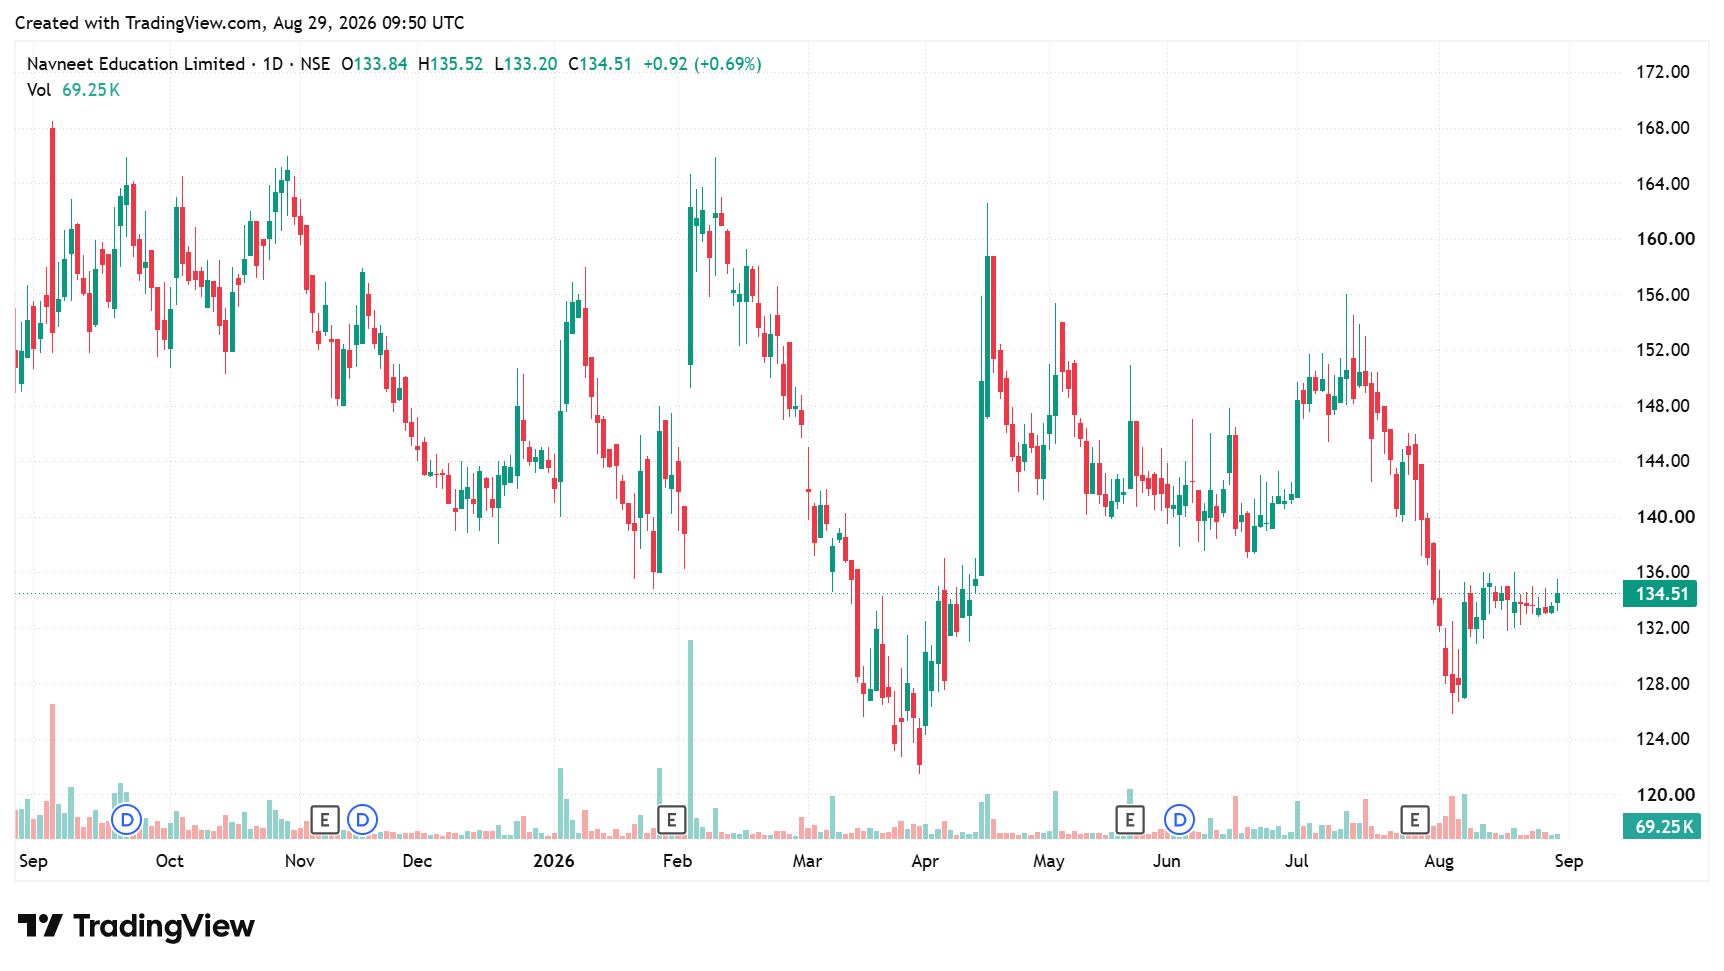
#2 Navneet Education: Leveraging education for stationery growth
Navneet Education is a major Indian educational publisher and stationery manufacturer. Its business model is structured around two core operating segments: Publishing (highest margin segment (40%) contributing 51.6% to Q1FY27 revenue) and the stationery segment.
Navneet is a market leader in publishing textbooks and syllabus-specific materials, particularly for its primary markets in Maharashtra and Gujarat. The workbook category is a key product line, accounting for 45% of its total Publication revenue. Schools market and recommend these workbooks, and students buy them through physical retail stores.
Why Expanding into the CBSE Curriculum is Navneet’s Next Major Growth Catalyst
Navneet has expanded its portfolio of textbooks and supplementary books up to Grade 10. Through this, it aims to tap into the growing number of schools following the CBSE-pattern curriculum. The stationery segment manufactures and sells a wide range of school and office stationery.
Navneet is undergoing a significant structural transformation. Curriculum changes are underway in its core markets of Maharashtra and Gujarat. Specifically, curriculum updates have been implemented for grades 2 to 6 in Maharashtra and for a few subjects in Gujarat. Management expects full-year volume-driven growth guidance of 10% for this division.
The Leadership Shakeup and Strategy to Capture 15% of the Non-Paper Stationery Market
The company is rapidly redesigning the packaging, look, and feel of its existing non-paper stationery vertical. It has appointed senior leadership to drive this growth. Management expects this category to reach 10% to 15% of domestic stationery revenue within three years.
How the ₹330 Crore K-12 Stake Sale Provides a Cash Buffer Against Muted Q1 Earnings
Navneet has sold a 4.5% stake in K-12 for ₹330 crore (retaining an 8.8% stake). Management plans to use this cash to finance organic and inorganic opportunities to scale the domestic stationery business. Q1FY27 Financials, however, were muted.
Consolidated revenue declined 0.8% year-on-year to ₹788 crore in Q1FY27, impacted by academic schedule delays in domestic publishing and supply chain issues in exports. EBITDA declined 12.8% to ₹198.0 crore as margin fell 350 bps to 25.1%. Consequently, consolidated net profit declined 10.2% to ₹141.0 crore.
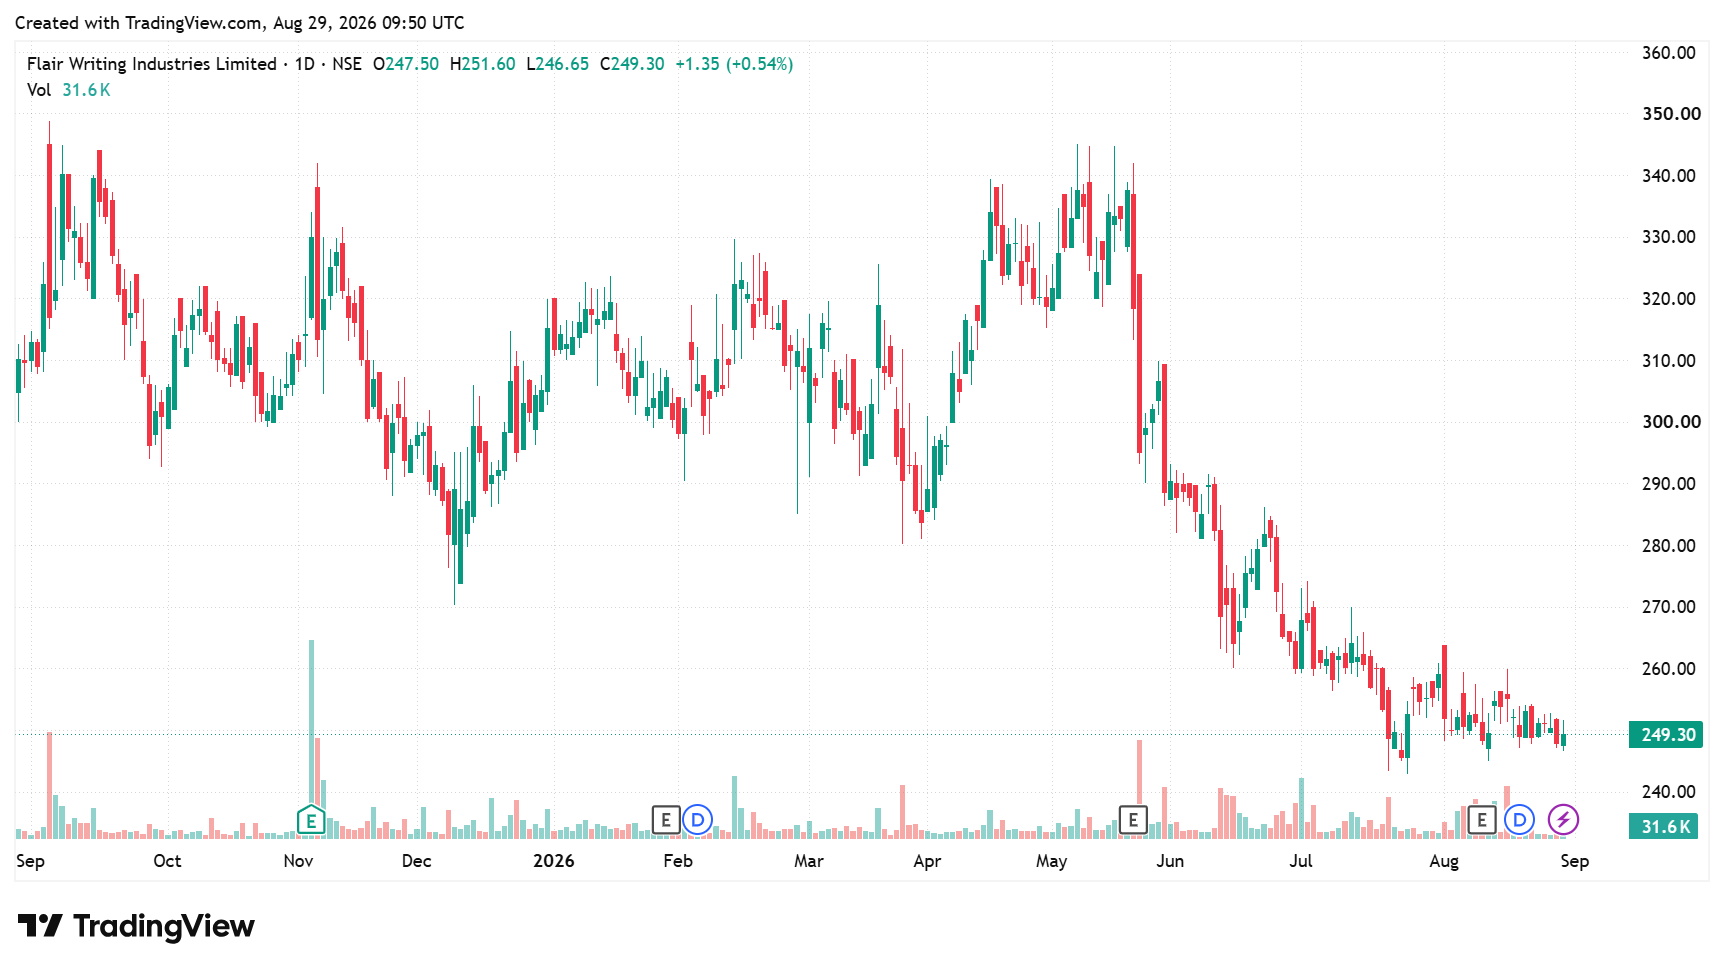
#3 Flair Writing Industries: Diversifying beyond its core pens
Flair Writing is a leading player in the writing instruments and stationery sector. The company has an annual installed manufacturing capacity of 2.4 billion pieces. Flair leverages one of the industry’s largest distribution networks, enabling it to quickly scale new categories. It has 8,000+ distributors and 330,000 wholesalers and retailers.
Its business is divided into 3 main segments: 69% of revenue comes from pens (writing instruments), 25% from creative products, and 6% from steel bottles and houseware.
How the Legacy Pen Business Defends its 18% Market Dominance
Pens & Writing Instruments is Flair’s legacy business and core revenue driver. Flair is an industry leader with an 18% market share in writing instruments in India. In Q1 FY27, this segment grew 9% year-on-year to reach ₹220 crore, driven by volume growth and positive demand during the back-to-school season.
Meanwhile, the Flair Creative business segment sells watercolors, crayons, erasers, and sketch pens. It is one of the fastest-growing divisions, with revenue rising 23% year-on-year to ₹80 crore in Q1 FY27. The bottles and houseware business also grew by 54.3% year-on-year to ₹19 crore. Through the latter two businesses, Flair is diversifying its revenue mix.
The Expansion Strategy to Support a 15% Manufacturing CAGR
Flair is actively expanding its manufacturing footprint to support an estimated 15% CAGR over the next three years. A new plant in Valsad for writing instruments and creative products is expected to be operational by the end of Q2FY27. This is expected to follow Flair’s historical capex-to-revenue ratio of approximately 3x.
Since the steel bottle capacity plan is currently utilized at 65%, Flair plans to commission new capacity in Q4FY27. This will increase steel bottle capacity by 30% to 35% and could generate revenue of ₹30-35 crore, depending on the final product mix.
Flair is deliberately shifting its revenue mix away from core pens and toward higher-growth, higher-margin categories like creative and steel bottles and houseware. These segments contributed 31% of total revenue in FY26 and are projected to scale to 35% to 38% of revenue in FY27. The Creative and steel bottle segment alone is projected to grow by nearly 40%.
Why Higher Input Costs Flatlined Q1FY27 Profit Growth
In Q1FY27, Flair delivered double-digit domestic revenue growth. Operating revenue increased 10.6% year-over-year to ₹319.2 crore. EBITDA increased 7.7% to ₹53.3 crore, while margins fell 46 bps to 16.7%. Consequently, net profit increased only 0.5% to ₹29 crore due to lower other income and higher input costs.
Here’s a snapshot of the Q1FY27 financial performance:
| Particulars | DOMS | Navneet | Flair |
| Q1FY27 Revenue | ₹670.5 crore | ₹788.0 crore | ₹319.2 crore |
| YoY Growth | +19.2% | -0.8% | +10.6% |
| Q1FY27 EBITDA (Growth) | ₹82.6 crore (-16.4%) | ₹198.0 crore (-12.8%) | ₹53.3 crore (+7.7%) |
| Margin | 12.3% | 25.1% | 16.7% |
| Q1FY27 Net Profit | ₹45.3 crore | ₹141.0 | ₹29 crore |
| Net Profit Growth | -23.4% | -10.2% | +0.5% |
| Key Trigger | Capacity Expansion | CBSE expansion and stationery revamp | Creative Segment Growth |
| Source: Management Commentary and Investor Presentation | |||
DOMS has the strongest growth momentum but faces margin pressure. Navneet offers higher profitability but weaker near-term growth. Meanwhile, Flair is showing steady growth through diversification.
Evaluating Capital Efficiency: Premium Valuations vs Industry Medians
DOMS boasts strong Return on Capital Employed (ROCE) and Return on Equity (ROE) due to its faster growth than Navneet and Flair. On valuation, DOMS trades at a discount to its 3-year historical median P/E multiple but at a premium to the industry median.
Flair is trading at a discount to both the industry and its historical median. Navneet is also trading in line with the industry but at a premium to its historical median.
| Peer Comparison (X) | ||||
| Price-to-Earnings Multiple | Return Ratios | |||
| Company | Company | 3Y Median | ROCE (%) | ROE (%) |
| DOMS | 61.4 | 71.9 | 24.3 | 20.7 |
| Navneet | 23.8 | 18.1 | 10.2 | 8.0 |
| Flair | 18.8 | 24.4 | 16.8 | 12.9 |
| Industry | 23.8 | 16.8 | 23.8 | |
| Source: Screener.in (As of 28th August 2026) | ||||
India’s stationery market is entering a phase where the shift towards organized and branded players could be as important as the overall market growth. With the market expected to reach ₹71,600 crore by FY28 and branded players’ share rising to 43%, the opportunity is widening.
DOMS is benefiting from its broad product portfolio and manufacturing scale, Flair is diversifying beyond pens, while Navneet is using its education ecosystem to build its stationery business. Meanwhile, it’s worth keeping these on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as necessary.