



India’s compressed biogas (CBG) market is moving from policy announcements to a larger commercial opportunity. As the name suggests, CBG is a renewable fuel produced by processing organic waste such as animal dung, food waste, and agricultural waste.
The government has now approved a ₹23,731 crore GOBARdhan scheme to boost CBG production with assured prices and capital support. The demand side is also getting a policy push. India’s CBG blending obligation will rise from 1% in FY26 to 3% in FY27, 4% in FY28 and 5% by FY29.
This gives CBG producers clear visibility for their output. Alongside the central policies, state governments are adding their own incentives. Maharashtra, for instance, has introduced a ₹500 crore CBG policy. The renewed focus, with policy support, is opening up opportunities for bioenergy, waste management, and CBG infrastructure players.
Notably, several players have already started building a presence in the CBG market. This article looks at three companies that are positioned to benefit from the sector’s expansion.
Join now
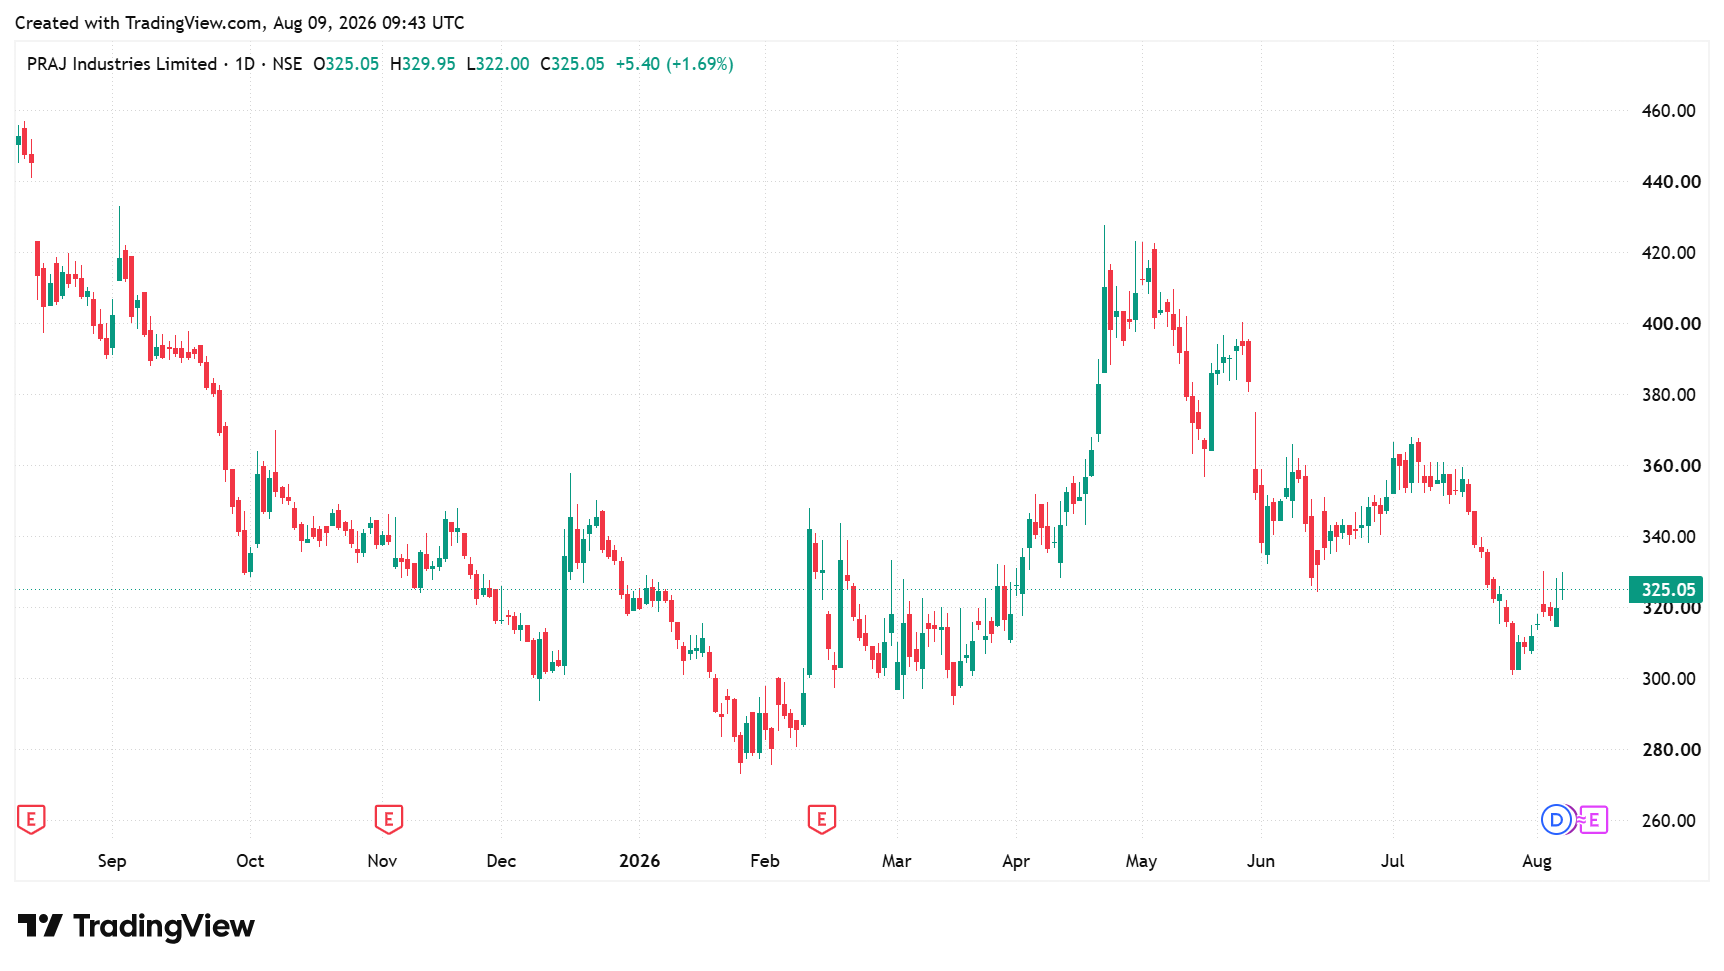
#1 Praj Industries: How Praj’s New Tech is Scaling India’s Biogas Market
Compressed Biogas (CBG) production is a rapidly growing and key component of Praj Industries’ bioenergy segment. The company’s innovation centre, Praj Matrix, has developed its proprietary RenGas technology, which forms the core of Praj’s offering.
This technology aims to increase the share of renewable fuel in the market and contribute to energy sovereignty. Management reports a robust inquiry pipeline for CBG projects based on press mud and Napier grass. Praj is also exploring exporting its RenGas CBG technology.
RenGas Technology and Feedstock Innovation
The RenGas process produces the highest-yielding biogas in the industry with 30% lower operating costs than traditional methods. To maximise yields and process efficiency, Praj has developed specialised feedstock preparation and stabilisation solutions, including PMStab, BMSolve, and NGStab.
Commercial Scale-Up and Organic Byproducts
The project is ready for commercialisation. It commissioned a pressmud-to-biogas plant and ramped up capacity from 0% to 100% of rated capacity within 60 days. Praj’s technology can convert a wide range of organic feedstocks, such as agricultural residues and organic wastes (cattle dung, food waste, municipal solid waste).
Margin Expansions via Value-Added Co-Products
To this end, Praj has demonstrated CBG plants using pressmud and rice straw mixed feedstocks at a commercial scale. Furthermore, the company is actively ramping up capacity at plants engineered for Napier grass and rice straw mixed feedstocks. Additionally, Praj enhances the project’s economic viability by recovering high-value co-products.
The digestion process creates value-added products like Organic Manure (Fermented Organic and Liquid Fermented Organic) and the Bio-bitumen Module. These high-margin value-added products improve the project’s internal rate of return.
Strategic Partnerships with BPCL and Indian Oil
Praj has also entered into certain partnerships. For instance, Praj has signed a Memorandum of Understanding (MoU) with Bharat Petroleum Corporation to establish a joint venture for CBG production. The MoU signed with Indian Oil also aims to set up production facilities for Sustainable Aviation Fuel, ethanol, and CBG.
#2 Va Tech Wabag: The 100-Plant CBG Blueprint
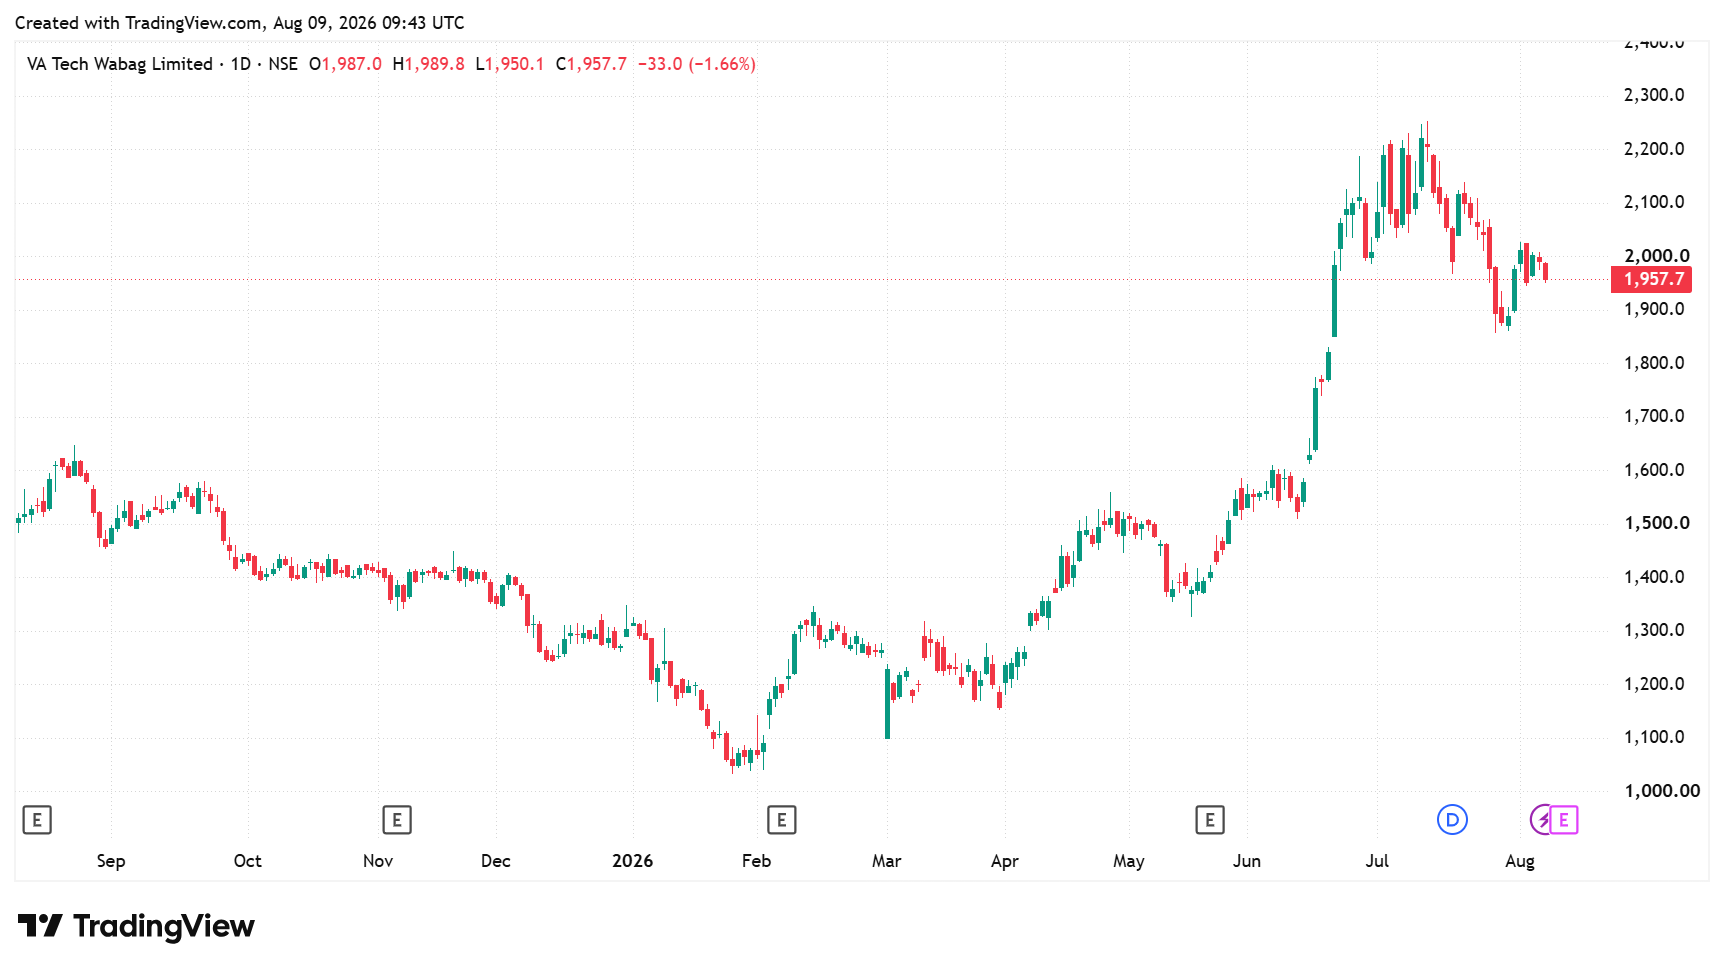
ForVa Tech Wabag, CBG is also key to its emerging future energy solutions. It has established a strategic partnership with Peak Sustainability to develop 100 CBG plants globally, converting organic waste streams into clean fuel.
The Ghaziabad Bioenergy Blueprint
The company successfully entered the CBG sector with its first milestone project located at the 70 MLD Sewage Treatment Plant in Ghaziabad, Uttar Pradesh. Va Tech developed this project in partnership with Peak. It is executed under a Build-Operate-Transfer (BOT) model via a dedicated joint venture named Ghaziabad Bioenergy.
The facility uses raw biogas generated from sewage sludge digestion to produce Bio-CNG. This single plant is capable of providing cooking gas to around 3,500 homes or fueling 400 vehicles. Wabag is handling the execution and the long-term operations and maintenance of this plant.
Expanding O&M Contracts and Green Revenue
Va Tech Wabag management states that the long-term strategic plan is to implement this model in municipal areas as well. This will also help municipal corporations generate new streams of ‘green revenue’. This new revenue could help the company expand the revenue share of operations and maintenance contracts to 20% of total revenues, from 17% in FY26.
₹17,235 Crore Order Book and Margin Projections
The company management has projected a revenue CAGR of 15–20% over the next 3-5 years. EBITDA margins are expected to remain in the 13-15% range. As of 31 March, 2026, the order book stood at ₹17,235 crore, which is more than four times its FY26 revenue.
Expansion into the Middle East and Africa, future energy solutions (green hydrogen, ultra-pure water, CBG), solar PV manufacturing and sectors such as semiconductor facilities could be future growth drivers.
#3 TruAlt Bioenergy: How TruAlt is Scaling its CBG Pipeline to 152 TPD
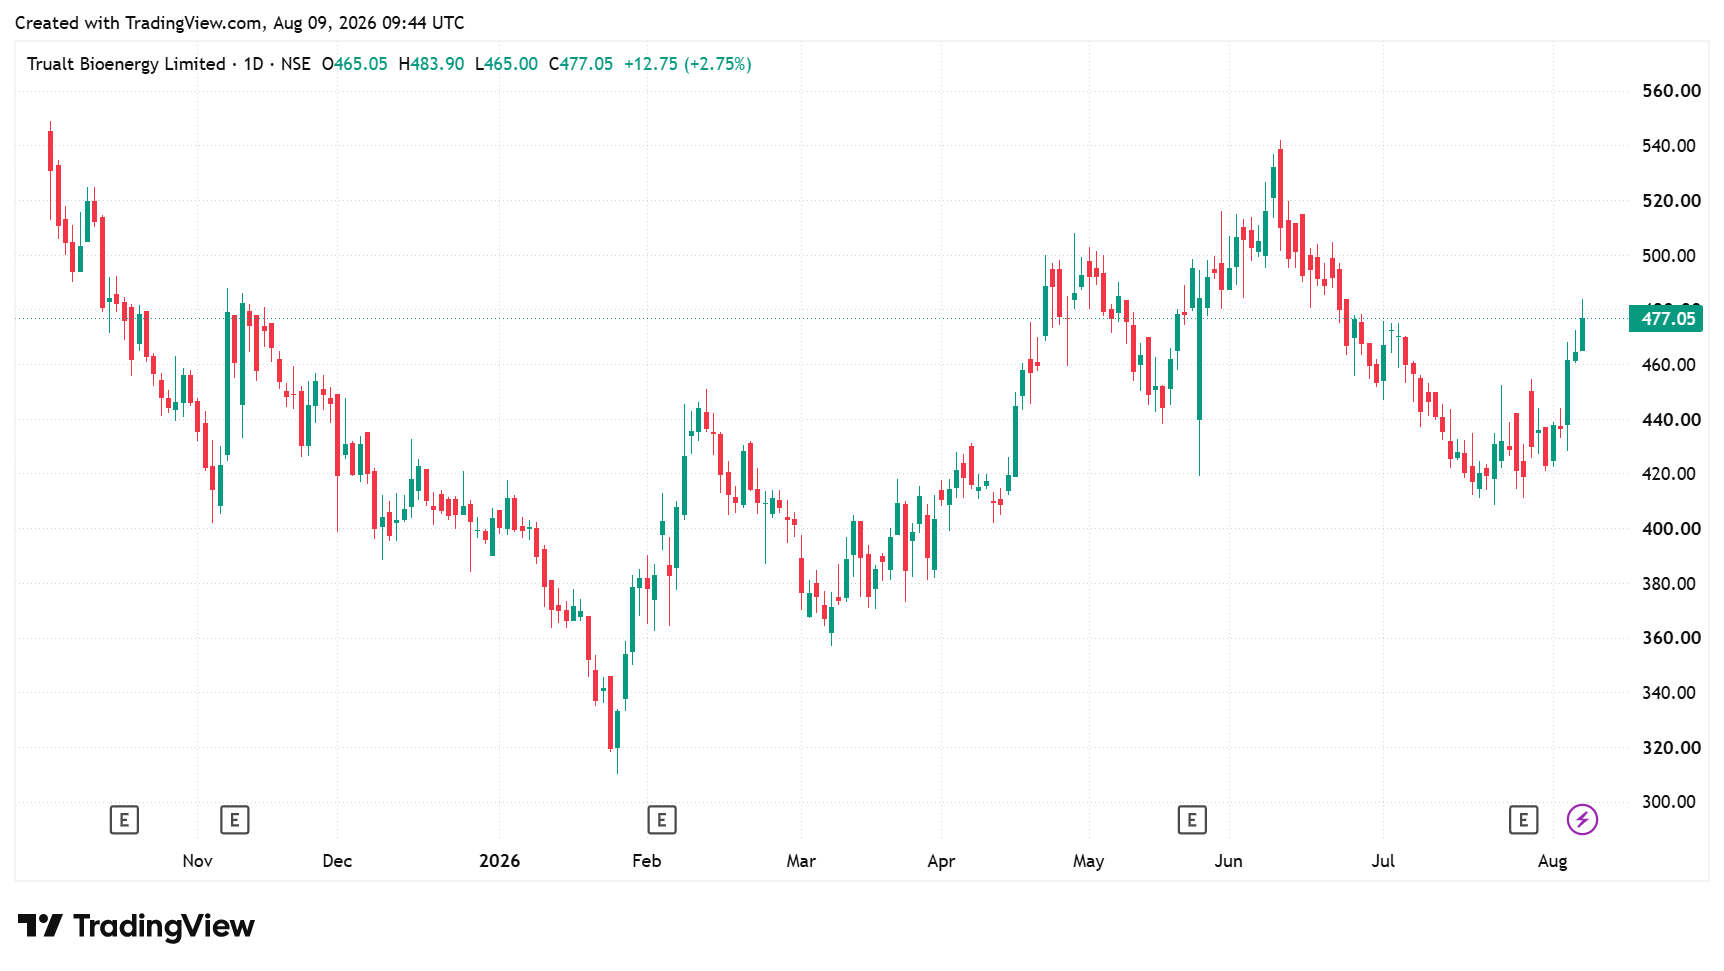
TruAlt Bioenergy’s CBG business is one of the company’s major long-term growth and earnings drivers. It has created a local supply chain that acts as a strong competitive barrier. TruAlt focuses primarily on sugarcane press mud and spent wash. TruAlt restricts plant setups to locations within a 30-kilometre radius where raw material availability is 3x the requirement.
The 30-Kilometer Feedstock Strategy and Q1 FY27 Margins
Currently, TruAlt operates one CBG plant (Unit 1 at Karnataka) with an installed capacity of 10.2 Tonnes Per Day (TPD) under its subsidiary Leafiniti Bioenergy Private Limited. The operating plant runs at a 78% capacity utilisation.
During Q1FY27, the CBG segment revenue rose by 11% year-on-year to ₹11.3 crore. Approximately 60% of revenue comes from gas sales, and 40% comes from organic fertilisers. These co-products include fermented organic manure (FOM) and liquid fermented organic manure. These are high-margin products and contribute significantly to strong margins.
At its inception, solid FOM prices stood at ₹500 per tonne, which has now surged to ₹2,500 to ₹2,800 per tonne. Strong segment margins of 55.6% also reflected this shift, even though EBITDA fell 6.2% to ₹6.2 crore. Net profit stood at ₹4-4.5 crore. It aims to have a long-term margin of greater than 60%.
Scaling via JVs: The Sumitomo and GAIL Partnerships
To expand its CBG business, TruAlt has formed two strategic joint ventures through its subsidiaries, holding a 51% controlling equity stake in both companies. The JV with Sumitomo Corporation (Japan) plans to invest ₹300-340 crore to build four 20-TPD CBG units in Karnataka and Maharashtra.
Commissioning is scheduled in phases based on CGD offtake demand, with 40% of capacity expected to be live in FY27, FY28 (85%), and 90% by FY29. Of the capacity to be commercialised in FY27, three out of the four Sumitomo JV plants are near commissioning and are expected to start generating revenues in Q4FY27.
The JV with GAIL India is planning to build 6 more CBG plants at a cost of ₹425 crore, each with 12 TPD capacity. Overall, TruAlt has a total of 24 CBG plants in its long-term pipeline. Of this, the near-term 9-plant (Sumitomo and GAIL JVs) represents a peak daily capacity of 132 TPD. The peak capacity of all ten plants will be 152 TPD.
Offtake Guarantees and the ₹600 Crore Revenue Blueprint
Importantly, GAIL ensures guaranteed offtake of 80% to 90% of daily production, which leads to immediate capacity utilisation. Management estimates the annual revenue potential of 132 TPD to be around ₹600 crore at full utilisation, with revenue of ₹4.5 crore per tonne per day of capacity.
The Valuation Gap: Execution Over Expectations
Backed by strong growth, Va Tech Wabag return ratios (Return on Capital Employed and Return on Equity) are stronger. In contrast, Praj’s profitability has been impacted by weakness in its ethanol segment, which has weighed on its return ratios.
In terms of valuation, Va Tech Wabag’s valuation has re-rated over the last three years, and it now trades at a premium to both its five-year EV/EBITDA and the industry median. Praj trades at a premium to both the historical and industry median. TruAlt’s trading history is limited.
| Peer Valuation | |||||
Particulars | EV/EBITDA Multiple (X) | Return Ratios | |||
| Company | 5Y Median | Industry | ROCE (%) | ROE (%) | |
| Praj Industries | 29.8 | 25.6 | 18.5 | 6.1 | 1.5 |
| Va Tech Wabag | 32.7 | 10.4 | 11.3 | 21.3 | 15.9 |
| TruAlt Bioenergy | 12.0 | NA | 11.4 | 10.4 | 8.4 |
| Source: Screener.in (Source: 08 August 2026) | |||||
The three companies offer different ways to participate in India’s CBG opportunity. Praj Industries brings proprietary technology and feedstock solutions, Va Tech Wabag is building CBG around sewage and municipal waste, while TruAlt Bioenergy is scaling capacity through JVs and assured offtake.
The key differentiator now is execution, as the companies move from pilot projects and partnerships to commercial-scale capacity. Also, CBG is still at a nascent stage, and the sector’s growth will depend on project execution, capacity utilisation, and whether the policy support translates into operating capacity. Meanwhile, it’s worth keeping them on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data were unavailable have we used an alternate, widely accepted, and widely used source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.