



The way India uses electricity is changing. More businesses now need power they can’t afford to lose, even when the grid fails. This has kept demand for diesel generator sets steady across factories, hospitals, offices and infrastructure projects.
India’s genset market was worth around ₹13,500 crore in FY25 and is expected to reach nearly ₹22,000 crore by FY30, according to industry data cited by Greaves Cotton. But the next leg of demand is coming from a different kind of customer.
Macro Shift: Why Data Centers Need Mission-Critical Generation
Data centers are emerging as a key growth driver for high-capacity gensets. India’s data center capacity is expected to expand sharply in the coming years as cloud usage, digital services, and Artificial Intelligence workloads continue to increase. Since these facilities operate around the clock, even a brief power disruption can affect operations.
This makes reliable backup generation a core part of their infrastructure. This is also changing the genset market profile. Data center applications are expected to grow at around 20.5% CAGR between FY25 and FY30. Batteries can help bridge short power interruptions, but large facilities still need generators that can support heavy loads for longer periods.
Against this backdrop, this article looks at two genset stocks that are seeing rising demand from India’s expanding data center infrastructure.
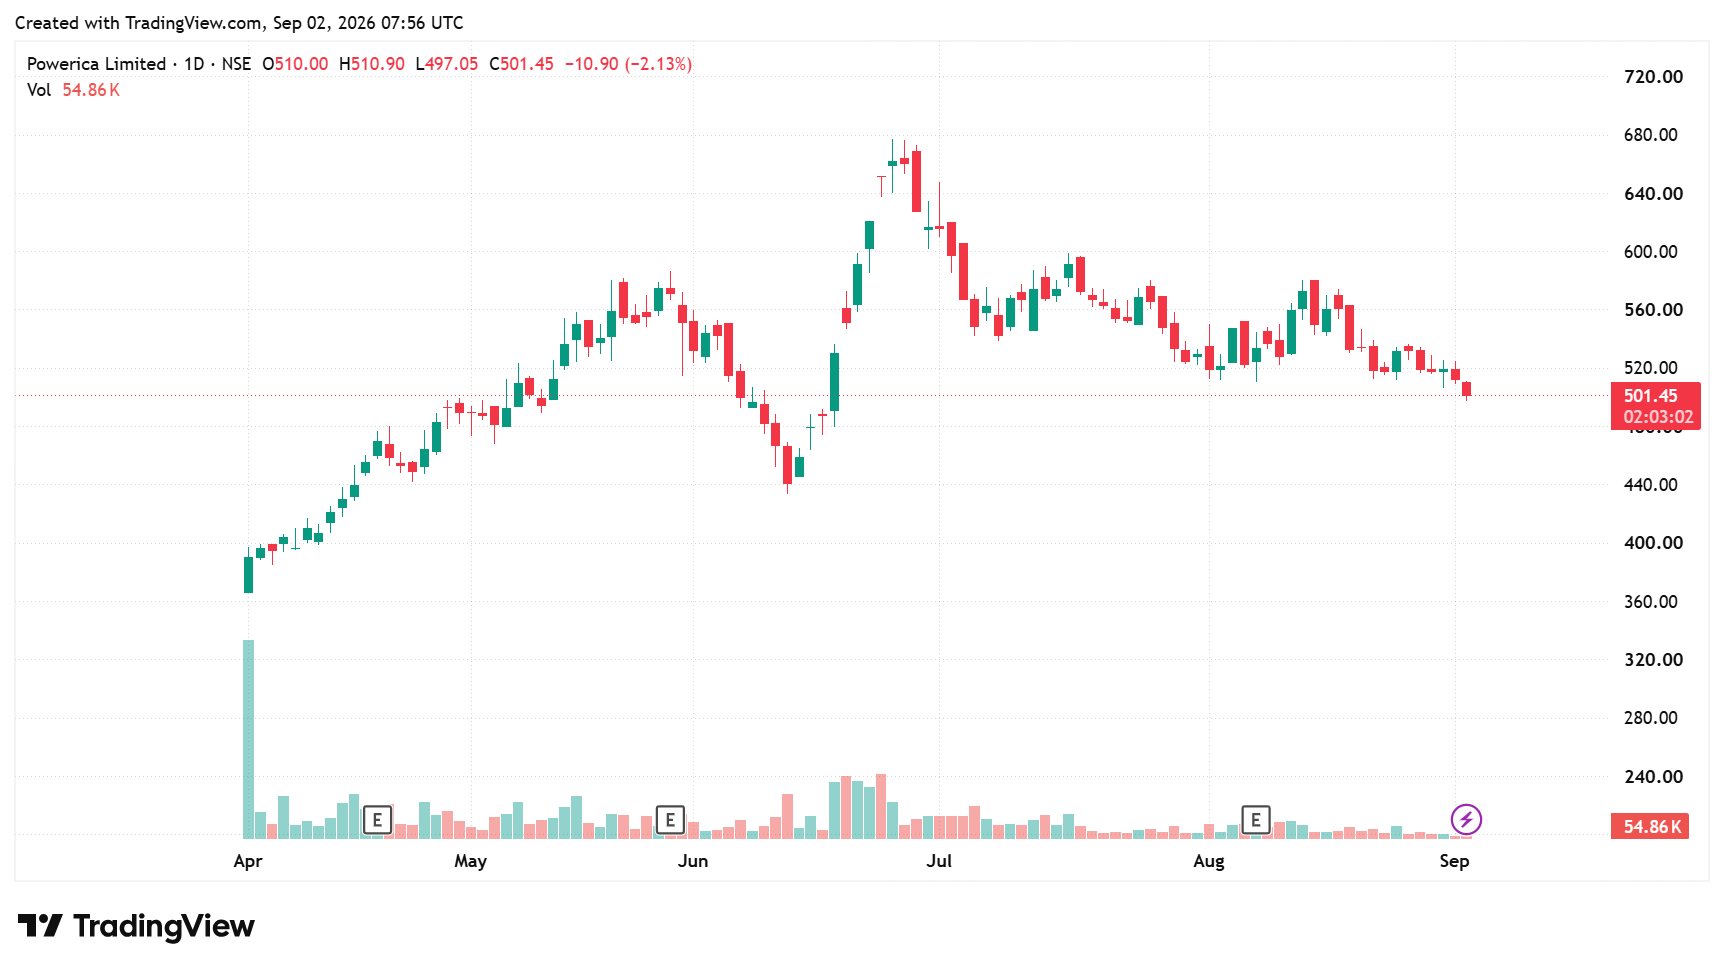
#1 Powerica: ₹1,100 Crore Data Center Order Book
Powerica offers power solutions through two key business divisions: the Generator Set Business and the Wind Power Business. The generator business is its core legacy business, contributing 81.4% of revenue, or ₹635.2 crore, in Q1FY27. The company has been manufacturing generators in partnership with Cummins India for over 40 years.
Cummins Alliance & DG Set Capacity
Powerica manufactures diesel generator (DG) sets ranging from 7.5 Kilovolt-Ampere (kVA) to 3,750 kVA. These DG sets are used across sectors, including manufacturing, infrastructure, real estate, and digital services. DG sets powered by Cummins engines specifically contributed 72% of total generator set business revenue in Q1FY27.
Why Data Centers Dominate the ₹1,700-Crore Order Book
Data centers have emerged as Powerica’s fastest-growing segment. In Q1FY27, data center applications contributed 20% of the generator set division revenue. As of July 2026, the DG set order book stood at ₹1,700 crore. Of this, ₹900 crore worth are data-center-specific orders. This data-center order book expanded rapidly to ₹1,100 crore by 7 August, 2026.
This includes a single hyperscaler/colocation order of ₹200 crore bagged during the first week of August. The delivery cycle for a standard DG set business order is 24 hours to 12 months. However, data center orders typically take 12 to 18 months to complete.
Order Execution: Why Single-Shift Slack Protects Powerica’s Delivery Window
Powerica directly manages the customer engagement and handles on-site mechanical and electrical installation. Demand is strong, as shown by a 75% to 80% capacity utilization rate at its plant. Because this utilization is based on a single shift, Powerica can scale up operations if needed.
Management emphasizes that they are not losing or refusing any customer orders due to supply-side issues. Importantly, Powerica connects and communicates directly with data center clients, eliminating the need to route orders through Cummins. The company says its execution and strong credibility could be a key factor amid growing competition.
Supply Chain Friction: Navigating a 150 bps Margin Squeeze
The Generator Set segment’s EBITDA margin fell 150 bps to 5.6% in Q1FY27. Increased raw material prices, supply-chain stress and the natural time lag in passing these costs to clients impacted margins. Powerica has already initiated a two-phase price hike. Management expects margins to recover across Q2 and Q3.
The Wind Division: 18.6% of Topline, 67% of Core EBITDA
The Wind Power business contributes the remaining 18.6% of revenue. This segment has a strong 48.6% margin. As a result, despite contributing modestly to revenue, the wind power business accounts for 67% of Powerica’s EBITDA (earnings before interest, taxes, depreciation, and amortization).
The company’s revenue grew by 26.7% year-on-year to ₹780.1 crore in Q1FY27. EBITDA grew by 20.4% to ₹106.3 crore, while blended margins stood at 13.6%. Net profit grew by 27.3% to ₹64.3 crore. A substantial reduction in interest burdens following debt repayment boosted profitability.
#2 Kirloskar Oil Engines: 192 MW Hyperscaler Order Secured
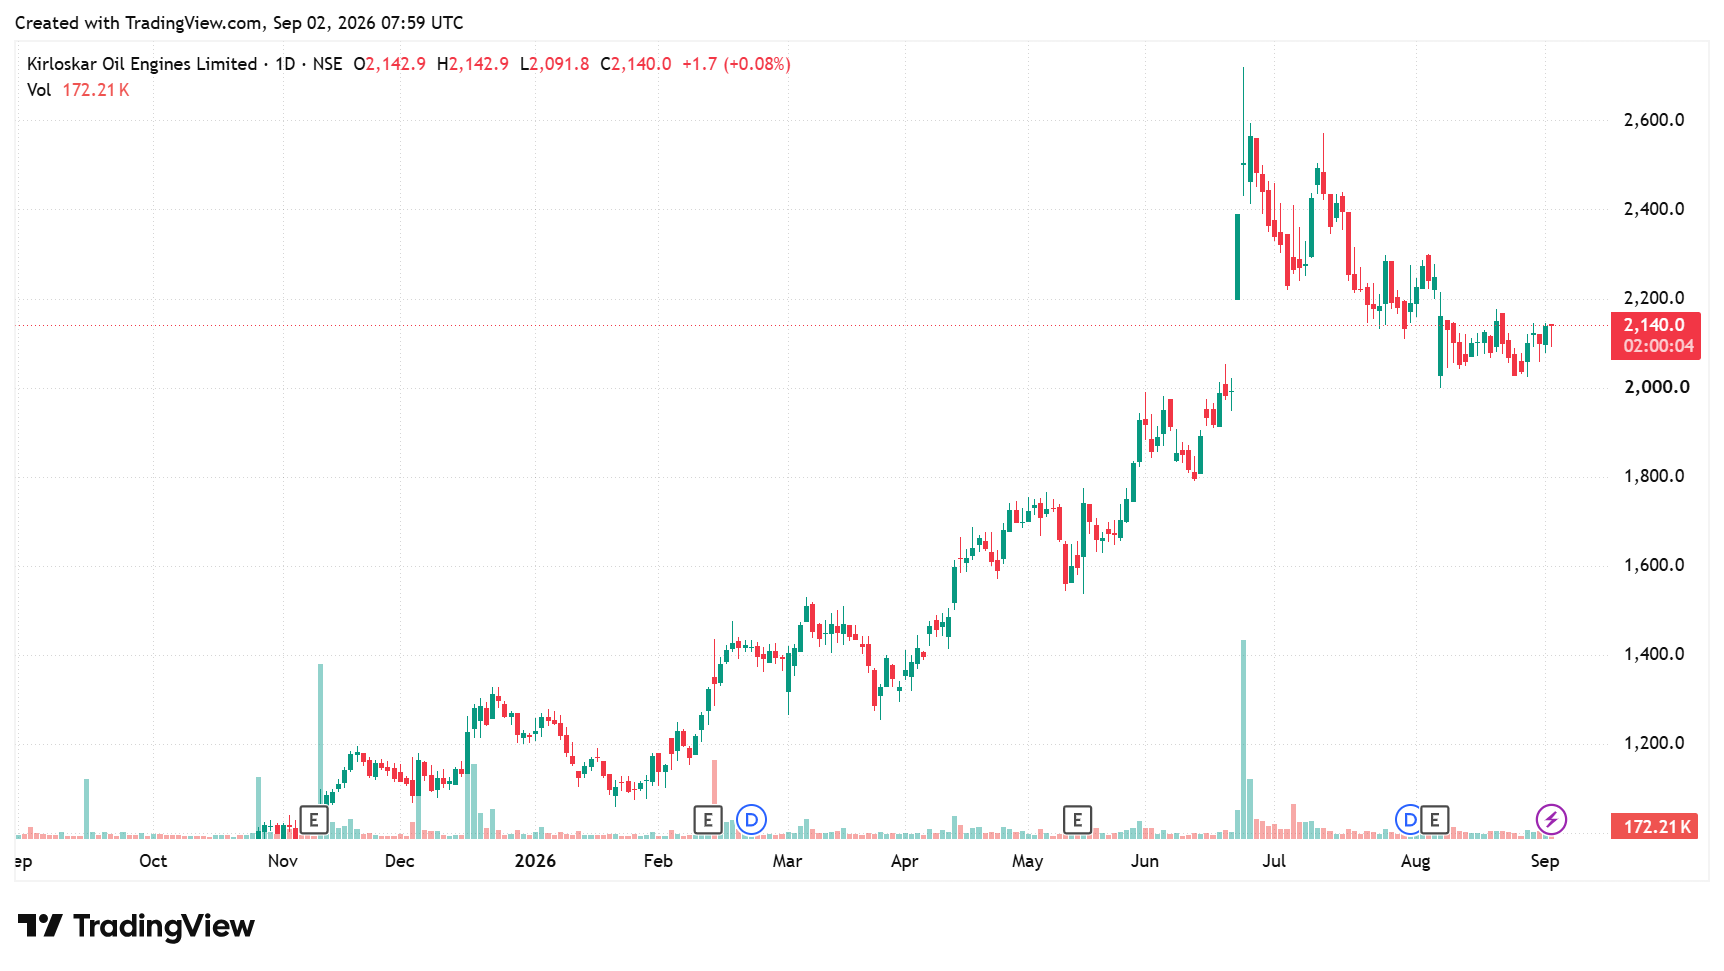
Kirloskar Oil Engines (KOEL) manufactures engines and generator sets. It has a 28% market share in power generating sets. Powergen accounts for 49% of total revenue. It is followed by the Industrial (25%), Distribution and Aftermarket (18%), and the International B2B Business (7%).
Hyperscale Pivot: Breaking Into 192 MW Mission-Critical Power
Currently, KOEL manufactures modular power platforms and high-horsepower systems for data centers with capacities reaching up to 2 megawatts (MW). KOEL is actively supplying power solutions across segments of the data center industry. It already has an established presence in Edge and Enterprise data center facilities.
The company is now steadily expanding into Hyperscaler operations. In fact, KOEL has recently won a hyperscaler data center order of about 192 MW. The contract covers the supply of gensets, along with an operations and maintenance agreement spanning 5 to 6 years. The order also marks its entry into high-horsepower and ultra-high-horsepower alternatives.
Additionally, the company is receiving significant inquiries as several new players enter the data center sector. Revenue contribution for the 192 MW order will begin upon recognition in FY27. To meet growing and future demands, management is scaling product capabilities. It also offers specialized modular power platforms like the “Optiprime” series.
Margin Contraction: Commodity Pressures Shave 230 bps in Q1FY27
From a financial perspective, the standalone revenue rose 16% year on year to ₹1,461.4 crore in Q1FY27. EBITDA fell 4% to ₹165.5 crore, while the margin declined 230 bps to 11.2%. As a result, net profit declined 9% to ₹99.3 crore. Higher commodity prices pushed raw material costs up, squeezing the margin.
The ₹16,600-Crore Blueprint: Scaling Kagal for Global Demand
Looking ahead, management has outlined an ambitious target to become a ₹16,600 crore company by FY30. To meet the targets, KOEL is increasing its current capacity of 1,35,000 engines by 50,000 units. This expansion is expected to become operational by April of next year.
KOEL recently announced an additional capex of ₹1,400 crore over the next two years. This will fund a completely new building at the existing Kagal site, increasing capacity to 20,000 engines. This new capacity will support the company’s overall demand, especially for high-horsepower engines and international markets.
Here’s how both companies stack up:-
| Particulars | Powerica | Kirloskar Oil Engines |
| Core Genset Presence | Cummins Partnership for 40+ years | 28% market share |
| Data Center Exposure | 20% of Genset revenue in Q1FY27 | Established in Edge & Enterprise |
| Data Center Order Book | ₹1,100 crore | 192 MW hyperscaler order |
| Data Center Opportunity | Hyperscaler/colocation projects | Hyperscaler and high-horsepower systems |
| Q1FY27 Revenue (Growth) | ₹780.1 crore (+26.7%) | ₹1,461.4 crore (+16%) |
| EBITDA | ₹106.3 crore (13.6% margin) | ₹165.5 crore (11.2% margin) |
| Net Profit (Growth) | ₹64.3 crore (+27.3%) | ₹99.3 crore (-9%) |
| Management Commentary and Investor Presentation | ||
The table highlights a strong financial performance from both companies. However, the quality of growth differs. Powerica delivered faster revenue and profit growth, along with a higher blended EBITDA margin. Its growing data center order book adds visibility to near-term growth.
KOEL, meanwhile, reported slower profit growth but has a larger scale. It is moving into the higher-value hyperscaler segment, with its 192 MW order providing a key growth opportunity.
The Valuation Spread: Growth Multiple vs Legacy Pricing
Powerica has a higher Return on Capital Employed (ROCE) than Kirloskar, indicating more efficient use of capital, while Return on Equity (ROE) is almost similar for both companies.
From a valuation perspective, following a sharp 137% gain in the last year, Kirloskar is currently trading at a premium to the industry median and its own 5-year median. Powerica is a new listing but currently trades at a discount to the industry multiple.
| Peer Comparison (X) | |||||
Company | Price-to-Earnings Multiple | Return Ratios | |||
| Company | 5Y Median | Industry | ROCE (%) | ROE (%) | |
| Kirloskar Oil | 54.3 | 32.5 | 43.2 | 14.6 | 17.5 |
| Powerica | 22.4 | NA | 32.5 | 15.7 | 17.4 |
| Source: Screener.in (Data as of September 02 2026) | |||||
The key point is that the two companies are entering the data center opportunity from different positions. Powerica already has a sizeable data-center order book, with ₹1,100 crore of orders by August 2026, while its plant was operating at 75% to 80% utilization.
KOEL, meanwhile, is moving further into hyperscaler projects, with a 192 MW order that also includes a five- to six-year O&M contract. The opportunity is therefore shifting toward larger, longer-duration projects. How well each company converts this demand into sustained revenue and margins will determine the value of this growth.
Nonetheless, you could keep these names on your watchlist to track their execution.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely used, and accepted source of information only when the data was unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as may be necessary.