



Without this machine, modern manufacturing would be nearly impossible. Yet India remains heavily dependent on imports for it.
The machine is the CNC, or computer numerical control, an automated machine that cuts, drills, and shapes metal into high-precision components. From car gearboxes and railway equipment to sophisticated aerospace and defense systems, CNC machines sit quietly at the start of much of India’s manufacturing chain.
Without them, modern manufacturing cannot scale. That is why machine tools are often called the “mother industry” of manufacturing: they are the machines that build other machines.
India’s CNC import gap is the opportunity
According to the Indian Machine Tool Industry report, India imported roughly ₹ 21,932 crore worth of machine tools in FY26, with imports accounting for around 60-65% of domestic machine-tool consumption. The dependence is even higher in sophisticated applications such as aerospace and defence.
That import gap is now becoming an investment opportunity. As India pushes for greater manufacturing self-reliance, the focus is shifting from simply assembling finished products locally to building more of the machinery and critical components that make them.
Join now
This creates a long-term opportunity for domestic CNC and machine-tool makers as manufacturers look to reduce import dependence and build local supply chains. Two listed companies offer a direct play on this trend: Jyoti CNC Automationand Macpower CNC Machines. Both are benefiting from the same import-substitution and indigenisation story.
Jyoti CNC Automation: The Scale Play
Jyoti CNC Automation is India’s largest listed pure-play CNC machine-tool maker. But its advantage is not just scale. The company has built a deeply backward-integrated manufacturing hub in Rajkot, producing critical components such as spindles, automatic tool changers, and rotary tables in-house.
This integration matters because these are high-value assemblies that many domestic manufacturers still import. Producing them in-house lowers machine costs while supporting gross margins, which stood at 58% in Q1 FY27.
The company also has access to advanced European technology through its French subsidiary, Huron Graffenstaden. Its 5-axis machining capabilities are particularly relevant for aerospace and defence, where India remains heavily dependent on imported high-precision machines.
Jyoti CNC: Financial Performance
| Period | FY25 | FY26 | Q1FY26 | Q1FY27 |
| Revenue (₹ crore) | 1,615 | 1,949 | 410 | 509 |
| YoY Growth (%) | – | 20.7% | – | 24.0% |
| EBITDA Margin (%) | 28% | 29% | 24% | 23% |
| Net Profit (₹ crore) | 310 | 391 | 71 | 57 |
| YoY Growth (%) | – | 26.2% | – | -19.7% |
Jyoti CNC has begun FY27 on a positive note. Consolidated revenue grew 24% YoY to ₹509 crore in Q1 FY27. EBITDA margin declined to 23% from 24% a year ago, while net profit declined 20% to ₹57 crore from ₹71 crore.
The decline in profitability margins is primarily due to higher finance costs and revenue deferral at the French subsidiary, Huron.
However, what’s important is the order book. At the end of June 2026, the order book stood at ₹4,848 crore, equivalent to almost 2.5 times FY26 revenue. Aerospace and defence accounted for 38% of the book, followed by general engineering at 20% and auto and auto components at 19%.
Scaling Up Capacity
Capacity is the next leg of the story. Jyoti operated at around 90% utilisation in FY26, leaving limited room for volume growth. It is now investing ₹450 crore to increase annual capacity from 6,000 to 16,000 machines by September 2026.
The company is also moving deeper into import substitution. Its newly launched NX 6240 EY double-column machine, with an estimated ₹3-5 crore average selling price, targets applications in railways, power and heavy engineering.
Risks to Watch
Huron is the biggest near-term overhang. French authorities opened a judicial investigation into the subsidiary over alleged violations of EU export controls involving dual-use machine tools exported to Russia via India.
The investigation has also affected shipments, leading to around ₹35 crore of revenue being deferred in Q1FY27 as Huron shifted to delivery-based revenue recognition. Management expects these dispatches to be recognised in the second half. Any prolonged regulatory action could further disrupt Huron’s exports and technology access.
Working capital is another key monitorable. Jyoti’s cash conversion cycle increased to 359 days in FY26 from 304 days in FY25. Working-capital days rose to 234 days from 203 days. With the company ramping up capacity, any further deterioration in working-capital efficiency may slow cash conversion and put pressure on operating cash flows.
Investors should also keep an eye on promoter pledging, which has increased to 20.9% of promoter holdings in Q1 FY27 from 4.1% a year ago.
FY27 Growth Outlook
Going forward, management expects consolidated revenue growth of 25-30%, with an Earnings Before Interest Tax Depreciation Amortisation (EBITDA) margin of around 25%. It further expects approximately 50% of EBITDA to convert into operating cash flow. For FY27, the company is targeting annual order intake of ₹2,500–3,000 crore.
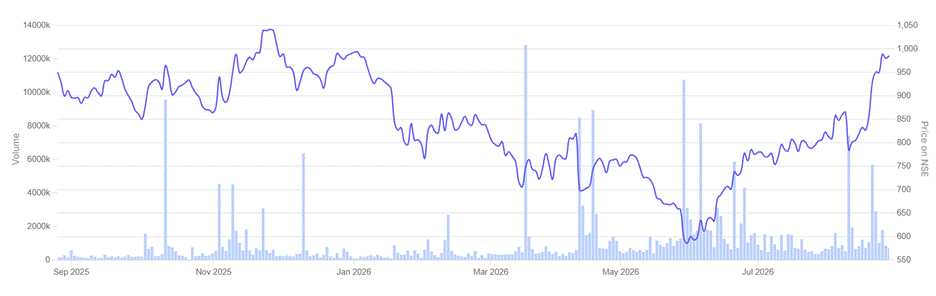
Jyoti CNC: 1 Year Stock Price Chart
Macpower CNC Machines: The Smaller Growth Bet
While Jyoti CNC represents the scale and technology-heavy play, Macpower CNC Machines offers exposure to the same manufacturing cycle from a much smaller base. That gives Macpower more room to grow market share and compound revenue at a faster rate, although its smaller scale also makes quarterly execution more sensitive.
This debt-free company has developed more than 315 machine models and serves customers across defense, aerospace, auto, electronic manufacturing services, and general engineering. The company is scaling and setting up new plants. About 50% of the new plant’s capacity is planned for defence work and higher-margin products.
Macpower CNC Machine: Financial Performance
| Period | FY25 | FY26 | Q1FY26 | Q1FY27 |
| Revenue (₹ crore) | 262 | 333 | 61 | 95.2 |
| YoY Growth (%) | – | 27.3% | – | 56.1% |
| EBITDA Margin (%) | 15.9% | 16.2% | 13.0% | 16.2% |
| Net Profit (₹ crore) | 26.2 | 33.9 | 4.6 | 9.6 |
| YoY Growth (%) | – | 29.3% | – | 108.7% |
Its June-quarter financial results showed sharper percentage growth than Jyoti’s. Revenue jumped 56% YoY to ₹95.2 crore, while profit more than doubled to ₹9.6 crore. EBITDA margin also improved to 16.2%.
Another key highlight is the company’s order book, which is at ₹456 crore as of June 2026. This is around 1.37 times FY26 revenue. Its ₹456 crore order book is becoming more premium, with 40% of orders belonging to the NEXA series, which is a premium range of high-end CNC machine tools.
Management is targeting 28–30% revenue growth in FY27. To support this, the company is investing around ₹50 crore in a new facility near Rajkot.
Risks to Watch
The company maintains inventory of more than 19,000 components across 383 variants. This has increased inventory and working-capital requirements, while tying up cash in the business. As a result, free cash flow can lag reported profit.
Another key risk to watch is quarterly execution. Since the company operates from a smaller base, quarterly revenue and margin delivery are sensitive to customer bank loan disbursements, client payment timings, and invoice clearances before machine handover.
Consequently, an execution misstep or order delay could exert a disproportionate impact on earnings expectations than it would for a larger player such as Jyoti.
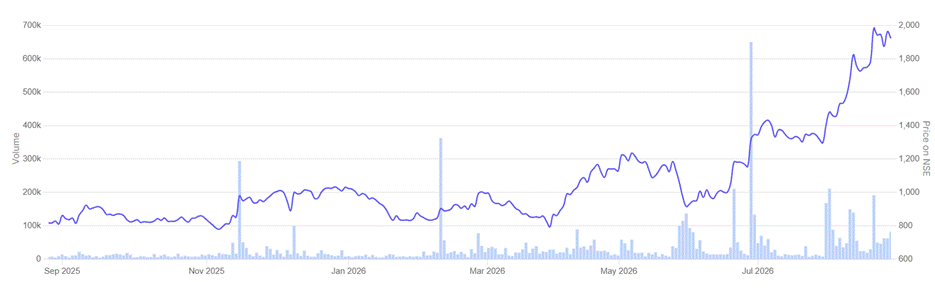
Macpower CNC Machines: 1 Year Stock Price Chart
Valuation: Macpower Trades Further Above Its Historical Multiple
Both stocks command premium valuations compared with the broader machine-tool industry, but the nature of the premium is different.
Valuation Trend
| Metrics | Trailing P/E | 5-yr Median PE | Industry Median PE |
| Jyoti CNC Automation | 69.7 | 73.0 | 33.24 |
| Macpower CNC Machines | 50.6 | 30.4 | 33.24 |
Jyoti CNC trades at 69.7 times trailing earnings, broadly in line with its five-year median P/E of 73 times. However, the stock trades at more than 2x the industry median P/E of 33.24 times, showing that the market continues to assign a significant premium to its scale, technology capabilities and growth outlook.
Macpower, meanwhile, trades at 50.6 times trailing earnings, well above its five-year median P/E of 30.4 times. The larger gap suggests the market has re-rated the stock more aggressively on expectations of faster growth.
For both stocks, therefore, future returns will depend not just on earnings growth, but on whether that growth is strong enough to justify the valuations investors are already paying.
Same Theme, Different Bets
Both companies are riding the same structural shift: India’s push to manufacture more cars, aircraft components, defence equipment, railway systems and electronics domestically.
That creates a long runway for CNC manufacturers. But the two stocks offer different ways to play it. Jyoti CNC brings scale, a broader product portfolio, greater exposure to high-end machines and a large order book.
Macpower offers a smaller base, faster percentage growth and a debt-free balance sheet. Its growing presence in higher-value machines could also give it more room to move up the value chain.
That makes the choice less about the industry opportunity and more about the type of growth investors want exposure to. Jyoti offers greater scale and visibility. Macpower offers higher growth potential, but with greater execution risk.
The Make in India opportunity may be the same. The path each company takes to capture it and the risks along the way are very different. Add these stocks to your watchlist and monitor how they execute their growth plans.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.