



What do semiconductors, Artificial Intelligence, data centres and green hydrogen have in common? They all need enormous amounts of water. And as India builds capacity in these emerging industries, water is quietly becoming a new infrastructure bottleneck.
A single semiconductor fab can consume up to 10 million gallons of ultra-pure water every day. Hyperscale data centres can use 3-5 million gallons daily, with water demand from the sector growing at 25-35% annually. Green hydrogen adds another layer, requiring only 15-25 litres of ultrapure water to produce 1 kg of hydrogen. This creates a new opportunity beyond traditional municipal water infrastructure.
Desalination, water recycling, industrial wastewater treatment, and ultrapure water systems are becoming critical for industries India wants to scale rapidly. The opportunity is not limited to India. Va Tech Wabag FY26 Annual Report estimates the global desalination market to grow from US$18 billion to US$30 billion (around ₹2.9 lakh crore) by 2031.
The scale of this opportunity is evident from the nearly 60% increase in water-focused investment funds since 2020, reaching approximately US$94 billion. Now, the bigger question is no longer just who supplies water to cities. It is who will supply, treat and recycle the water needed to power India’s next wave of industrial growth? Let’s look at two such companies.
Join now
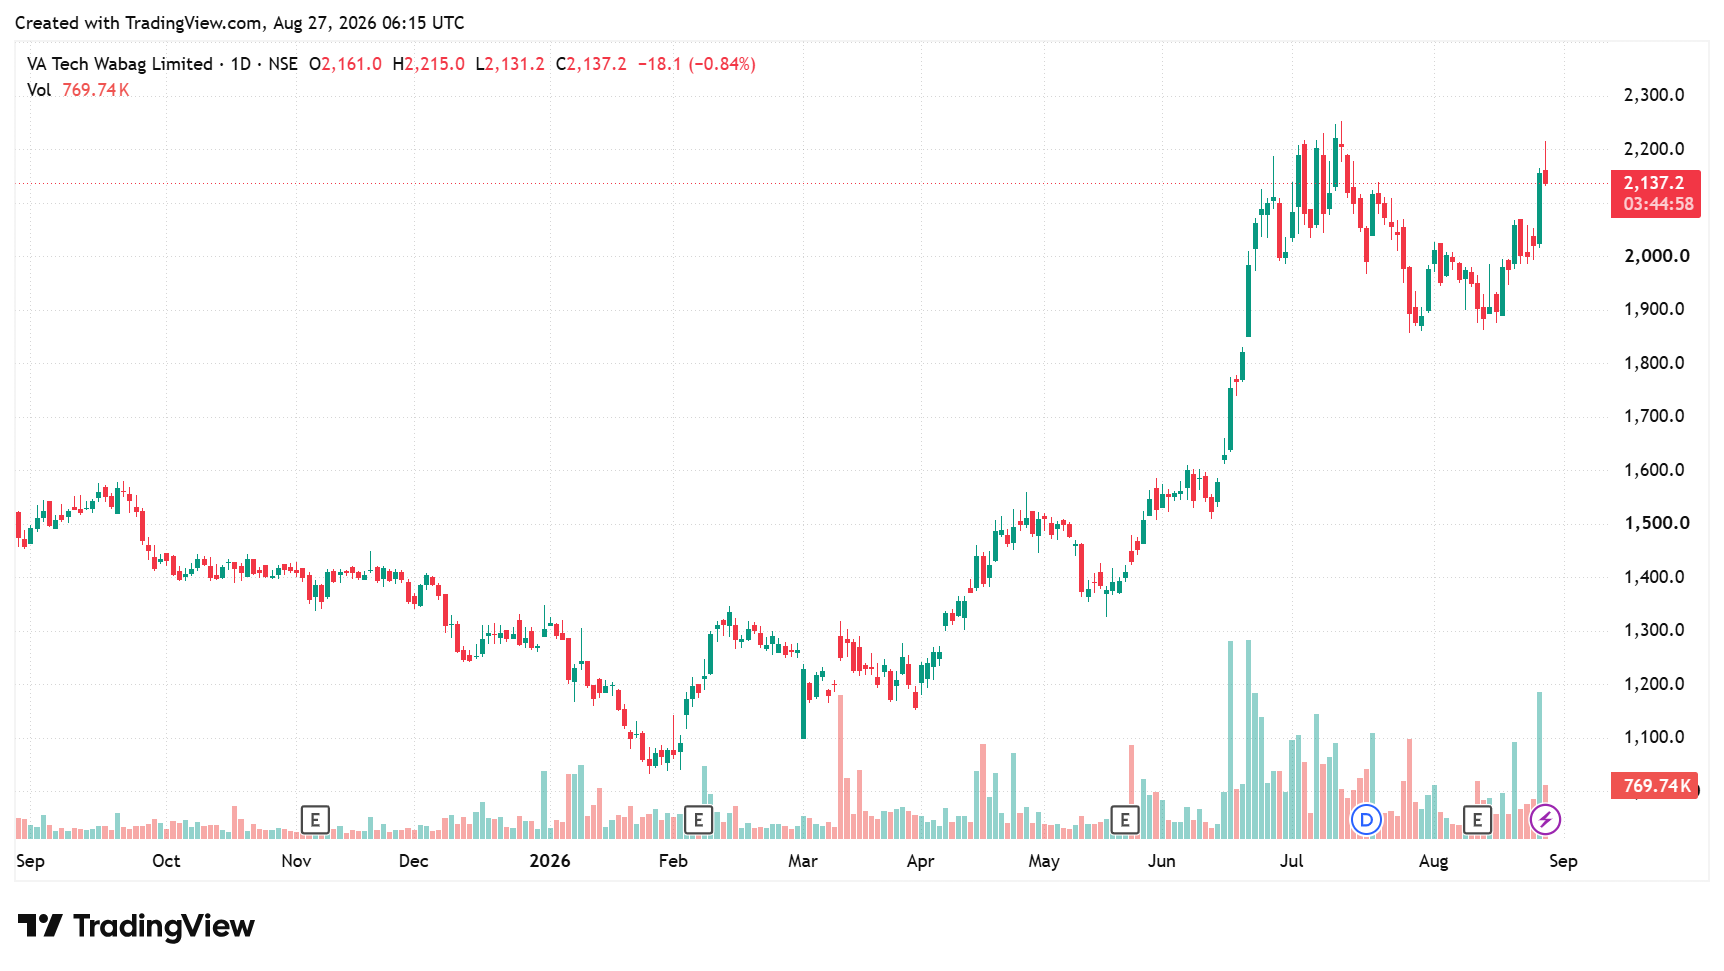
#1 Va Tech Wabag: Riding India’s High-Tech Water Demand
Va Tech Wabag is a pure-play water technology company. The company ranks among the top three private operators globally and the top three desalination players. Management has explicitly stated that it has no near-term plans to diversify outside the water domain.
They believe the global water market provides more than enough opportunity to sustain their long-term growth targets. WABAG’s operations span 5 domains of water management: drinking water treatment, wastewater treatment, recycle-reuse, desalination, and industrial water treatment.
Why Increasing O&M Share is the Key to Sustained Margin Growth
The company provides both engineering, procurement, and construction (EPC) and operations and maintenance services (O&M). This allows it to capture value not only from plant installation but also from recurring revenue from plant maintenance. O&M contracts command relatively higher margins and carry low risk.
Currently, O&M contributed 18% to Q1FY27 revenue. Management aims to increase the O&M share to 20% in the medium term. Currently, municipal projects contribute 75%, while industrial clients contribute the remaining 25%. The business is not dependent on any one place. India and the rest of the world contribute 48-52%.
Tapping into High-Tech: The Pivot to Semiconductors, Solar, and Bio-CNG
For Wabag, Semiconductors, Solar PV cells, data centres, green hydrogen and artificial intelligence are five emerging high-tech sectors. WABAG will deliver end-to-end setups from raw water treatment, Ultra-Pure Water, and Effluent Treatment to long-term O&M. It has started securing desalination orders from the PV Solar Sector.
This includes a 100 million litres per day (MLD) desalination project for Indosol in Andhra Pradesh, India, which is a major project in the company’s existing order backlog. Wabag won a breakthrough order to deliver water treatment systems for a Solar Cell Manufacturing Facility.
As these businesses grow, revenue from industrial clients could become a major part of its revenue. The company is also expanding into Bio-CNG. To this end, the company has established a strategic alliance with Peak Sustainability Ventures to implement 100 CBG plants in India.
De-Risking the Revenue Model Through Sovereign-Backed Global Projects
It bids on mega sovereign-backed and multilateral development bank projects. For instance, the company is executing the Looped Water Grid (Chennai) funded by the Asian Development Bank. The World Bank backs another advanced water reuse project in Bangalore.
The company is executing multiple projects in the Middle East and Africa region. Contracts in Saudi Arabia, such as the Yanbu Desalination Plant AI Haer, Ras Tanura, and Al Jouf Plant, are backed by the Saudi Water Authority.
Analysing the ₹19,394 Crore Backlog and Q1FY27 Financial Surge
As of 30 June 2026, the order backlog stood at ₹19,394.2 crore. EPC business accounted for 66% (₹12,728 crore) of the order book, and O&M for 34%. The EPC order book provides revenue visibility of about 3 years, based on FY26 revenue of Rs 3,944 crore. The company is targeting an order book at 4X revenue.
Wabag aims to grow its revenue at a CAGR of 15-20% over the next three to five years. The company is also targeting EBITDA margins of 13-15% and net cash positive (₹964.9 crore as of Q1FY27). The company also reported strong financial performance in Q1FY27.
Revenue rose 20.8% year-on-year to ₹886.8 crore in Q1FY27, driven by order book execution. EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortisation) surged 21.7% to ₹116.3 crore while margins stood at 13.1%. Net profit grew 36.9% to ₹90.1 crore.
#2 Ion Exchange: Positioning for India’s Ultra-Pure Water Boom
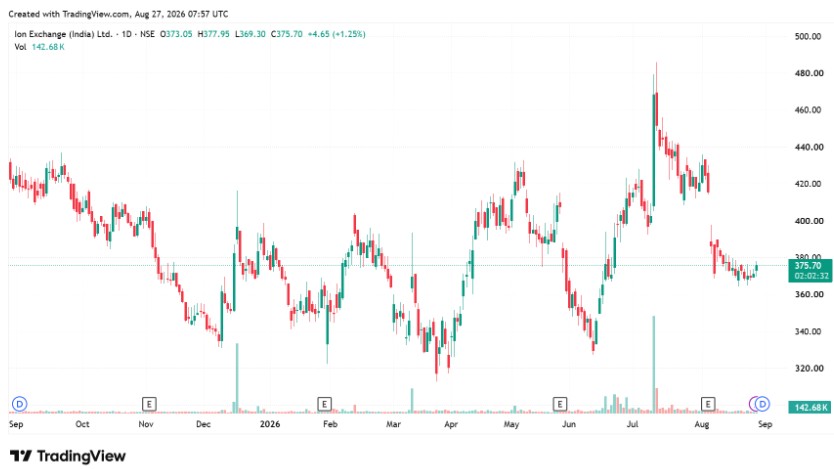
Ion Exchange provides total water and environment management solutions. Its comprehensive portfolio ranges from source water pretreatment to water and industrial wastewater treatment, recycling, zero-liquid discharge, sewage treatment, and drinking water purification. ION has recently restructured its reporting to five business segments.
Treatment Solutions delivers water treatment projects to industrial, municipal, and international markets. The Industrial Products segment designs systems and components for modular plant setups. The Lifecycle Services segment provides water service networks, including O&M. The other two segments are Consumer Products and Specialty Chemicals.
Expanding into High-Tech: Semiconductors and Ultra-Pure Water
Ion provides specialised ultra-pure water systems to semiconductor industries. This is not a new niche for the company. Ion completed an ultra-pure water project for a semiconductor complex (SCL Mohali) nearly 30 years ago. Management has been actively bidding on upcoming semiconductor projects in India over the past year.
Ion recently secured a semiconductor application project with a partner. The company offers end-to-end solutions, including setups, advanced condensate polishing, specialised membrane filtration, and chemical recovery solutions. Similarly, the company is leveraging its Roha manufacturing plant to produce specialty resins.
This product is designed for ultrapure water polishing in the solar and electronics manufacturing services (EMS) sectors. Further, Ion offers dedicated cooling water chemistry, utility softening, and high-efficiency RO plants to protect thermal loops in data centre facilities.
Q1FY27 Financial Strain: Why Margins More Than Halved
In Q1FY27, the company’s operating income grew by 20% year-on-year to ₹701 crore. All-round performance drove the growth, with double-digit growth across all five segments. However, EBITDA fell by 49% to ₹32 crore as margins more than halved to 4.5%. Consequently, net profit crashed by 93.6% to ₹3.1 crore.
Specialty Chemicals business impacted profitability with the segment EBIT down 52% to ₹22 crore. Higher input costs and underutilisation of the Roha plant weighed on margins, with the latter impacting margins by around 6%. In addition, the foreign exchange benefit seen last year, which had supported margins by 3-4%, was absent this quarter.
Legacy Projects and Cost Overruns Weigh on Profitability
Additionally, margins in the Treatment Solutions business are being severely eroded by cost overruns on some large-value legacy EPC contracts, particularly the UP water project. The Consumer Products business also reported a loss of ₹34 lakh on revenue of ₹112 crore during the quarter. The segment aims to achieve break-even by the end of FY27.
Meanwhile, the Industrial Products business grew revenue by 14% and EBIT by 145%. The Lifecycle Services business grew revenue by 28% and EBIT by 22%. The company’s order book stood at ₹2,473 crore as of June 2026. The order book has reached nearly ₹2,980 crore, including an order from Hyundai Engineering worth approximately ₹506 crore (US$52.8 million).
Strategic Bidding: Rebuilding the ₹2,980 Crore Order Book
The bid pipeline is ₹9,777 crore. The company is repositioning its largest engineering business. The unexecuted portion of UP projects accounts for 11% of the order backlog until June 2026. Management is now selectively bidding for high-margin, complex projects under a more conservative risk framework (such as the Hyundai contract).
Evaluating Capital Efficiency: Premium Valuations vs Industry Medians
Va Tech Wabag boasts strong Return on Capital Employed (ROCE) and Return on Equity (ROE) due to its faster growth of late. Ion Exchange’s business is burdened by legacy water projects, which impacts profitability even though revenue has grown consistently.
Profit compression has pushed up its valuation because the denominator is smaller. Right now, Ion trades at a price-to-earnings multiple of 49.2x, a premium to its peer Va Tech Wabag, its own 3-year historical median, and the industry median. Meanwhile, Wabag is also trading at a premium to both the industry and historical median, owing to its strong order book.
| Peer Comparison (X) | ||||
| Price-to-Earnings Multiple | Return Ratios | |||
| Company | Company | 3Y Median | ROCE (%) | ROE (%) |
| Va Tech Wabag | 33.3 | 29.0 | 21.3 | 15.9 |
| Ion Exchange | 49.2 | 37.8 | 14.1 | 12.2 |
| Industry | 18.9 | 20.4 | 16.5 | |
| Source: Screener.in (As of 26th August 2026) | ||||
As India aggressively scales semiconductors, AI, data centres, and green hydrogen, water has quietly become a critical technology bottleneck. This has created an opportunity for specialised water infrastructure companies. Va Tech Wabag offers a stable, high-growth play.
With a robust ₹19,394 crore order book, sovereign-backed projects, and a strategic shift toward high-margin O&M contracts, it justifies its premium valuation through strong execution. Conversely, Ion presents a turnaround opportunity. Despite deep expertise in ultrapure water systems, it is currently burdened by legacy project cost overruns and margin compression.
Meanwhile, it’s worth keeping these on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives and resources, and only after consulting any independent advisors as necessary.