



India’s shipbuilding industry is at an inflection point. A ₹1.5 lakh crore defence order pipeline is building up, while the government is aggregating demand for 400+ commercial platforms. At the same time, the government has approved ₹69,725 crore in support to strengthen the domestic shipbuilding ecosystem.
This includes ₹24,736 crore in financial assistance for shipbuilding, a ₹25,000 crore Maritime Development Fund, and a ₹19,989 crore outlay to expand shipbuilding capacity. The support aims to improve the competitiveness, financing and capacity of Indian shipyards. But the opportunity is not without constraints.
India has only around five to six major shipyards competing for large defence contracts, while several existing yards lack the infrastructure to build larger commercial vessels. The industry still remains dependent on imports for critical systems. This is despite 100% indigenisation achieved for hull construction, 60% in weapons and sensors, and 70% in safety systems.
This policy support is crucial for the domestic shipbuilding industry, which is targeting 100% indigenisation in the next 5 to 10 years. Against this backdrop, this article examines two major Indian shipyards.
Join now
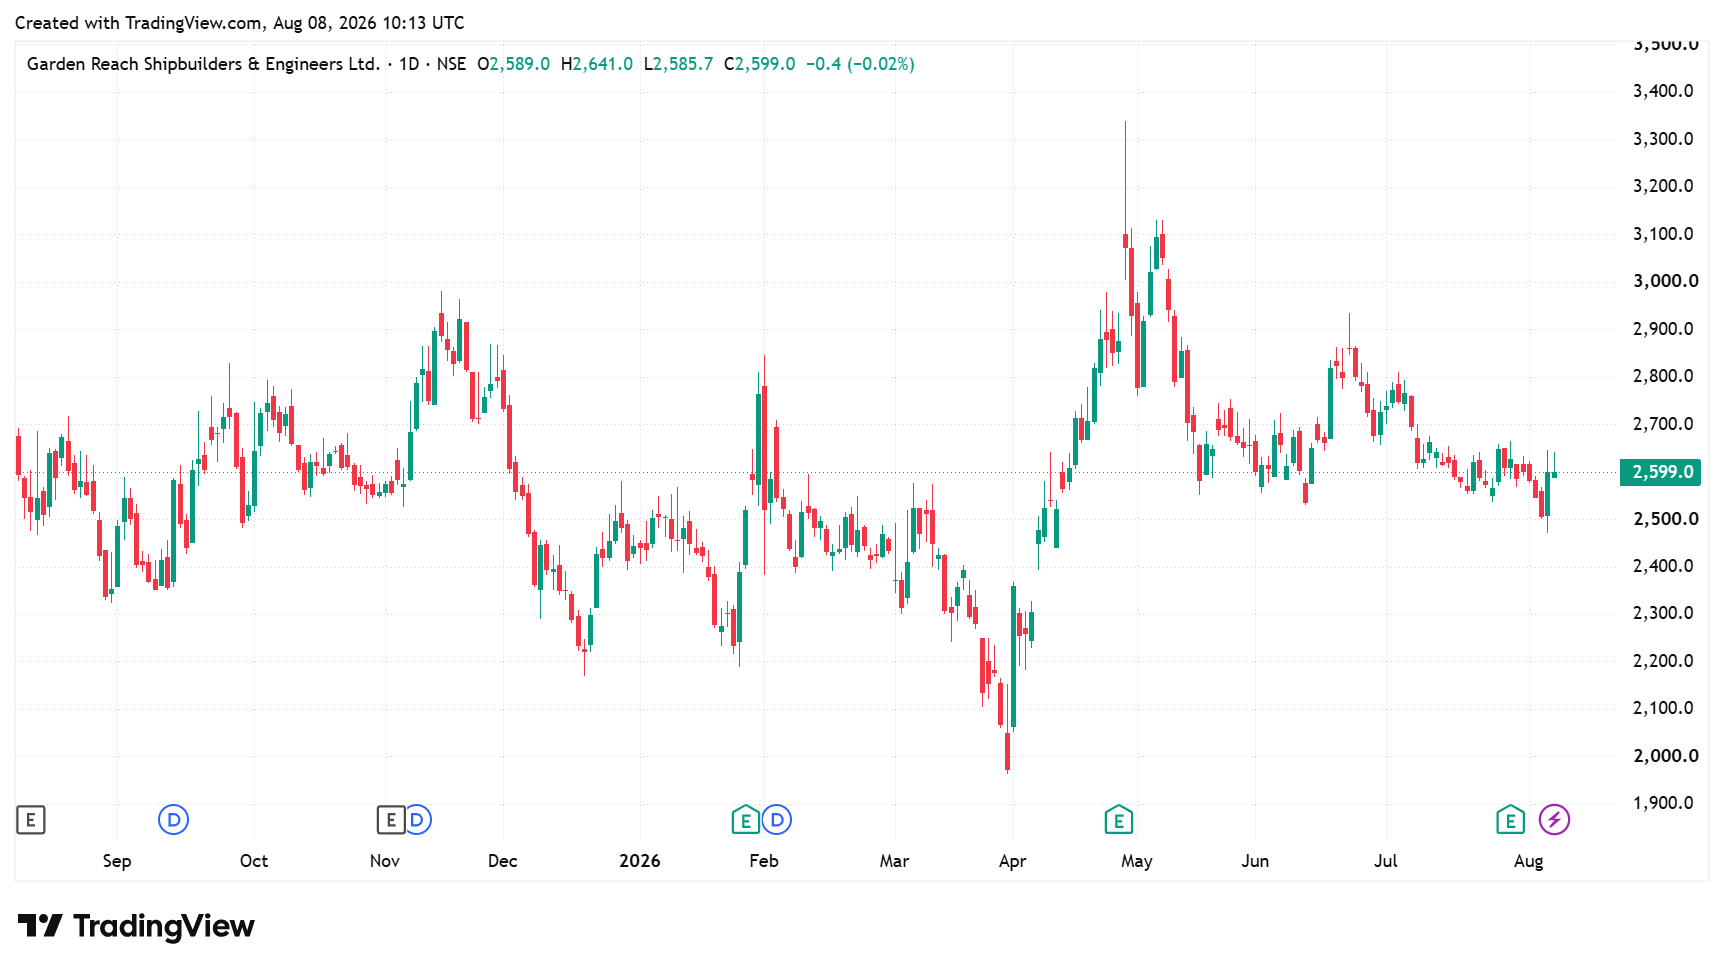
#1 Garden Reach Shipbuilders & Engineers: Just Hit a 17-Quarter Winning Streak
Garden Reach Shipbuilders & Engineers (GRSE) is one of India’s leading defence public sector shipyards. On 19th June 2026, the Government of India awarded the company Navratna Status, reflecting its consistent financial and operational performance over the years. To date, GRSE has delivered 118 warships globally, the highest delivered by any Indian shipyard.
While shipbuilding has been its core strength, GRSE has successfully diversified into several specialised sectors. This includes defence electronics and weapon systems (manufacturing 30mm Naval Surface Guns) and commercial shipbuilding. Backed by a strong order book, GRSE is seeing robust financial growth.
Q1 FY27 Financials: Accelerating Execution
Revenue increased by 38.5% year-on-year to ₹1,814.6 crore as order execution accelerated. This marked its 17th consecutive quarter of upward growth. EBITDA grew by 34.9% to ₹248.8 crore, while margins declined 37 bps to 13.7%. Net profit surged by 43.8% to ₹172.8 crore, aided by a 37% jump in other income.
Navigating a Shifting ₹13,500 Crore Order Book
GRSE’s current order book stands at ₹13,596.3 crore, comprising 11 projects totalling 44 marine platforms. Of this, the shipbuilding division contributed over 95% (₹12,980 crore). While historically almost all orders were defence-related, it has successfully diversified its order book.
Now, the non-defence segment contributes 25%, which includes export orders and special research vessels for various ministries. Major ongoing projects include P17 Alpha (scheduled for delivery in November 2026), Anti-Submarine Shallow Water Craft (completion in FY27), and Next-Generation Offshore Patrol Vessels (deliveries expected to begin from Q2FY28).
In addition, GRSE is building 12 multi-purpose vessels for a German client, a fully electric hybrid ferry for the Government of West Bengal and a trailing suction hopper dredger for Bangladesh. That said, the order book has fallen below ₹15,000 crore for the first time in 10 years. Management attributes this to high physical execution and delivery.
The ₹1.5 Lakh Crore Defence Pipeline
However, the active pipeline could replenish the order book once again. Management projects a defence order pipeline of about ₹1,50,000 crore in the near term. Out of this, five live defence tenders worth ₹80,000+ crore are already active in the market. This includes a major P75 Bravo Warships contract worth ₹70,000 crore.
If GRSE secures this order, its order book will increase significantly. Further, GRSE expects two large, major Requests for Proposals (₹71,000 crore) in 2026. The first is for 12 mine countermeasure vessels (₹36,000 crore). This order will likely be split between two shipyards. Another is the ₹35,000 crore landing platform docks project.
The company is also expanding its product portfolio in line with India’s indigenous goals. GRSE has proven prototypes for an Unmanned Surface Vessel (USV) and an Autonomous Underwater Platform (tested in Pangong Lake). The shipyard has been shortlisted for another Navy project for an unmanned underwater platform and is participating in the Navy’s projects.
Commercial Expansion & Capacity Upgrades
On the commercial side, GRSE is building 13 hybrid electric ferries for West Bengal, with delivery scheduled for September, October 2026 and April 2027. It is now actively pitching water metro systems in other states, including Goa. While these are small orders (₹200-300 crore per metro system), management expects a total opportunity of ₹1,500 crore across the five states.
To support this ₹1.5 lakh crore pipeline and allow the construction of larger commercial vessels, GRSE is executing ₹4,400 crore in brownfield and greenfield capacity expansion. The company is investing ₹200 crore to revitalise two leased sites from Kolkata Port within 18 months.
A new sea-facing shipyard is expected to be fully operational in 3-5 years at a cost of ₹2,200 crore. Another ₹2,000 crore facility is expected to be commercialised by 2030. Once these plants are complete, GRSE’s concurrent construction capacity will jump from 32 to 43 platforms.
#2 Mazagon Dock Shipbuilders: The Defence Giant Awaits a ₹90,000 Crore Submarine Deal
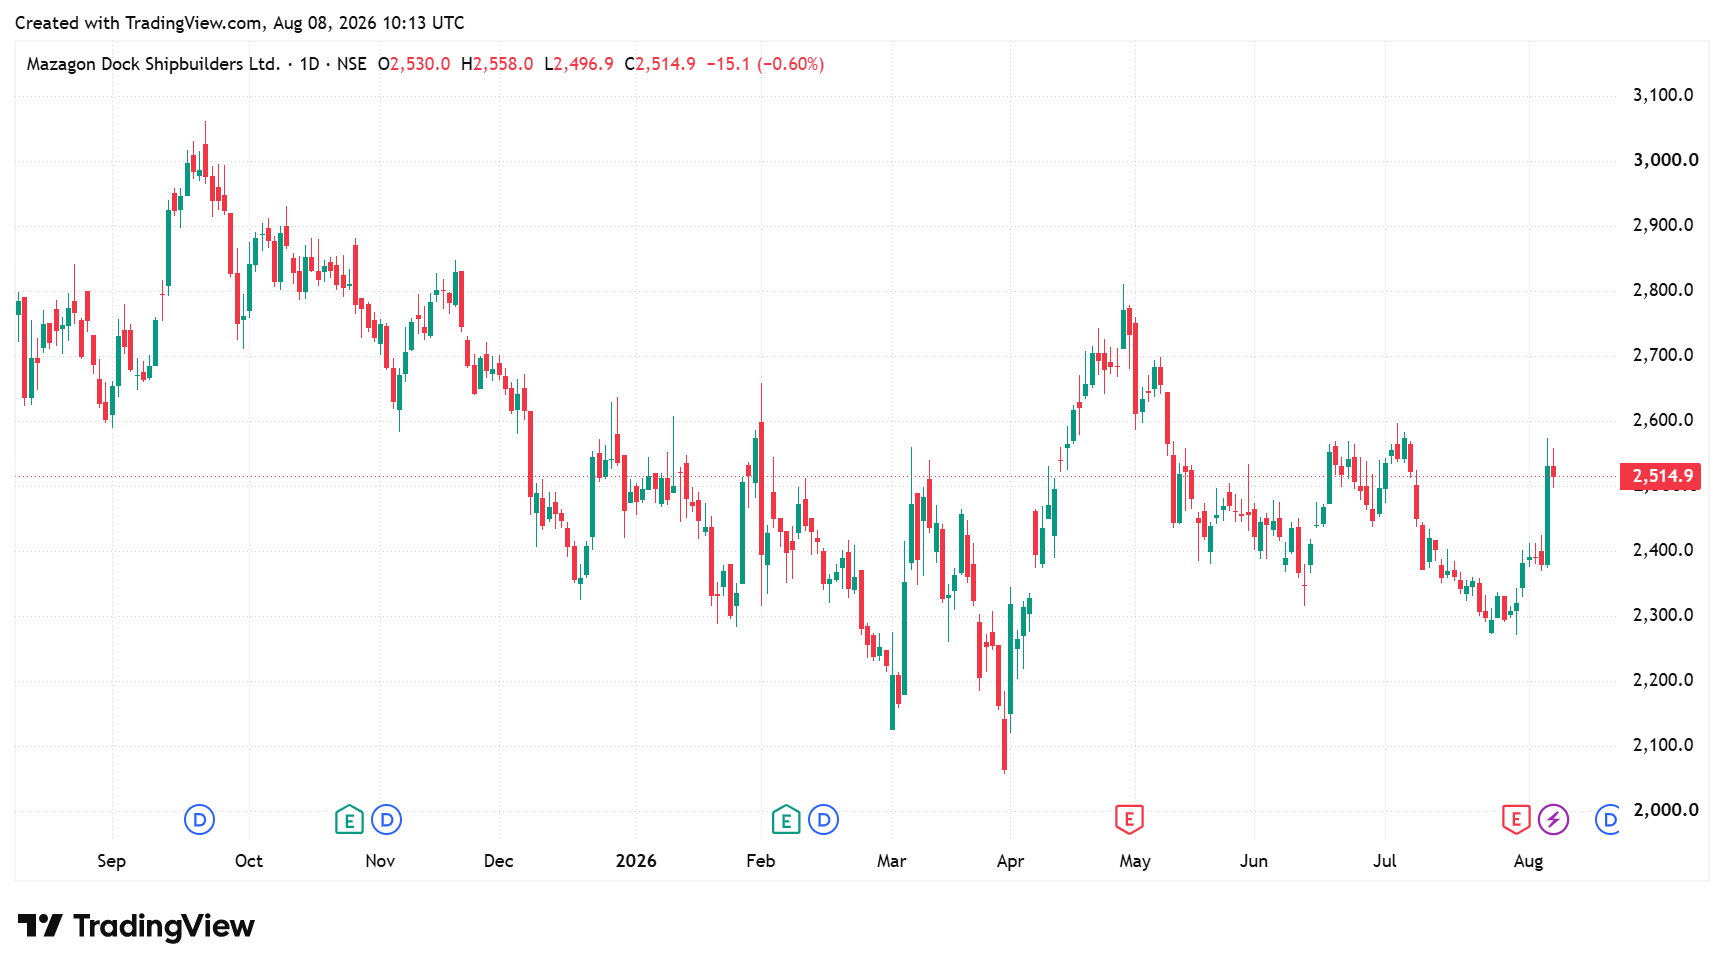
Mazagon Dock Shipbuilders (MDL) is also a ‘Navratna’ company of the Government of India. It is India’s only public sector defence shipyard that constructs destroyers and conventional submarines. The company boasts a massive concurrent building capacity capable of handling 11 submarines and 10 warships simultaneously.
Compared to GRSE, MDL’s growth has slowed down. Revenue increased 12.1% year-over-year to ₹2,943 crore. However, EBITDA rose 21.6% to ₹760 crore, while margins stood at 25.8%. Consequently, net profit grew 21.7% to ₹550 crore. As older legacy projects were completed, the execution of new orders slowed growth.
Navigating a Slower ₹18,218 Crore Order Book
MDL has a total order book of ₹18,218 crore as of June 30, 2026. This gives it a revenue visibility of around 1.4 years, based on FY26 revenue of ₹13,006 crore. It also has a large future project pipeline estimated at ₹2.9+ lakh crore, representing almost 15.9 times its current order book.
This pipeline is expected to lead to a significant recovery in the order book over the next few quarters. It has already completed contractual negotiations for six next-generation conventional submarines worth ₹90,000 crore.
The ₹2.9 Lakh Crore Catalyst Awaiting Approval
The contract is currently awaiting final approval from the Cabinet Committee on Security, which is expected to be finalised soon. This single order can increase the existing order book by 5x. Further, MDL expects three additional submarines under the P75 framework within the current fiscal year.
A request for proposal for ₹70,000 crore Project 17B Stealth Frigates is expected in FY27-28. MDL is a strong contender for this project. MDL plans to bid jointly with Swan Defence for the highly competitive ₹40,000 crore Landing Platform Docks contract. There are additional orders of around ₹ 90,000 crore in the pipeline.
Once some of these new contracts are finalised, management expects growth to resume after FY28. Meanwhile, MDL expects its revenue growth to slow. However, to diversify, it is expanding beyond domestic defence shipbuilding.
Looking Beyond Defence: Colombo Dockyard & Capacity Expansion
The company is in talks with France’s Naval Group to explore co-building Scorpene-class submarines for an undisclosed Asian export customer. MDL is aiming to establish a significantly stronger presence in constructing and servicing offshore Oil and Gas platforms. This will help the company expand its revenue base and reduce its dependence on core shipbuilding.
The acquisition of a 51% controlling stake in Colombo Dockyard during FY26 was a major step to this end. Colombo Dockyard allows MDL to achieve geographic diversification and immediately expands its commercial shipbuilding, ship repair, and outfitting capacities. It is also expanding its waterfront shipbuilding handling capacity from 80 Deadweight Tonnage (DWT) to 200 DWT.
MDL is building a greenfield shipyard. This facility will serve as a hub for both commercial shipbuilding and offshore platform fabrication. Another 12,000-ton floating dry dock was scheduled to be completed in July 2026. This plant will manage the dry-docking and repairs of future commercial and naval projects.
Q1FY27 Financial Snapshot (₹ crore)
| Particulars | Mazagon | GRSE |
| Revenue (in cr) | ₹2,943 (+12.1%) | ₹1,814.6 (+38.5%) |
| EBITDA (in cr) | ₹760 (+21.6%) | ₹248.8 (+34.9%) |
| EBITDA Margins | 25.8% | 13.7% |
| Net Profit (in cr) | ₹550 (+21.7%) | ₹172.8 (43.8%) |
| Order Book as of 30 June | ₹18,218.0 | ₹13,596.3 |
| Revenue Visibility | ~1.4 years | ~1.9 years |
| Order Pipeline | ₹2.9+ lakh crore | ₹1.5 lakh crore |
| Source: Investor Presentations | ||
GRSE delivered faster growth, while Mazagon Dock remained larger and more profitable, with stronger margins and a bigger order book but slower revenue growth. Their combined order book remains at ₹31,800 crore, which is lower than the historical peak. However, the order pipeline (over ₹2.5 lakh crore) is substantial and can replenish the order book.
A key point to note here is that the ₹2.5 lakh crore MDL pipeline overlaps with several large opportunities that GRSE is competing for.
The Valuation Gap: Execution Over Expectations
Backed by strong growth, GRSE return ratios (Return on Capital Employed and Return on Equity) are higher than Mazagon Dock. In terms of valuations, both GRSE and Mazagon Dock are trading almost at par with their 5-year historical averages, but at a discount to the industry median.
| Peer Valuation | |||||
Particulars | Price-to-Earnings Multiple (X) | Return Ratios | |||
| Company | 5Y Median | Industry | RoCE (%) | RoE (%) | |
| GRSE | 37.2 | 35.9 | 66.4 | 43.0 | 31.8 |
| Mazagon | 35.5 | 32.2 | 45.6 | 36.0 | 29.2 |
| Source: Screener.in (Source: 08 August 2026) | |||||
India’s shipbuilding opportunity is no longer just about winning defence contracts. The bigger shift is towards building scale, moving into commercial vessels and reducing dependence on imports.
GRSE and Mazagon Dock are approaching this transition differently. Although both companies have seen their order books decline from recent highs, the larger opportunity has not gone away. What matters now is how quickly they can replenish their order books and convert their large project pipelines into actual contracts.
Their ongoing capacity expansion will also play an important role, particularly as India looks to build larger vessels domestically. For investors, the next growth phase will therefore be more about execution and new order wins. It’s worth keeping them in your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. Only in cases where the data were unavailable have we used an alternate, widely accepted, and widely used source of information.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities, or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.
Editor’s Note: The reference to “P75 alpha” under the GRSE heading has been corrected to “P17A”, after the company clarified on an error in their earnings call transcript.