



Buying Like There is No Tomorrow
Investors who track disclosures rather than headlines have had an unusually clear run of them this year. Ashish Dhawan’s holding in Religare Enterprises has been reported four separate times since April, and every entry points the same way.
| Date | Stake before | Stake after | Detail disclosed |
| 17 Apr 2026 | 4.25% | 4.46% | 7,00,000 shares bought on the open market |
| Jun 2026 quarter | 4.46% | 5.24% | Market buying plus warrant conversion at Rs 235 |
| 28 Aug 2026 | 5.24% | 6.35% | 38,00,000 shares at Rs 232, worth Rs 88.16 cr |
| 31 Aug 2026 | 6.35% | 7.41% | Includes a BSE bulk deal of 19,01,448 shares at Rs 237 |
He now holds 2.53 crore shares, worth about Rs 616 cr at Monday’s close, and continues to hold warrants carrying an exercise price of Rs 235. Crossing 5% in June triggered mandatory disclosure, which means every purchase since has been visible to the market as it happened.
He kept buying regardless. Every one of these purchases sits on the exchange record, filed by the acquirer himself under the takeover code, which is why this is a rare case where a star investor’s buying can be tracked to the share rather than inferred a quarter later.
The Demerger Roadblock
Religare Enterprises has been promoter-controlled since March 2025, when the Burman family of Dabur formally entered the promoter column after a long and contested takeover. They now hold 30.55%. Under that ownership, the board approved a scheme to split the company earlier this year. Lending, broking and allied operations would move into Religare Finvest. The parent would keep its roughly 63% holding in Care Health Insurance and stay listed. Shareholders would get one Finvest share for every Religare share held.
The scheme cleared its visible hurdles. On 7th July the NSE issued a no-objection letter and the BSE recorded no adverse observations. At the end of July, SEBI closed a long-running investigation, disposing of a 2024 show-cause notice without penalty or direction. After years of litigation and regulatory overhang, the file was finally moving.
Then the central bank declined. Religare received a letter dated 6th August saying the application had been examined and the request had not been acceded to. Religare Finvest received a similar letter the following day. Neither communication, as disclosed, explains the objection. The company has not withdrawn the scheme and says it will engage with the regulator.
The Regulatory Shadow of Past Promoters
The position today is a restructuring holding every approval except the decisive one, in front of a regulator that has given no public reasoning. Dhawan has put roughly Rs 133 cr into that uncertainty in the three weeks since the rejection.
The central bank’s caution has a history behind it. Religare Finvest, the entity that would have received the demerged businesses, spent years under the RBI’s corrective action framework after the previous promoters were accused of misappropriating funds from it. That episode ended with arrests, litigation and a lending book that had to be rebuilt from near zero.
Any scheme that moves assets into that particular subsidiary was always going to attract a longer look than a routine group reorganisation. Knowing the history does not tell you what the objection was, but it does explain why a no-objection was never a formality.
The Margin Contraction Story
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5-yr CAGR |
| Sales (Rs cr) | 2,513 | 3,227 | 4,679 | 6,266 | 7,385 | 8,459 | 27% |
| Operating Profit (Rs cr) | 278 | -364 | 483 | 368 | 356 | 136 | NM |
| Operating Margin | 11.1% | -11.3% | 10.3% | 5.9% | 4.8% | 1.6% | |
| Net Profit (Rs cr) | -478 | -1,539 | 3,169 | 347 | 183 | 73 | NM |
Operating profit is shown rather than EBITDA, which is not a meaningful measure for an insurance-led financial group. CAGRs are marked NM (not meaningful) because FY21 was a loss year and the operating line changes sign. The Rs 3,169 cr printed in FY23 rests on a one-off gain of roughly Rs 3,473 cr tied to the old lending book.
The margin row is the one to sit with, and it is the row that explains everything else. Revenue compounded at 27% a year over five years. Over the same stretch, operating margin fell from 11.1% to 1.6%, and on a trailing twelve-month basis it is now 0.7%. Operating profit in absolute terms is roughly half what it was in FY21 while revenue has more than tripled.
The June 2026 quarter carried that trend forward. Consolidated income rose about 26% to Rs 2,358 cr, and the company posted a net loss of Rs 47 cr against a Rs 8 cr profit a year earlier. The December 2025 quarter was a Rs 77 cr loss. Two of the last three quarters have been in the red, and the trailing twelve-month profit is down to Rs 18 cr.
The balance sheet has been moving too. Consolidated borrowings roughly doubled to Rs 493 cr in FY26 from Rs 233 cr, investments grew to Rs 11,203 cr and total assets to Rs 14,506 cr. Cash from operations was Rs 1,820 cr for the year, which for a group with an insurance float at its centre reflects premium collection as much as trading profitability.
Working capital days remain deeply negative, which is what an insurance-led structure looks like when premiums arrive before claims are paid.
Unpacking the Sum of the Parts
Open up that quarter by segment and the group divides cleanly. Financial services delivered a pre-tax profit of Rs 13.3 cr, with Religare Broking growing its post-tax profit 65%. Insurance delivered a pre-tax loss of Rs 87.3 cr. That line is the one almost every report has misread, and it is worth slowing down on.
Care Health is not the problem in any commercial sense. Gross written premium grew 37% to Rs 3,247 cr in the quarter and its own profit before tax rose 59% to Rs 163 cr. It holds roughly a quarter of the standalone health insurance segment. Its investment book has reached Rs 11,751 cr, which is more than the market capitalisation of the listed parent that owns it. It raised Rs 150 cr through a rights issue during the quarter and a further Rs 200 cr of Tier II capital in August.
Capital Flows and Core Value
The parent has been feeding capital downward on several fronts at once. Beyond Care Health’s rights issue and Tier II raise, Religare Broking was allotted 4.21 crore shares against a Rs 100 cr rights issue on 21st August.
For a holding company that reported a standalone loss of Rs 9.6 cr for the June quarter, that is a lot of money moving into subsidiaries while the parent itself earns almost nothing on its own account. It is also a reasonable clue about where management believes the value is being created.
So how does a subsidiary earning Rs 163 cr show up in the parent’s accounts as a Rs 87.3 cr loss? The answer is not underwriting. It is accounting.
The combined insurance service ratio did sit above 100 at 102.7%, but it moved the right way, improving 30 basis points from 103.0% a year earlier. That is not a business losing control of claims. It is a health insurer buying share while holding its cost line steady.
The roughly Rs 250 cr gap between Care’s own profit and the segment loss reported at group level comes from Ind AS 117, the new insurance contracts standard, and the way premium, expense and reserve recognition are restated when the insurer is consolidated into a non-insurance parent. Under the new rules, premium volume no longer drives the top line in the way it once did, and the timing of when profit is recognised shifts. Investors who read only the consolidated line are reading an accounting artefact and calling it a business problem.
A Flatlining Valuation Profile
Here is the number that frames the whole story. The Burman family’s open offer in September 2023 was priced at Rs 235. Dhawan’s warrants carry an exercise price of Rs 235. He bought at Rs 232 last Friday and Rs 237 on Monday. Three years have passed and the market has settled on almost exactly the same figure.
The longer record agrees. Over ten years the share price has compounded at minus 1% a year. Over three years it is flat. Over one year it is down about 2%. The 52-week band sits between Rs 197 and Rs 285.
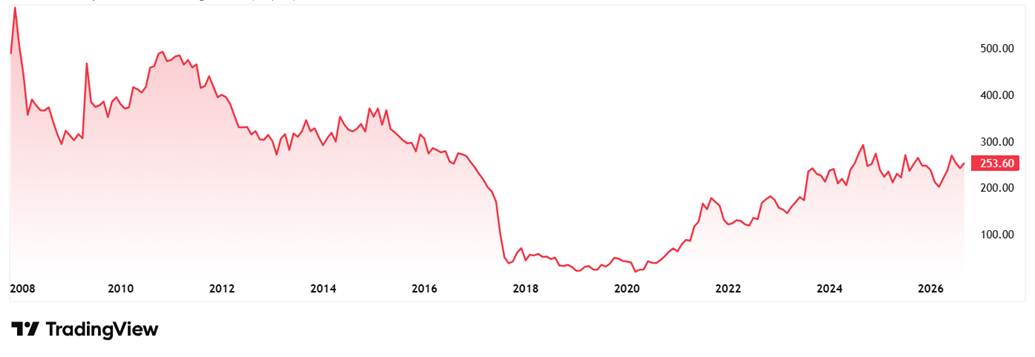
Regarding valuations, the share trades at a PE of 176 currently, which is much higher than the current industry median of 25x. The 10-year median PE for the company is 73x while the industry median for the same period is 21x.
Return on equity is 3.17% and return on capital employed 3.06%. No dividend has been paid in any of the last twelve years. Both those medians deserve a caveat: the company reported losses in six of the last twelve years, so any long-run earnings multiple for this name is built on a broken series and should be read as an indication rather than a benchmark.
The Endgame on the Register
Nobody commits Rs 616 cr to a 0.7% operating margin. The purchase only makes sense as a bet on the parts rather than the whole.
Strip the description back and Religare is a holding company whose principal asset is a majority position in a health insurer compounding premiums at 37% with about a quarter of its niche. That insurer sits inside a listed shell whose consolidated accounts turn its profit into a loss, paying nothing out, earning 3% on equity and trading on a multiple that carries no information. The demerger existed to separate the two so each could be priced on its own terms. The central bank has, for now, refused to allow it.
Dhawan’s 7.41% stands against the promoters’ 30.55%, on a register where foreign and domestic institutions combined hold under 19%.
He also has room to keep going: the open offer trigger under Indian takeover rules sits at 25%, so nothing in the last four months has taken him close to a threshold that would force his hand. Seen that way, the timing stops looking odd.
Religare Is Now His Biggest Position on the Register
One more thing puts the last four months in perspective. Dhawan runs a concentrated book of a dozen or so disclosed holdings, mostly financials and mid-cap industrials, worth roughly Rs 2,500 cr. Until April, Religare was a mid-sized position in it. It is not any more.
| Company | Disclosed stake |
| Religare Enterprises | 7.41% |
| Palred Technologies | 5.54% |
| Quess Corp | 4.85% |
| AGI Greenpac | 4.79% |
| Equitas Small Finance Bank | 4.02% |
| Greenlam Industries | 3.77% |
| RPSG Ventures | 3.73% |
| Northern Arc Capital | 2.17% |
No other listed company on that list carries a bigger percentage of his money than the one the Reserve Bank just blocked.
The Stand-Off Window
A buyer who believes the value sits in Care Health, and that the scheme is delayed rather than dead, has been handed a window. The bad news is already public and the price has not moved. The scheme has not been withdrawn. And the register is unusually thin.
Foreign institutions have gone from 11.75% in September 2023 to 9.64%. Domestic institutions have slipped from a peak of 13.43% to 9.33%. The shareholder count has fallen from 85,873 to 69,935. Fewer holders and thinner institutional presence mean less resistance to a buyer working steadily through the order book.
Three things would settle the question. The RBI could explain its objection. The company could disclose what it has been asked to fix. Or the scheme could be redrawn in a form the regulator will accept. None of the three has happened, and no timeline has been offered for any of them.
Until one arrives, shareholders own an asset whose value turns on a decision nobody outside the central bank can currently read. That is an uncomfortable place for most investors and evidently not for this one. The most informative document on this company right now is not its profit and loss account. It is the running tally of one investor’s filings, and that tally has moved four times since April. Adding this stock to a watchlist looks like a sensible thing to do right now.
Disclaimer
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.