



Shareholding filings are the closest thing retail investors get to a live feed on India’s sharpest money. They arrive late, incomplete, and they are read far too literally.
This month has handed us two clean examples. A company listed on 24th August 2026 with Radhakishan Damani in its register from day one. And the June 2026 filing for another one shows Bright Star Investments, the vehicle through which the Damani family holding there is tracked, back among the disclosed public shareholders after two quarters away.
Let us dive into both these stocks.
#1 Horizon Industrial Parks: The Pre-IPO Reality Check
Incorporated in 2009, Horizon Industrial Parks is the warehousing platform Blackstone assembled in India over more than a decade. It builds and leases large modern sheds. Fulfilment centres for e-commerce, factory space for manufacturers, and in-city units for last-mile delivery. Blackstone entities hold 75.4% after the listing.
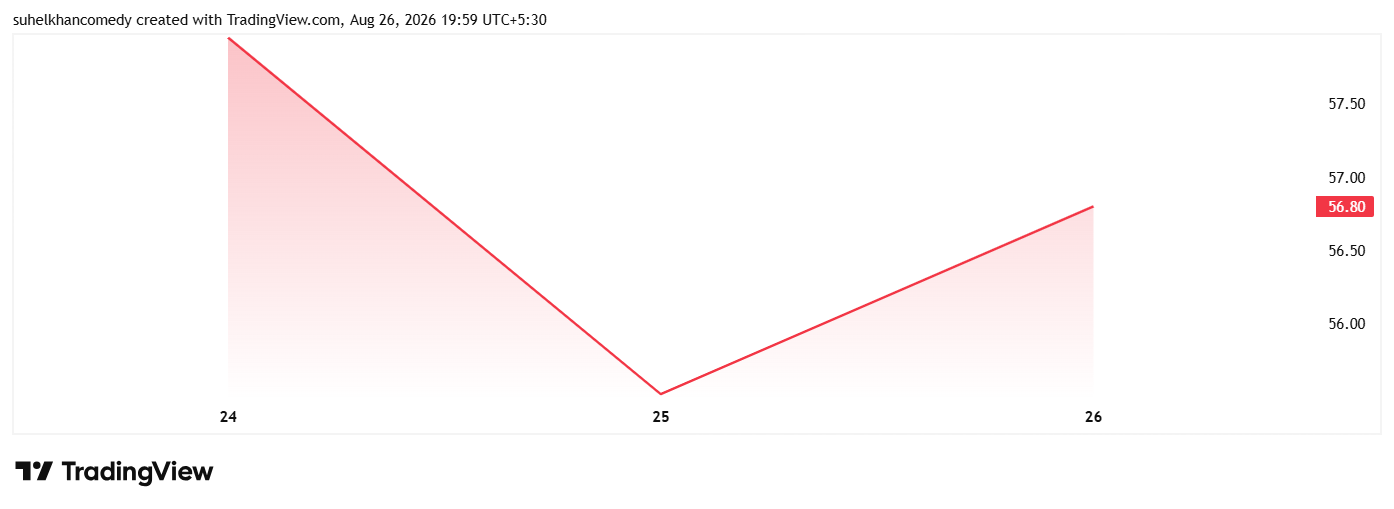
It raised Rs 2,600 cr in a pure fresh issue at Rs 57 to Rs 60 a share, listed on 24th August and closed at Rs 58.8 on 26th August. That values it at Rs 16,393 cr, the ninth largest listed real estate company in India on the day it arrived.
Join now
Decoding the Rs 1,650 Crore Private Placement
Here is the detail almost every listing-day write-up skipped. Damani’s 1.16% did not come from the public issue. It came from a Rs 1,650 cr private placement completed in December 2025, months before the offer document was filed.
The register proves it. Sitting alongside Damani in the August 2026 filing are 360 One’s two real assets funds at 1.99% and 1.31%, and SBI Life Insurance at 1.45%. Same names, same round, 5.91% of the company between them. The balance sheet shows the money landing too, with reserves up from Rs 472 cr in March 2025 to Rs 3,215 cr in March 2026.
So, this is not a man reading a prospectus and backing a debutant. It is a man who took a pre-listing position, waited eight months, and then had the market discover him. At the current price the holding is worth about Rs 187 cr. Against an issue price of Rs 60, it is under water.
What makes the stake worth watching is not its size but its share of what actually trades. Public shareholders hold just 6.97% of Horizon, worth about Rs 1,121 cr. Damani alone is 16.6% of that free float, a sixth of everything genuinely in public hands.
Behind the Margins: Horizon’s Heavy Debt Burden
Let us look at the company’s financials to get a better understanding why the story might be even more different than one might think.
| Financial Year | FY23 | FY24 | FY25 | FY26 | 3Y CAGR |
| Sales (Rs cr) | 151 | 234 | 390 | 691 | 66% |
| EBITDA (Rs cr) | 19 | 137 | 290 | 531 | NM |
| Net Profit (Rs cr) | -151 | -139 | -179 | -204 | NM |
EBITDA here refers to operating profit before other income. Two notes. There are only four years of data, so no five-year CAGR is possible. And the EBITDA growth is marked not meaningful on purpose. The FY23 base of Rs 19 cr carried an operating margin of 13%, against 59% the next year, so compounding off it flatters rather than informs.
Sales grew 55%, 67% and 77% in the last three years, and operating margin now sits at 77%, which is what a well-let warehouse portfolio should look like. The company has still lost money every year, with the loss widening each time.
The reason sits in the two lines below operating profit. In FY26, interest cost Rs 539 cr and depreciation Rs 266 cr, against operating profit plus other income of Rs 607 cr. Interest alone swallowed the whole operating profit. Borrowings were Rs 6,904 cr against a net worth of Rs 5,665 cr.
That is what the Rs 2,600 cr fresh issue is meant to fix. Every rupee is company money, with no selling shareholder taking cash off the table, and most of it is earmarked for repaying debt. Cut the interest bill and the same rent roll starts earning. That is the case, and the risk.
Valuation Realities for a Loss-Making Giant
You will not find a PE multiple for Horizon. The company has never reported an annual profit, so the ratio does not exist, and nor does a ten-year median, because there is no ten-year history to compute it from.
The industry median currently is about 26x. What can be measured is that Horizon trades at about 2.8 times its March 2026 net worth, on a return on capital employed (ROCE) of 3.2%.
One more thing worth noting is that the company closed its trading window on 24th August, the day it listed, and said it reopens 48 hours after the June 2026 quarter results. The only quarterly numbers in the public record are from June 2025. Horizon has not yet reported a quarter as a listed company.
#2 Sundaram Finance: Tracking the 2.37% Phantom Stake
Incorporated in 1954, Sundaram Finance is one of India’s oldest deposit-taking non-banking lenders. It started by financing commercial vehicles for Chennai truck operators and never left that business, adding home finance, asset management and insurance around it over seven decades.
The June 2026 filing puts Bright Star Investments back on the disclosed shareholder list at 2.37%, after being absent in December 2025 and March 2026. On the face of it, a sale and a re-entry.
Why the ‘Sale and Re-entry’ Narrative Doesn’t Add Up
Look at what the register shows across three years. Bright Star appears at 2.37% in September 2023, and at 2.37% in every filing it appears in since, through to June 2026. The same figure to two decimals, every time.
It has vanished before, too. The name is missing from the March 2025 filing, then reappears in June 2025 at exactly 2.37%.
Consider what a genuine round trip involves. The company has about 11.1 crore shares outstanding, so 2.37% is roughly 26.3 lakh shares, worth close to Rs 1,200 cr today. Selling that block and buying back the exact same quantity, twice, landing on the identical percentage each time, is not how large positions behave.
Now check the totals, which is where the reading settles. A 2.37% block that changed hands had to go somewhere. Total public holding was 35.55% in September 2025, then 35.43%, 35.34% and 35.43%. That is a swing of 0.21 percentage points against a 2.37% stake. Foreign holding fell over the same stretch, from 19.13% to 18.58%. Domestic institutions rose 0.57 points.
No buyer in that pattern is large enough to have absorbed the block, and there is no seller shaped hole where it left. The reading that fits is the boring one. The position did not move, and the name was simply not itemised in two filings. Only the underlying filings settle it, but the aggregates point one way.
This matters beyond one stock. A name leaving a disclosed list is not a sale, and a name returning is not a purchase. Both get reported as trades.
Record Quarters Masked by Filing Noise
Behind the filing noise, the business has been doing something worth noticing.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Revenue (Rs cr) | 5,292 | 5,111 | 5,501 | 7,274 | 8,513 | 9,852 | 13% |
| Financing Profit (Rs cr) | 1,398 | 1,483 | 1,806 | 2,224 | 2,620 | 2,980 | 16% |
| Net Profit (Rs cr) | 1,223 | 1,296 | 1,510 | 1,842 | 1,879 | 2,059 | 11% |
For a lender, financing profit replaces EBITDA. It is revenue less interest paid out and less operating expenses, the closest measure of what the business earns before depreciation and tax. The CAGRs above run off audited FY21 and FY26 figures, so they differ slightly from versions anchored to trailing twelve-month numbers.
The June 2026 quarter was the best in the company’s recent record. Revenue of Rs 2,644 cr, up 13%. Financing profit of Rs 818 cr, up 30%. Net profit of Rs 636 cr, up 34%, and the highest of any quarter in three years, beating the previous best of Rs 554 cr.
The share price of Sundaram Finance was about Rs 2,590 in August 2021 and it closed at Rs 4,540 on 26th August 2026, against a 52-week high of Rs 5,642 and a low of Rs 4,000. It is about 19% below that high and down 7% over a year, in the same stretch that quarterly profit hit a record. Over five years the price compounded at 12%, so this is a de-rating inside a long uptrend.
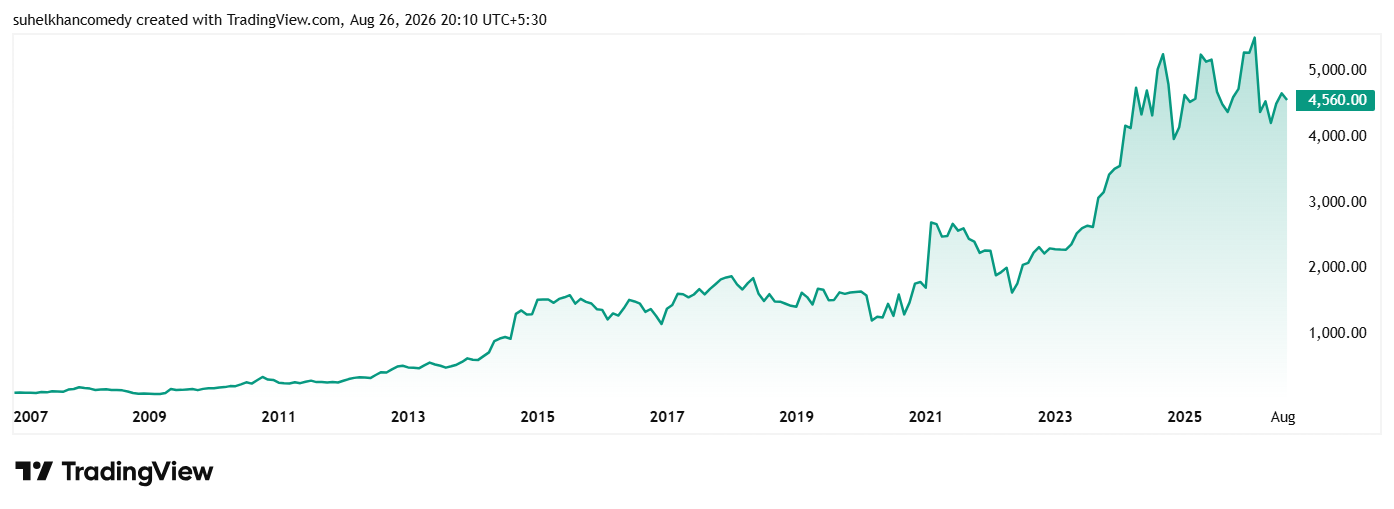
Valuation De-rating Inside a Long Uptrend
The stock trades at a PE of 22x currently and the industry median is about 19x. The 10-year median PE for the company is 24x while the industry median for the same period is 22x.
Borrowings have compounded at about 14% a year over five years to Rs 69,636 cr, which is what growth costs a lender, and interest coverage is thin across the sector. Ownership has also been rotating hard. Foreign holding climbed from 8.35% in September 2023 to above 19% before easing to 18.58%, while domestic institutions went the other way, from 16.55% to 7.37% and back to 8.00%.
Read the Data, Not the Narrative
Put the two together and many things become clear.
In Horizon, an investor appears on a register on listing day and the natural conclusion is that he backed the issue. He did not. He wrote the cheque eight months earlier at a privately negotiated price, and sits below what the public paid.
In Sundaram Finance, a name goes missing and returns, and the natural conclusion is a sale and a purchase. The totals say otherwise, and the same disappearance had already happened a year earlier without anyone calling it a trade.
The two businesses could hardly be less alike. One is a seven-decade old lender with a record quarter. The other is a three-day old listing with a growing rent roll, heavy debt and no profit to value it on. What connects them is that both have had a story attached that the numbers do not support. And both are backed by one of the biggest investors of India.
Filings are evidence, not narrative. The percentages are facts. What gets read into the gaps between them is interpretation, and that is where the damage happens. A sensible way to stay across this is to add these stocks to a watchlist and read the next filings closely.
Disclaimer: Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.