



Profits are important. But profit does not always translate into cash. A company may report rising earnings while its money remains tied up in receivables, inventory or heavy capital expenditure. Free cash flow offers a tougher test. It shows how much cash remains after the business has paid for its operations and investments.
So, we set off to find companies that are cash rich. Specifically, relatively smaller companies. The starting point was a screen that selects companies with market capitalisation between Rs 500 crore and Rs 11,000 crore. It focuses on businesses that have generated positive free cash flow over the past five, seven and ten years. This helps test their ability to produce cash across different business and economic cycles.
Cash generation alone is not enough. The companies must also record sales growth of more than 5% pa over three and five years. This is to ensure we eliminate companies that are not growing at all over a long period of time. Operating margins must remain above 12%. Return on capital employed must exceed 15% and stay reasonably close to its five-year average.
The balance sheet faces another check. Debt-to-equity must be below 0.3. Promoters must hold more than 25%, with no pledged shares. Their holding should also not have fallen sharply over the past three years. A dividend payout above 10% provides an additional sign that some of the cash is reaching shareholders.
Valuation is the final gate. Each company must trade at less than 20 times free cash flow. The idea is simple. Find businesses that produce real cash, maintain healthy fundamentals and are still available at a sensible price. We have only considered companies with Q1 FY27 results.
Join now
In short, a very high hurdle to cross. Not surprisingly, only three stocks passed this test. Let’s take a look at them.
#1 IndiaMART InterMESH: High Treasury Gains Cushion Paying-Subscriber Drop
IndiaMART InterMESH, the first and largest B2B digital marketplace in the country, today stands out as a game-changer on the B2B landscape. It focuses on integrating small and medium businesses (SMEs) by expanding digital tools and online marketplace access.
IndiaMART InterMESH Financial Performance
| Metric | Value |
| Q1 FY27 revenue growth | 11% |
| Q1 FY27 profit growth | 12% |
| Q1 FY27 cash from operations | Rs 163 crore |
| Debt-to-equity | 0.01 |
IndiaMART recorded cumulative free cash flow of Rs 2,705 crore over five years. The figure rises to Rs 3,708 crore over 10 years. Its asset-light marketplace model requires limited capital expenditure. This has allowed operating cash flow to convert into free cash flow consistently.
The company also clears the growth and profitability checks. Sales compounded at 17% over three years and 19% over five years. Its FY26 operating margin stood at 30%. This was in line with its five-year average. RoCE was 28%, compared with a five-year average of 25.4%.
The balance sheet adds to the cash-flow case. Debt-to-equity was just 0.01. Promoters held 49.07% in June 2026, with no pledged shares. The holding declined by only 0.14 percentage points over three years. The FY26 dividend payout ratio was 76%.
Revenue rose 11% YoY to Rs 414 crore in Q1 FY27. Net profit increased 12% to Rs 172 crore. However, other income contributed Rs 107 crore. This included mark-to-market gains on treasury investments. Cash from operations stood at Rs 163 crore.
Deferred Revenue & AI Investments Cushion Operational Slowdown
Deferred revenue increased 16% to Rs 2,014 crore. This supports revenue visibility. IndiaMART is also investing in AI-led cataloguing, matchmaking and call handling.
The stock trades at 15.6 times free cash flow. This is within the screen’s limit of 20 times. The main risk is subscriber growth. Paying suppliers declined by 1,850 during the quarter to 2.18 lakh.
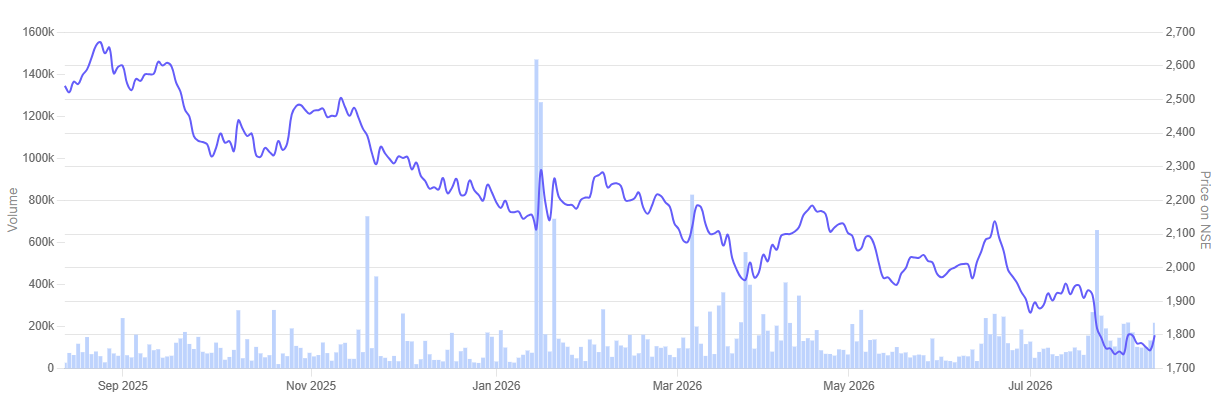
In the past year, the share price of IndiaMART InterMESH is down 29.6%.
IndiaMART InterMESH 1 Year Share Price Chart
#2 Mastek: 25% Order Backlog Expansion Driven by North American AI Deals
Established in 1982, Mastek is a provider of vertically-focused enterprise technology solutions. Having a presence in IT industry for almost 4 decades, Mastek has evolved from an IT solutions provider to Digital transformation partner.
Mastek Financial Performance
| Metric | Value |
| Q1 FY27 revenue growth | 7.7% |
| Q1 FY27 profit growth | 15% |
| FY26 free cash flow | Rs 515 crore |
| Debt-to-equity | 0.16 |
Mastek generated cumulative free cash flow of Rs 1,645 crore over five years and Rs 2,231 crore over 10 years. FY26 free cash flow reached Rs 515 crore. This was its highest level in more than a decade. Cash conversion has therefore improved even as the company expanded internationally.
Sales compounded at 13% over three years and 17% over five years. The FY26 operating margin was 16%. This was slightly below its five-year average of 17.6%, but remained above the screen’s 12% floor. RoCE stood at 18%. It was also above 80% of its five-year average, as required by the screen.
Debt-to-equity stood at 0.16. Borrowings declined to Rs 438 crore from Rs 583 crore a year earlier. Promoters held 35.77% in June 2026, with no pledged shares. The FY26 dividend payout ratio was 18.5%.
Revenue increased 7.7% YoY to Rs 985 crore in Q1 FY27. Net profit rose 15% to Rs 106 crore. The 12-month order backlog increased 25% to Rs 2,935 crore as of June 30, 2026. Mastek also closed more than 40 AI-led deals during the quarter.
Strong Valuation Metrics Support Middle East Execution Risks
The stock trades at 10.9 times free cash flow. Its P/E stands at around 12.7 times, which is a more relevant secondary valuation measure for a software company. Its 5-year average P/E stands at 21.2 times, while its peer median P/E is 21.
The Middle East remains the main risk. Delayed collections and project ramp-ups could affect margins and cash conversion.
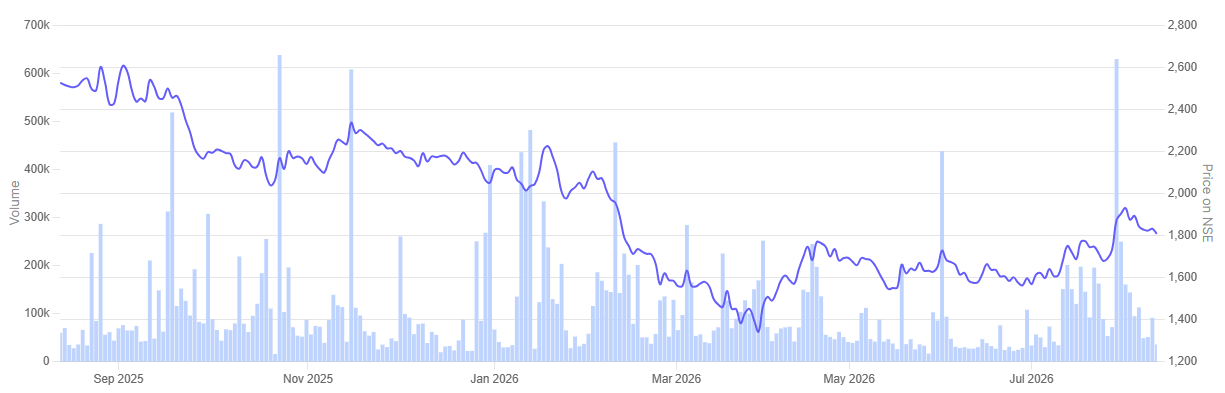
In the past year, the share price of Mastek is down 28.5%.
Mastek 1 Year Share Price Chart
#3 Axtel Industries: Debt-Free Microcap Expanding Manufacturing Capacity
Incorporated in 1991, Axtel Industries manufactures custom-designed food processing plants and machinery as per clients’ requirements.
Axtel Industries Financial Performance
| Metric | Value |
| Q1 FY27 revenue growth | 18.7% |
| Q1 FY27 profit growth | 3.2% |
| FY26 free cash flow | Rs 63 crore |
| Debt-to-equity | 0.00 |
Axtel Industries generated cumulative free cash flow of Rs 127 crore over five years. The figure stood at Rs 159 crore over seven years and Rs 189 crore over 10 years. FY26 free cash flow rose to Rs 63 crore from Rs 24 crore. This was supported by operating cash flow of Rs 71 crore.
The company passed the screen despite its relatively modest growth rate. Sales compounded at 8% over both three and five years. This was above the screen’s 5% threshold. The FY26 operating margin stood at 18%, compared with a five-year average of 15.2%. RoCE was 30%, against a five-year average of 27.8%.
Axtel was the only completely debt-free company among the three. Promoter holding remained unchanged at 49.95%, with no pledged shares. Its FY26 dividend payout ratio stood at 62%. This indicates that part of the cash generated by the business was returned to shareholders.
Revenue increased 18.7% YoY to Rs 32.31 crore in Q1 FY27. Net profit rose only 3.2% to Rs 1.96 crore. The slower profit growth reflected pressure on quarterly margins.
Capacity Expansion & R&D Drive Microcap Growth Strategy
Axtel’s expanded manufacturing facility has added factory sheds and material-handling equipment. The company is also establishing an R&D and testing centre for bulk-solids processing.
The stock trades at 10.7 times free cash flow, below the screen’s limit of 20 times. However, Axtel operates at a small scale. Quarterly performance can vary sharply with the timing and execution of large equipment orders.
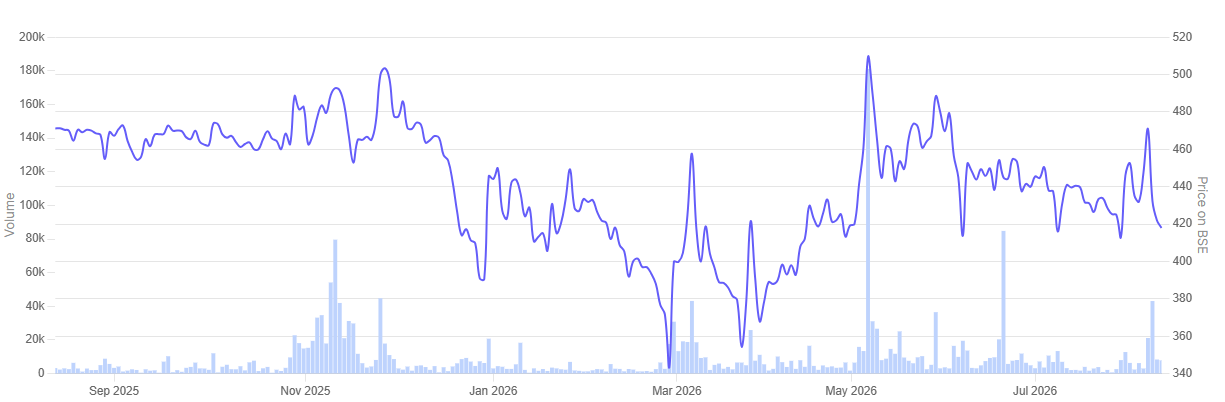
In the past year, the share price of Axtel Industries is down 28.5%.
Axel Industries 1 Year Share Price Chart
Conclusion
The three companies in this screen combine consistent free cash flow with healthy margins, low debt and strong capital efficiency. Their valuations also remain within the screen’s limit.
However, each company carries its own business and execution risks. The screen offers a useful starting point, but investors should study cash-flow quality and growth prospects before making a decision.
Cash Flow, Growth and Valuation
| Metric | IndiaMART | Mastek | Axtel Industries |
| FY26 free cash flow | Rs 687 crore | Rs 515 crore | Rs 63 crore |
| Q1 FY27 revenue growth | 11% | 7.7% | 18.7% |
| Q1 FY27 profit growth | 12% | 15% | 3.2% |
| Five-year sales CAGR | 19% | 17% | 8% |
Ratios and Ownership
| Metric | IndiaMART InterMESH | Mastek | Axtel Industries |
| RoCE | 28% | 18% | 30% |
| RoE | 20.7% | 15.6% | 20.5% |
| Debt-to-equity ratio | 0.01 | 0.16 | 0.00 |
| Promoter holding | 49.07% | 35.77% | 49.95% |
| Dividend payout | 76% | 18.5% | 62% |
You can track how these are progressing by adding stocks to your watchlist.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Ekta Sonecha Desai has a passion for writing and a deep interest in the equity markets. Combined with an analytical approach, she likes to deep dive into the world of companies, studying their performance, and uncovering insights that bring value to her readers.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.