



The Enigma of Nemish Shah & The Filings Trail
The reticent and private Nemish Shah does not give interviews. The ENAM Holdings co-founder has spent three decades running a famously tight book of Indian equities and saying almost nothing about it. The filings however are not so quiet.
Across the twelve quarters to June 2026, Shah did two very different things with two companies that look alike from a distance. In Bannari Amman Sugars he has not sold a single share. His holding has sat at 2.59% for three unbroken years. In LMW, the Coimbatore machinery maker once called Lakshmi Machine Works, he has been trimming. The stake has slipped from 5.57% to 5.24%, and the most recent cut came in the June 2026 quarter itself. Shah has owned these stocks for atleast a decade.
Both companies are close to debt free. Both posted a jump in net profit in FY26. So why grip one and shave the other? The answer sits below the profit line; in the part of the accounts most readers skip.
#1 LMW: A Capex Trap or a Legitimate Turnaround?
Incorporated in 1962, LMW Ltd builds textile spinning machinery, CNC machine tools and foundry castings, and runs an advanced technology centre supplying precision parts to the aerospace industry. With a market cap of Rs 18,311 cr as on 10th August 2026, it is one of only three companies in the world making the full range of spinning machinery, from blow room to ring frame.
Join now
While that is a big moat, it is also a trap. LMW sells capital equipment to Indian textile mills, so revenue tracks their willingness to spend. When mills stop ordering, the order book empties out. The last three years were exactly that stretch.
Still Climbing Out of a Downcycle?
Let us look at the 5-year financials to get a better idea of what the company has been doing for the past few years.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 1,727 | 3,171 | 4,719 | 4,696 | 3,012 | 3,207 | 13% |
| EBITDA (Rs cr) | 71 | 247 | 450 | 435 | 142 | 170 | 19% |
| Net Profit (Rs cr) | 45 | 181 | 384 | 374 | 103 | 131 | 24% |
EBITDA here refers to operating profit before other income. Before you start taking notes, please don’t forget that FY21 was the pandemic trough, and compounding off that number usually flatters the final percentage. The three-year sales CAGR tells the truer story at minus 12%.
FY26 revenue of Rs 3,207 cr is still 32% below the FY23 peak of Rs 4,719 cr. LMW is climbing out of a downcycle, not setting records.
In the quarter that ended in June 2026, sales rose 24% to Rs 861 cr. Operating profit jumped to Rs 64 cr from Rs 14 cr, lifting the margin from 2.0% to 7.4%. Net profit was Rs 56 cr against Rs 11 cr.
After eight quarters of scraping along the bottom, the operating engine restarted. Margin expansion of that size on a 24% revenue lift is what a real capex upcycle looks like early on.
Cash Pile Outearning the Machinery
Here is the part that matters most, and it is easy to miss. In FY26, LMW reported other income of Rs 132 cr against pre-tax profit of Rs 182 cr, meaning 72% of pre-tax profit arrived from outside the factories. On a trailing twelve-month basis, the ratio softens but stays large, at Rs 136 cr against Rs 234 cr.
Put it another way. Trailing operating profit is Rs 219 cr and depreciation Rs 121 cr, leaving Rs 98 cr from the core business against other income of Rs 136 cr. The cash pile currently earns more than the machinery does, and the company’s own disclosures flag that line.
But none of this makes the June quarter fake. Operating profit genuinely quadrupled. But anyone reading only the headline profit is seeing something the shop floor did not produce.
Is the Margin Expansion Already Priced In?
The share price of LMW was around Rs 8,200 in August 2021 and as on 10th August 2026 it was Rs 17,140 which is a jump of 109% in 5 years.
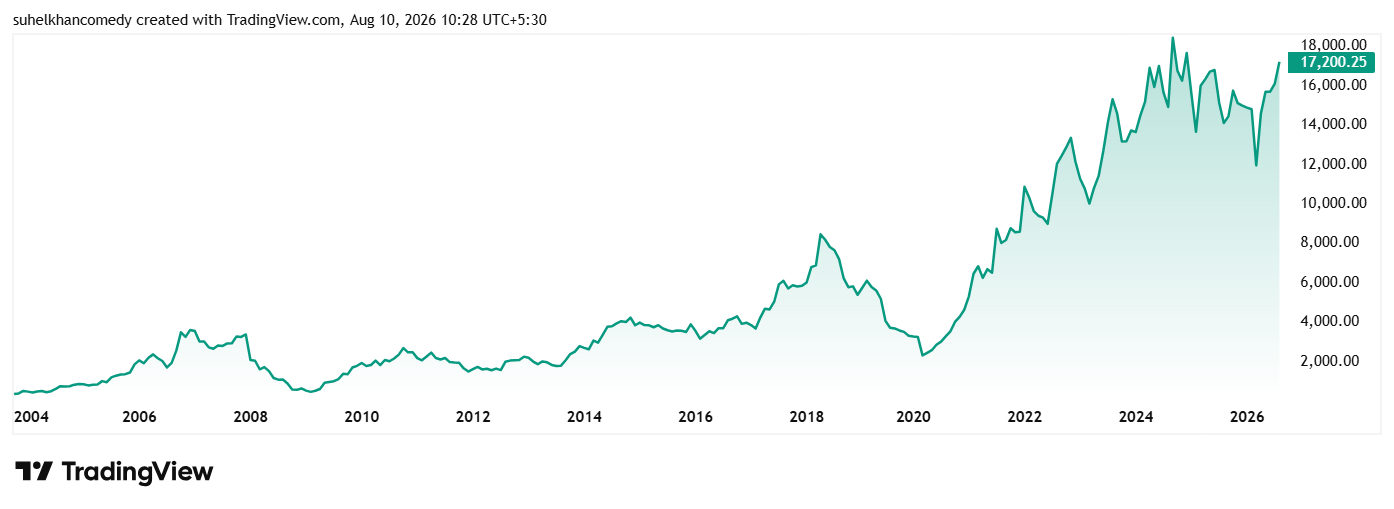
The current price is inching towards its 52-week high of Rs 17,699, but still 10% down from the all-time high of Rs 19,200.
As for the valuations the company’s share is trading at a PE of 100x which is close to 3 times the current industry median of 31x. The 10-Year median PE of the company is 44x while the industry median for the same period is 27x.
The Capital Conundrum: Single-Digit Returns on Six Times Book Value
Return on equity for the last reported year was 4.05% and return on capital employed 6%, with three-year return on equity at 7.02%. A company earning single digits on capital, priced at six times book, has already been paid for a recovery that has produced exactly one strong quarter.
LMW has also carried zero borrowings for six straight years and its interest cost rounds to nil. Against equity capital of Rs 11 cr it holds reserves of Rs 2,856 cr and an investment book of Rs 706 cr. On 7th August 2026, CRISIL assigned it a corporate credit rating of AA with a stable outlook.
Which brings us back to Shah. His holding has stepped down from 5.57% to 5.47%, then 5.43%, 5.36%, 5.35% and now 5.24%. That is roughly 35,000 shares over three years, close to 11,700 of them in the June quarter alone. On a stake above 5% it is a nudge, not an exit. But the direction has been one way for twelve quarters, and one way while the stock climbed.
#2 Bannari Amman Sugars: The Decade-Long Path to Zero Borrowings
Incorporated in 1983, Bannari Amman Sugars set up its first mill in 1986 and now runs five units crushing 23,700 tonnes of cane a day across Tamil Nadu and Karnataka. Calling it a sugar company undersells it. There are also two distilleries, cogeneration plants that burn bagasse for power, windmills in southern Tamil Nadu and a granite processing unit.
The company market cap as on 10th August was Rs 4,413 cr and Shah owns 2.6%, roughly 3.25 lakh shares worth about Rs 114 cr. He has not touched it in any of the twelve quarters on record.
Capital Discipline: Halving the Cash Conversion Cycle
One of the strongest numbers when we look at Bannari Amman’s financials is borrowings. It stood at Rs 1,221 cr in FY15. By FY21 they were Rs 872 cr, by FY24 Rs 486 cr, by FY25 Rs 150 cr. In FY26 they finished at Rs 9 cr, making them virtually debt free.
Interest expense followed it down, from Rs 93 cr in FY15 to Rs 16 cr in FY25 and Rs 2 cr in FY26. A company that once handed nearly a hundred crore a year to its lenders now pays them almost nothing. This is a classic case of solid capital and debt management.
The working capital discipline behind that is just as striking. The cash conversion cycle halved from 263 days to 137 days in FY26, with inventory days down from 277 to 140. Cash from operations was Rs 514 cr and free cash flow Rs 405 cr, both among the best the company has recorded. The investments line jumped from Rs 4 cr to Rs 263 cr, which is what a business does when it runs out of debt to repay.
The Tax Shield Illusion: Dissecting the 41% Profit Spike
Let us look at the financials behind this smooth money management machine.
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 1,563 | 1,998 | 2,526 | 2,220 | 1,793 | 1,917 | 4% |
| EBITDA (Rs cr) | 211 | 218 | 304 | 306 | 210 | 198 | -1% |
| Net Profit (Rs cr) | 92 | 80 | 143 | 152 | 105 | 148 | 10% |
EBITDA here refers to operating profit before other income. Figures are standalone.
Net profit rose 41% in FY26, from Rs 105 cr to Rs 148 cr. On its own that reads like a turnaround. The table above already hints otherwise: EBITDA over five years has compounded at a negative rate.
Look at FY26 in isolation and the picture changes to a sharper one. Sales grew 6.9%, but operating profit fell from Rs 210 cr to Rs 198 cr, and the operating margin slipped from 11.7% to 10.3%. The factories did not have a better year. They had a slightly worse one.
What changed was further down the page. The effective tax rate dropped from 35% in FY25 to 17% in FY26. Applying the earlier rate to FY26 pre-tax profit of Rs 177 cr gives net profit of roughly Rs 115 cr rather than Rs 148 cr. Around Rs 33 cr of the Rs 43 cr increase came off the tax line, not the shop floor.
30x PE vs the 25% Discount: Valuation Realities
The share price of Bannari Amman Sugars was around Rs 1,820 in August 2021 and as on 10th August 2026 it was Rs 3,520 which is a jump of 94% in 5 years.
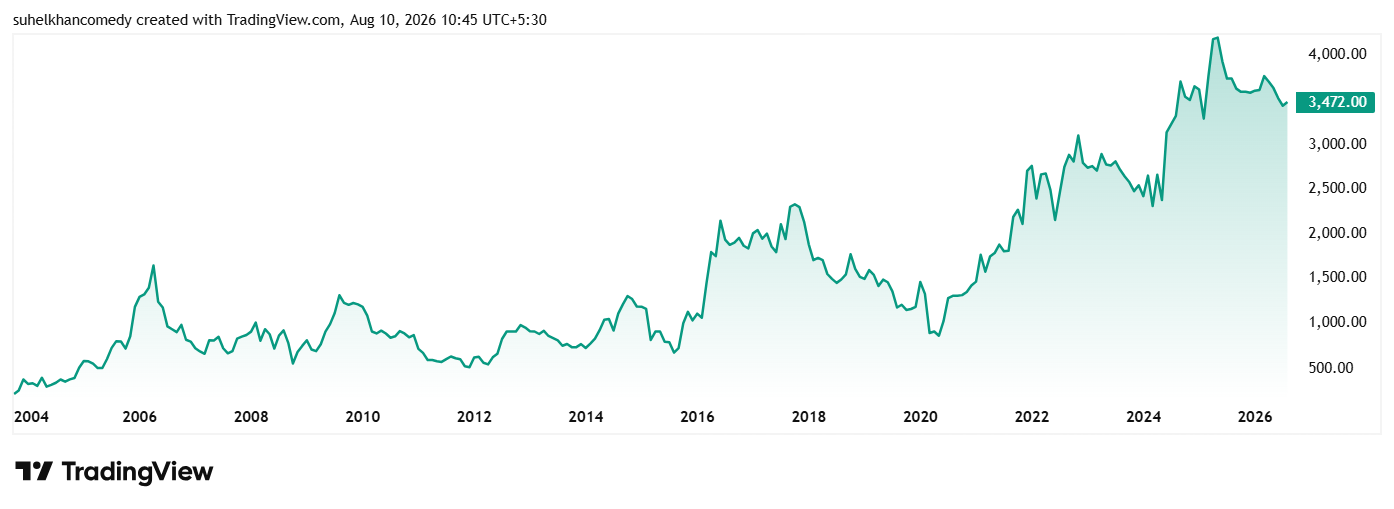
At the current price, the stock is trading at a discount of 25% from its all-time high of Rs 4,675.
As for the valuations, the company’s share is trading at a PE of 30x and the industry median currently is 16x. The 10-year median for the company is 25x while the industry median for the same period is 11x.
The 13% Margin Test: What to Watch in the August 14th Board Meet
The board meets on 14th August 2026 to approve results for the quarter ended June 2026. The base is soft: the year-ago quarter delivered sales of Rs 419 cr, operating profit of Rs 37 cr and net profit of just Rs 15 cr. Growth against that should not be hard.
The line worth watching is the operating margin. If it holds near the 13% managed in the September and December 2025 quarters, the FY26 slippage was a cycle blip. If it lands closer to the single digits of March 2026, the deleveraging bought time but not yet growth.
Another point worth noting is that on 2nd July 2026 the company said the Erode Collector had initiated recovery of Rs 12.72 cr in electricity tax covering 2003 to 2016, a demand it intends to challenge. On 27th June 2026 it reported a cybersecurity incident at its Tamil Nadu distillery, addressed immediately with no impact on operations.
Nemish Shah’s One Golden Rule, Two Radically Different Trades
If you look closely, both the stocks we analysed today, share a common thread. Something Shah quietly is a fan of. It is a clean balance sheet. LMW has carried no debt for six years. Bannari Amman spent a decade getting to the same place. Where most mid-sized Indian manufacturers borrow to chase growth, both chose the harder route. What separates them is where last year’s profit came from, and what Shah did about it.
At LMW the operating recovery is genuine, but reported profit leans heavily on treasury income, revenue sits a third below its own peak, and the price embeds a full recovery at 97 times earnings. He has been trimming, quarter after quarter.
At Bannari Amman operations went sideways and the profit headline was flattered by a tax credit, but the balance sheet was transformed, cash generation is strong, and the price asks for a third as much. He has not moved a share.
Read that way, the two positions are not a contradiction. They look like one rule applied twice. Mind what you pay for the earnings, and mind where the earnings came from. If you are following the story or intend to, you can track both names on a watchlist and see what 14th August brings.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.