



The Supply Chain Pivot: Why Murthy is Buying Manufacturing
When the man who built Infosys picks stocks, most people expect him to buy software. Narayana Murthy has done the opposite. His family office, Catamaran Ventures, spent a long stretch on the sidelines. In fact, following a heavy post-2022 sell-off, Catamaran held just two listed stocks.
That has changed fast. As per the exchange filings for the quarter ending June 2026, Catamaran now holds more than 1% in seven listed companies. On the morning of 23rd September 2026, those stakes are worth close to Rs 1,421 cr. Four of the seven names arrived in the June quarter alone. Two more were bought privately, well before they listed. And just three holdings, Sansera Engineering, Aequs and TD Power Systems, account for about 82% of the money.
Look closer and the portfolio reads like a supply chain. Vardhman Special Steels makes alloy steel. M M Forgings and Sansera hammer steel into engine and chassis parts. SEDEMAC builds the electronics that tell those engines what to do. Aequs makes parts that fly on Airbus and Boeing jets. TD Power makes the generators that keep plants running. The lone software company, IRIS RegTech, is the laggard. Let us dive in, starting with the largest holding.
#1 Sansera Engineering: The ₹490-Crore Precision Forging Anchor
Incorporated in 1981, Bengaluru-based Sansera Engineering makes precision forged and machined parts such as connecting rods, crankshafts and rocker arms for two-wheelers, cars and trucks. It ranks among the top 10 global suppliers of connecting rods for light and commercial vehicles. It also supplies parts for aircraft, tractors and off-road machines, and now reports a separate revenue line for aerospace, defence and semiconductor work.
Catamaran picked up a 1.68% stake in the June 2026 quarter. At Rs 4,650, the price on 23rd September 2026, that stake is worth over Rs 490 cr. It is the single largest position in the portfolio.
Margin Expansion: Profit Outpacing Revenue Growth
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 1,549 | 1,989 | 2,338 | 2,811 | 3,017 | 3,498 | 18% |
| EBITDA (Rs cr) | 274 | 336 | 380 | 482 | 528 | 645 | 19% |
| Net Profit (Rs cr) | 110 | 132 | 148 | 188 | 217 | 327 | 24% |
EBITDA here is operating profit before other income. The June 2026 quarter was stronger still. Sales rose 33% over the same quarter last year to Rs 1,021 cr, and net profit rose 38% to Rs 87 cr. Borrowings stood at Rs 591 cr at the end of FY26 against a net worth of over Rs 3,000 cr.
Promoter holding has slipped from 34.78% in September 2024 to 29.21% in June 2026. Most of that drop came in the December 2024 quarter, in the same year that fresh equity more than doubled the company’s reserves.
Valuation Check: Buying After a 206% Premium Rally
The market has noticed. The stock is up 206% in one year and has compounded at 41% a year over five years.
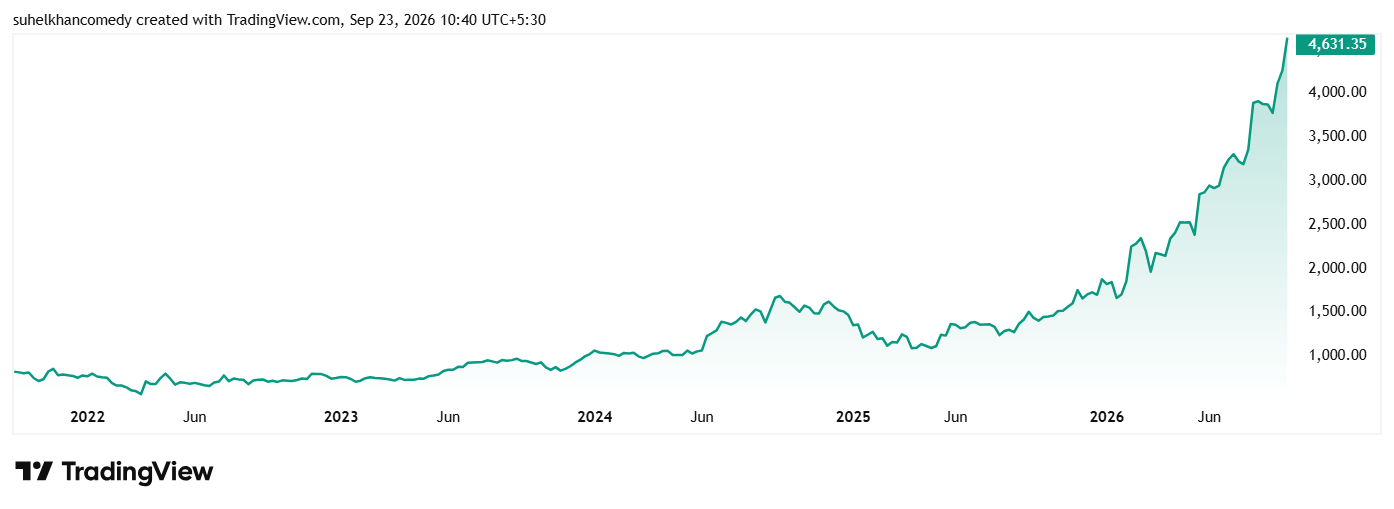
It trades at a PE of 83x against the current industry median of 29x. It also trades at over 9 times its book value, while return on equity sits near 12%. Since Sansera listed only in September 2021, a 10-year median PE is not available. Put simply, Murthy walked in after the big run, not before it.
#2 Aequs: The Early-Stage Aerospace Play Squeezed by Losses
Incorporated in 2000, Aequs runs an aerospace manufacturing cluster in Belagavi, Karnataka, where forging, machining, surface treatment and assembly sit inside one special economic zone. Its customers include Airbus, Boeing, Safran and Collins Aerospace. It also makes cookware, small appliances and toys.
Catamaran did not buy this one on the market. Through its fund Catamaran Ekam, it was an investor well before the IPO of December 2025, which was priced at Rs 124 a share. It holds 2.8% of the company, worth over Rs 460 cr at Rs 238 on 23rd September 2026. The stock is up roughly 96% from its issue price.
Rapid Revenue Growth Meets Heavy Depreciation
| Financial Year | FY23 | FY24 | FY25 | FY26 | 3Y CAGR |
| Sales (Rs cr) | 812 | 965 | 925 | 1,230 | 15% |
| EBITDA (Rs cr) | 40 | 129 | 79 | 92 | 32% |
| Net Profit (Rs cr) | -110 | -14 | -102 | -113 | NM |
Only four years of data are available, so a 3-year CAGR is shown. NM: not meaningful due to losses.
Sales grew 33% in FY26 to Rs 1,230 cr, and the June 2026 quarter was up 55% to Rs 396 cr. The bottom line went the other way. The net loss widened to Rs 113 cr in FY26, and the June quarter alone lost Rs 53 cr. Interest of Rs 94 cr and depreciation of Rs 138 cr simply ate up an operating profit of Rs 92 cr.
Trading at 11x Book Value Pre-Preferential Issue
Here is how the share price has moved since listing.
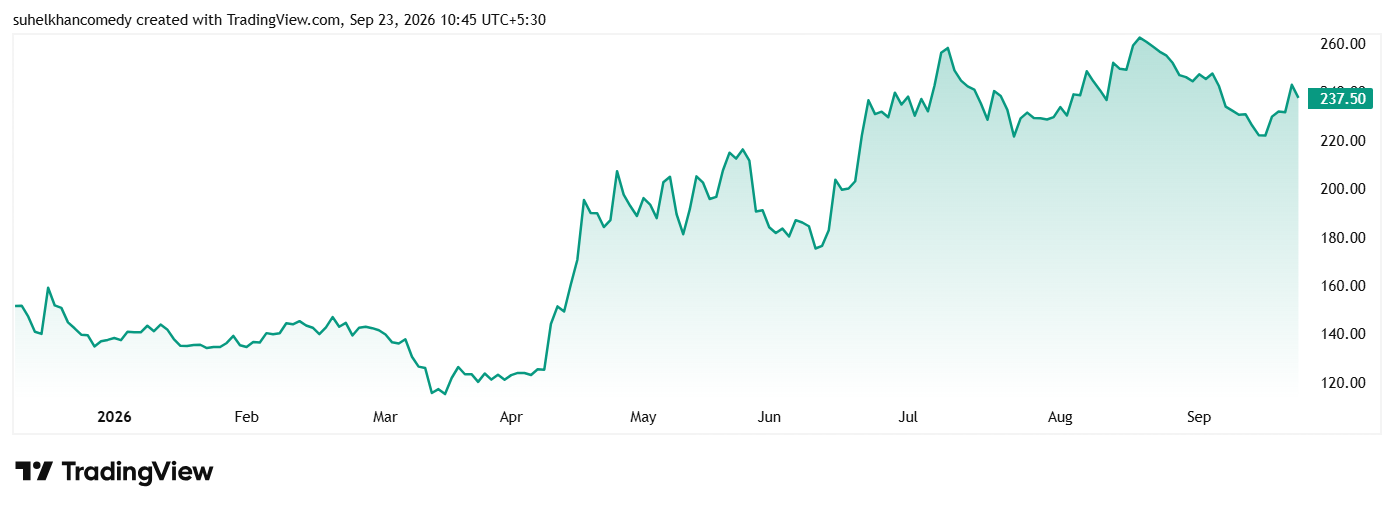
With no profits, there is no PE to speak of, and with a listing only in December 2025, no 10-year median either. The stock trades at close to 11 times book value. There is fresh news too. As per its filing with BSE, the board meets on 25th September 2026 to consider issuing warrants to the promoter on a preferential basis.
#3 TD Power Systems: The Stock Split Standard Screeners Missed
Incorporated in 1999, Bengaluru’s TD Power Systems builds AC generators and electric motors used in steam, gas, hydro and diesel power plants. I wrote about it in July. Since then, something has changed that many screens have missed.
Catamaran bought 1.46% of the company in the June 2026 quarter, or 22.8 lakh shares. But the company split each share into two, with a record date of 24th August 2026, as per an NSE Clearing circular. So, Catamaran now owns about 45.6 lakh shares. At Rs 757, that stake is worth close to Rs 345 cr, not the Rs 174 cr some trackers show.
Sustaining a 40% Net Profit Growth Engine
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 594 | 797 | 872 | 1,001 | 1,279 | 1,856 | 26% |
| EBITDA (Rs cr) | 71 | 97 | 134 | 171 | 235 | 335 | 36% |
| Net Profit (Rs cr) | 45 | 70 | 97 | 118 | 175 | 239 | 40% |
The pace has picked up further. June 2026 quarter sales jumped 72% to Rs 640 cr, and profit rose 72% to Rs 86 cr. Return on capital employed is 34% and borrowings are just Rs 18 cr. The order book stood at Rs 1,972.9 cr on 31st March 2026, as per its results filing.
Promoters Inject ₹75 Crore at a Discount
On 21st September 2026, the company allotted 12.5 lakh shares to its promoters at Rs 600 each, raising Rs 75 cr. Shareholders also cleared a plan to raise money from institutions. This matters because promoter holding had dropped from 58.51% in March 2023 to 26.87%. The Rs 600 price is about 21% below today’s level, as preferential pricing is tied to a SEBI formula based on past prices.
The stock is up 179% in a year and has compounded at 88% a year over five years, which is more than a 20-fold rise.
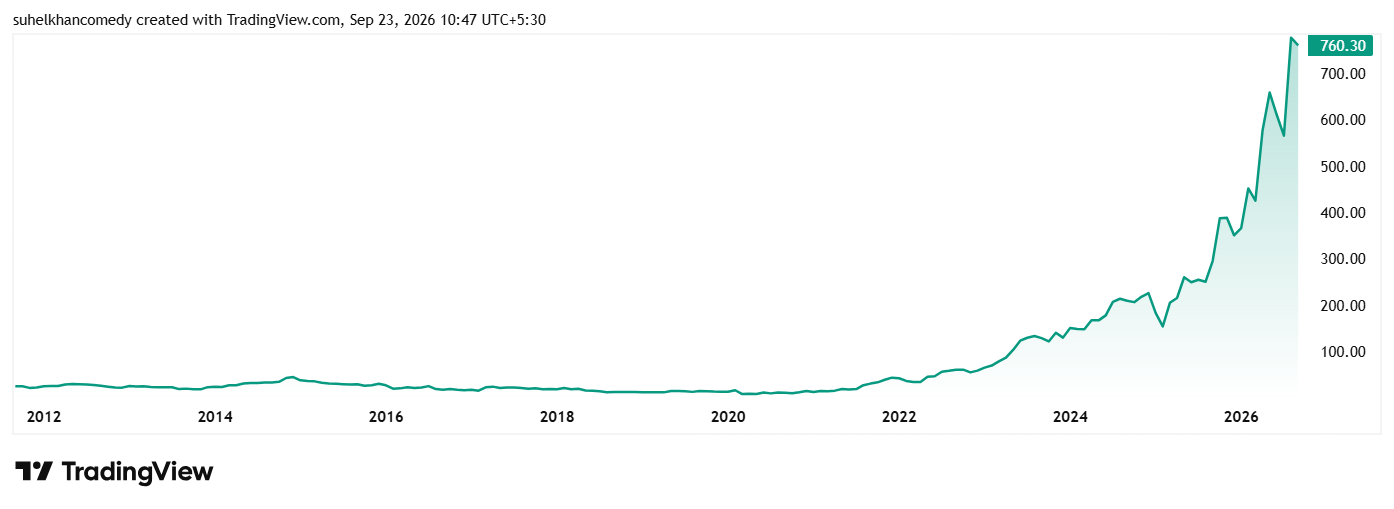
It trades at a PE of 86x against the current industry median of 33x. The 10-year median PE for the company is 35x while the industry median for the same period is 43x.
#4 SEDEMAC Mechatronics: The 114x PE Tech Play Fueling Two-Wheelers
Incorporated in 2007, Pune-based SEDEMAC Mechatronics was set up by engineers from IIT Bombay. It designs the electronic control units that start engines, manage fuel injection and run motors in two-wheelers, three-wheelers, electric vehicles and generator sets.
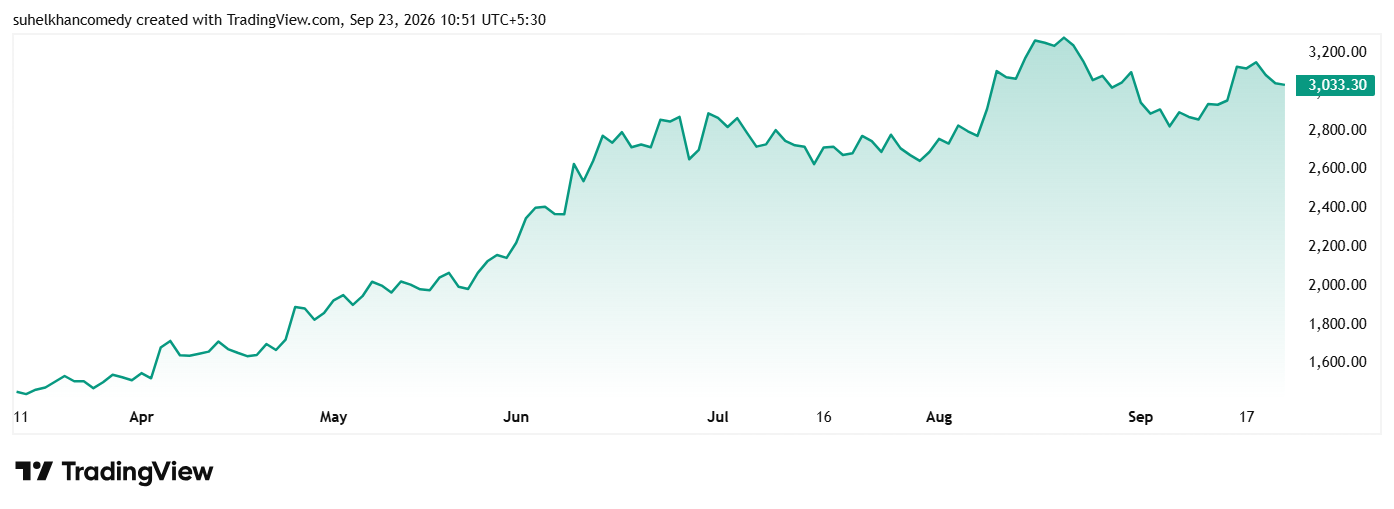
Catamaran entered in April 2025 by buying out an early investor, before the IPO. When the IPO opened in March 2026 at Rs 1,352 a share, the retail portion was subscribed just 0.20 times, as per exchange data. The stock was at Rs 3,048 on 23rd September 2026, about 124% above the issue price. Catamaran’s 1.57% stake is worth about Rs 210 cr.
Scaling Operations Post-Covid
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 240 | 283 | 423 | 531 | 658 | 1,058 | 35% |
| EBITDA (Rs cr) | 28 | 29 | 47 | 78 | 121 | 217 | 51% |
| Net Profit (Rs cr) | 7 | 4 | 9 | 6 | 47 | 104 | 71% |
Read the profit CAGR with care. The base year, FY21, was hit by Covid, and profit then was a tiny Rs 7 cr. Still, the recent numbers are strong. June 2026 quarter sales rose 43% to Rs 310 cr and profit nearly doubled to Rs 33 cr. Return on capital employed is 35%.
Regulatory Hurdles vs. Favorable Credit Ratings
The stock trades at a PE of 114x against the current industry median of 29x, and at 30 times book. With a listing only in March 2026, there is no 10-year median PE. The BSE filings show two recent events. A GST department search ended on 11th September 2026, and the company said it saw no material impact. Four days later, ICRA upgraded its loan ratings to A with a positive outlook.
#5 Vardhman Special Steels: The Toyota-Backed Alloy Manufacturer
Incorporated in 2010, Vardhman Special Steels rolls alloy steel into bars that later become engine and gearbox parts. Japan’s Aichi Steel, part of the Toyota group, owns about a quarter of it. Catamaran’s 1.02% stake is worth about Rs 40 cr at Rs 408.
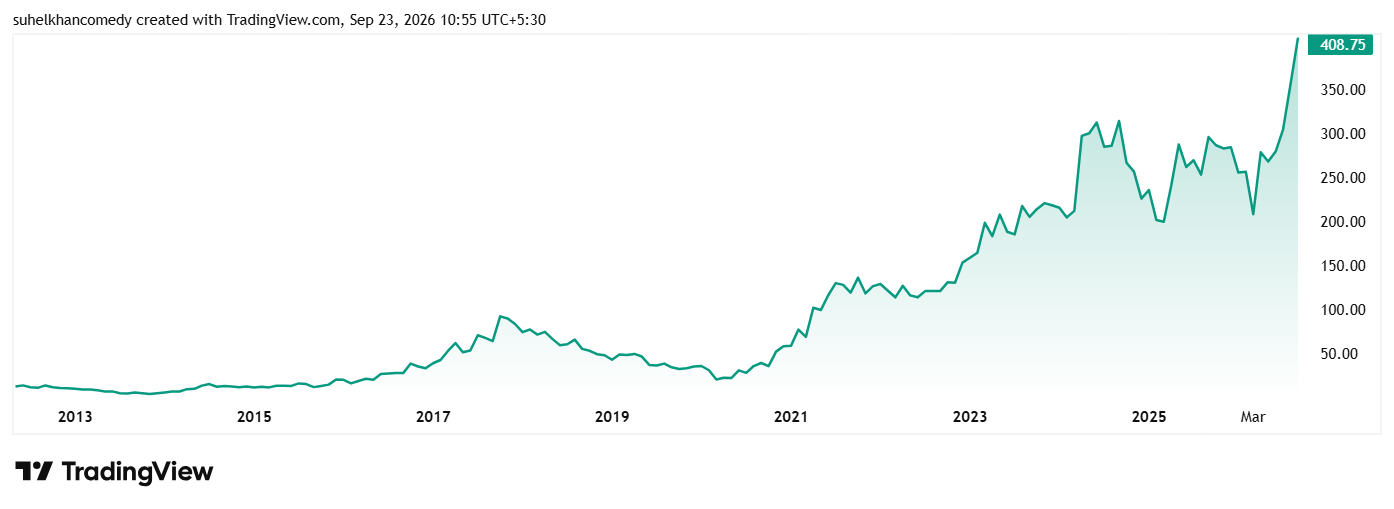
I wrote about it in July, the price was Rs 276. That is a gain of about 48% in just over two months.
Flat Revenues, Best Operating Margin in 13 Quarters
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 937 | 1,368 | 1,735 | 1,661 | 1,764 | 1,754 | 13% |
| EBITDA (Rs cr) | 107 | 174 | 141 | 142 | 148 | 166 | 9% |
| Net Profit (Rs cr) | 44 | 101 | 100 | 92 | 93 | 122 | 23% |
The June 2026 quarter explains the rally. Sales rose 12% to Rs 486 cr, but net profit doubled to Rs 41 cr, and the operating margin touched 12%, the best in the last 13 quarters. The stock trades at a PE of 28x against the current industry median of 21x. The 10-year median PE for the company is 19x while the industry median for the same period is 19x.
#6 M M Forgings: The Old Royal Enfield Dealer Carrying Heavy Debt
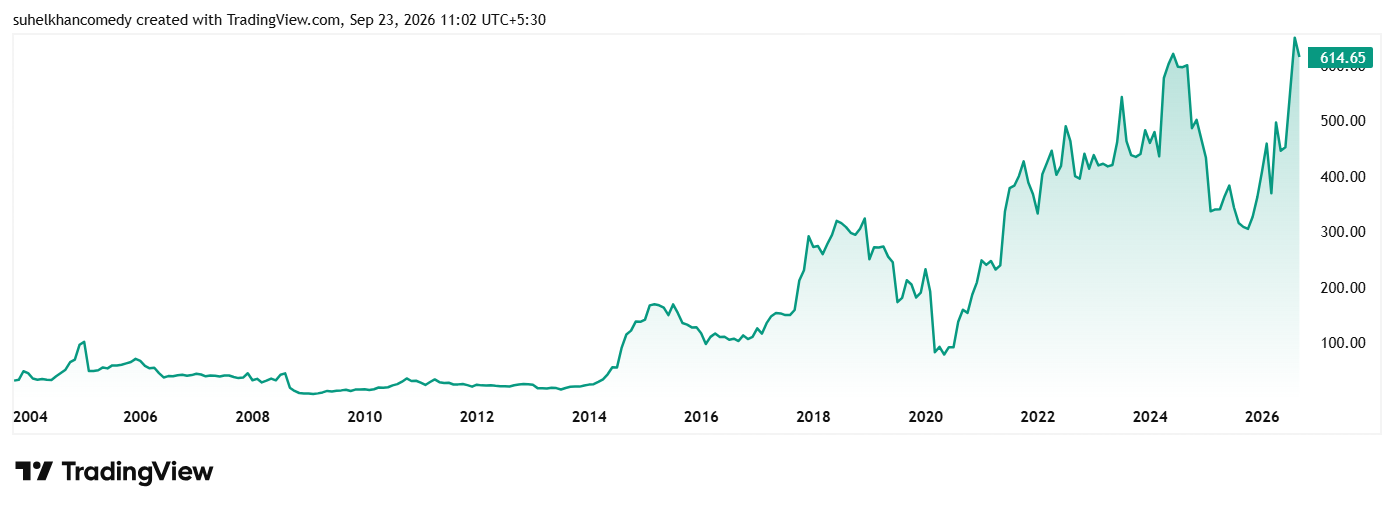
M M Forgings has one of the more unusual histories in the portfolio. It began in 1946 as a dealer of imported Royal Enfield bikes and set up its first forging plant in Tamil Nadu in 1974. Today it makes steel forgings in raw, semi-machined and fully machined form. Catamaran bought 1.02% in the June 2026 quarter, worth about Rs 30 cr at Rs 604.
The share is currently trading at Rs 614 as on 23rd September 2026.
Borrowings Eclipse Net Worth
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 752 | 1,140 | 1,462 | 1,563 | 1,525 | 1,590 | 16% |
| EBITDA (Rs cr) | 129 | 209 | 273 | 293 | 296 | 280 | 17% |
| Net Profit (Rs cr) | 46 | 91 | 128 | 135 | 123 | 99 | 17% |
The five-year CAGR hides a recent slide. Net profit has fallen from Rs 135 cr in FY24 to Rs 99 cr in FY26. The interest bill has climbed from Rs 28 cr in FY22 to Rs 78 cr. Borrowings of Rs 1,235 cr are now larger than the company’s net worth of about Rs 975 cr. The June 2026 quarter profit of Rs 90 cr looks strong, but it includes other income of Rs 63 cr.
The stock trades at a PE of 26x, which is flattered by that one-off, against the current industry median of 29x. The 10-year median PE for the company is 20x while the industry median for the same period is 25x. The share is up 88% in a year, but only 8% a year over five years.
#7 IRIS RegTech: The Lone Software Pick Lagging the Portfolio
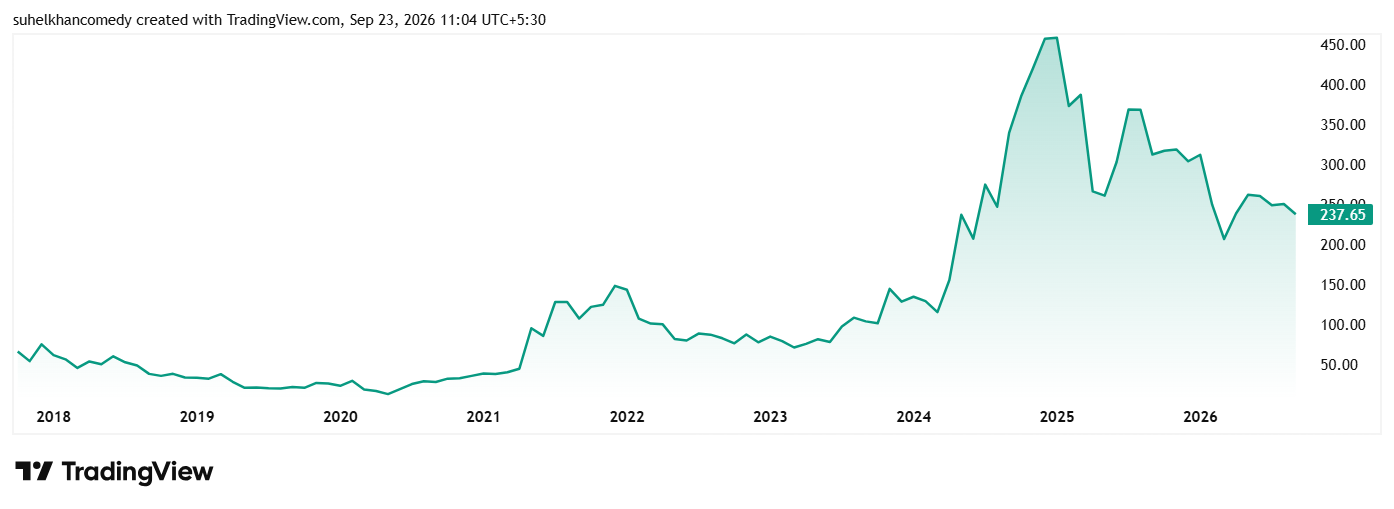
Incorporated in 2000, IRIS RegTech Solutions builds software that helps regulators and companies file financial data in standard digital formats. It is the only technology company in Murthy’s listed book, and it has been on the register since at least December 2024. Catamaran holds 1.47%, worth only about Rs 7 cr at Rs 236. The stock is down 27% in a year.
How a TaxTech Sale Inflated FY26 Profit
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 57 | 61 | 74 | 102 | 110 | 128 | 18% |
| EBITDA (Rs cr) | 11 | 7 | 10 | 15 | 19 | 10 | -2% |
| Net Profit (Rs cr) | 4 | 1 | 4 | 9 | 13 | 127 | NM |
NM here means not meaningful, as FY26 profit includes a one-time gain.
The FY26 profit of Rs 127 cr is not what it seems. The company booked an exceptional gain of about Rs 136 cr from selling its TaxTech business to US-based Sovos. The core business earned an EBITDA of just Rs 10 cr, and the June 2026 quarter slipped to an operating loss. On the plus side, cash and investments stood at Rs 155.4 cr at the end of FY26, a large chunk of its Rs 486 cr market value.
The PE of 38x is flattered by that gain, and with losses between FY16 and FY19, a 10-year median PE would not mean much.
Following the Strategy, Not Just the Price
Put the seven names side by side and the pattern is hard to miss. The man who helped build India’s software export story is putting his family’s money into engineering and manufacturing. Forgings, special steel, generators, aircraft parts and engine electronics make up almost the entire book.
The entry points tell a second story. In Aequs and SEDEMAC, Catamaran came in early and privately. SEDEMAC has since more than doubled from its IPO price and Aequs has nearly doubled. In Sansera and TD Power, it bought after huge rallies. A retail investor copying those trades today pays even more.
The risks are real. Aequs is still losing money. M M Forgings carries more debt than equity. SEDEMAC trades at over 100 times earnings. And IRIS shows that a famous backer cannot fix a weak quarter. A practical move is to add these stocks to a watchlist and see how the next two quarters play out before drawing any conclusions. Following a famous name is easy. Paying his price is a different matter.
Disclaimer:
Note: We have relied on data from www.Screener.in and www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information, including filings made available on the BSE website.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, He was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors.