
Catamaran’s 5th Metal Pick: Decoding the ₹33 Crore Foseco Investment
On Thursday, 27th August 2026, Catamaran Ventures LLP bought 55,978 shares of Foseco India at Rs 5,897 apiece. The ticket came to Rs 33.01 cr and equates to roughly 0.74% of the company. The stock rose the following session to Rs 6,371, valuing Foseco at Rs 4,819 cr.
Taken alone, a sub-1% position is easy to wave away. The context is what makes it worth reading. In the June 2026 quarter alone, Murthy’s family office turned up as a fresh name in four listed companies: Sansera Engineering with about 1.7%, TD Power Systems with about 1.46%, Vardhman Special Steels with 9,82,693 shares for around 1.0%, and a smaller position in MM Forgings.
Line those five up and the thread is hard to miss. Sansera and MM Forgings shape metal into components. Vardhman melts scrap in an electric arc furnace and rolls it into alloy steel bars. TD Power builds the generators that heavy plants run on. And Foseco sells the consumables that foundries use to turn molten metal into castings. Catamaran has spent two quarters buying its way along a single industrial chain, and it has now bought a supplier to the whole of it.
Join now
The Vesuvius Group Dilution: How the Morganite Deal Unlocked a 15% Block
Foseco does not usually have shares available. Until December 2025 its UK parent, the Vesuvius group, owned 74.98% and had done every quarter since 2017. The float was sleepy and domestic institutions barely bothered.
What changed was a deal. In late 2025 Foseco India acquired 75% of Morganite Crucible (India), a separately listed maker of the heat-resistant vessels used to melt metal, now renamed Foseco Crucible (India). Foseco paid partly in its own shares, which is why the parent’s stake fell to 63.54% and public shareholding jumped from 24.22% to 36.00%. The arithmetic is precise: dilute 74.98% by a fresh issue equal to 15.26% of the enlarged capital and you land on 63.54% to the second decimal.
Those new shares went to Morgan Advanced Materials, the London-listed seller. On Thursday, Morgan sold every one of them. Morganite Crucible Limited and Morgan Terrassen BV offloaded 11,50,800 shares for Rs 678.6 cr, exiting completely. Morgan never bought that stake on the market. It was handed the paper as part payment, held it through the lock-in, and cashed it nine months later to pay down group debt.
That is the door Catamaran walked through. It was not the biggest buyer on the other side. SBI Mutual Fund took Rs 190 cr and Motilal Oswal Mutual Fund took Rs 25.11 cr, with the balance going to buyers who did not have to be named. But for a family office that has been hunting this sector, a forced 15% block is often the only way in.
Foseco India Financials: Analyzing the 19% Revenue CAGR and Standalone Margins
Foseco was set up in 1958 and runs plants at Sanaswadi near Pune and at Puducherry. Its filters, coatings and binders go to firms casting parts for cars, tractors, valves, railways and power equipment. One flag before the table: the company closes its books in December, not March, so these are calendar years.
| Year ended December | CY20 | CY21 | CY22 | CY23 | CY24 | CY25 | 5-yr CAGR |
| Sales (Rs cr) | 251 | 338 | 407 | 477 | 525 | 604 | 19% |
| EBITDA (Rs cr) | 21 | 44 | 63 | 70 | 91 | 107 | 38% |
| Net Profit (Rs cr) | 15 | 33 | 46 | 73 | 73 | 75 | 38% |
A 38% profit CAGR reads great and is mostly an accident of where the clock starts. CY20 was the pandemic year: profit fell 57% to Rs 15 cr and operating margin collapsed to 8% against a normal 14% or so. Compounding off a hole that deep and the number flatters.
Start from CY19, the last clean pre-pandemic year, and the six-year picture is sober but honest. Sales compound at 11%, operating profit at 15% and net profit at about 14%. That is a solid industrial business, not a rocket. The table is standalone for a reason: on a consolidated basis the record starts only in CY24, when the crucible business arrived.
Debt-Free Balance Sheet and the Hidden Value in the Crucible Subsidiary
Murthy has spoken often about wanting businesses that generate real cash and carry no debt. Foseco fits that description almost to the letter. Borrowings stood at Rs 1 cr at the end of CY25 against reserves of over Rs 1,000 cr. Operating cash flow was Rs 92 cr against Rs 107 cr of operating profit, and free cash flow was Rs 85 cr. The cash conversion cycle is negative at 39 days, because suppliers get paid slower than customers pay in.
The June 2026 quarter also shows something the market has not fully priced. On a standalone basis Foseco did Rs 182 cr of sales at a 17.6% operating margin. Consolidated, it did Rs 231 cr at 22.9%. Strip one from the other and the crucible business contributed roughly Rs 49 cr of sales and Rs 21 cr of operating profit in a single quarter. The unit Morgan was willing to let go of is currently the richest-margin asset in the group.
Valuation Check: 46x PE and Upcoming Institutional Fund Raise
The share price of Foseco was around Rs 1,500 in August 2021 and as on 28th August 2026 it was Rs 6,311.
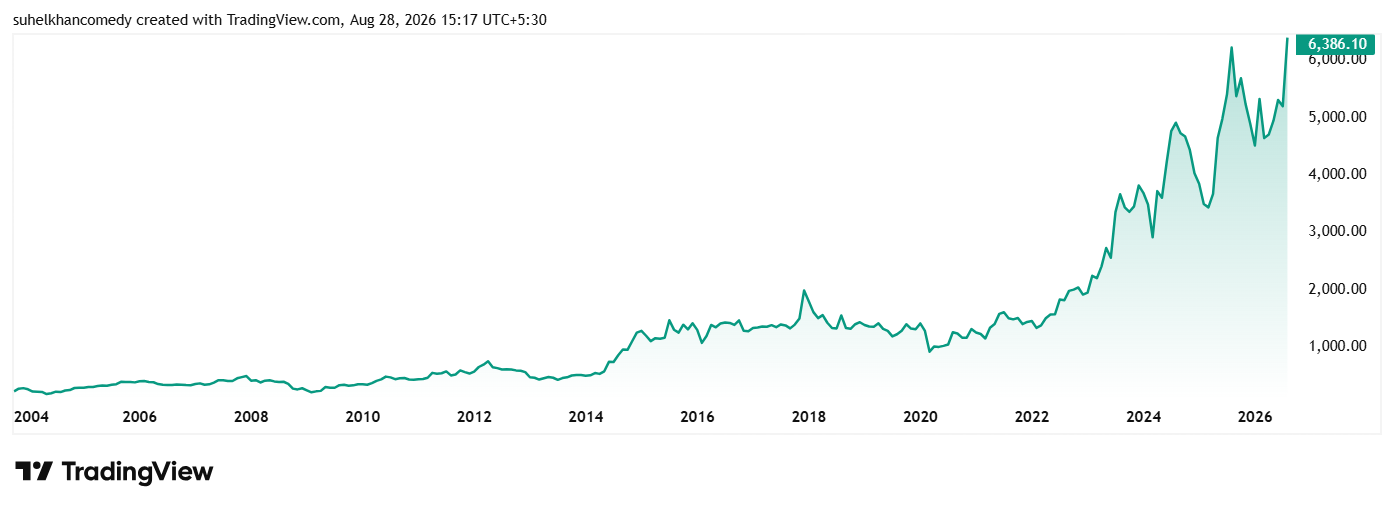
The stock trades at a PE of about 46x and the industry median currently is 28x. The 10-year median PE of the company is 44x while the industry median for the same period is 28x again. Over a decade the share price compounded at 16% a year while profit compounded at 10%. That six-point gap is the rerating doing the work, not the business.
The dividend yield is 0.41%. The 52-week range runs from Rs 4,300 to Rs 6,846, and the shares are down roughly 5% over the year.
Two supply events belong on the calendar. Foseco has told the exchanges that shareholders will be asked at the 59th annual general meeting on 23rd September 2026 to approve a fund raise through a qualified institutional placement. It must also sell down about 1.77% of its listed crucible subsidiary to meet minimum public shareholding rules. A stock that has just absorbed a 15% block has more paper heading its way.
What the Foseco Entry Means for Catamaran Watchers
Three things stand out for readers who follow the family office rather than the stock.
First, the buying is deliberate and it is sectoral. Five entries across two quarters, every one of them in metal forming, special steel or the equipment and consumables that sit around them. This is not opportunistic dabbling. It looks like a thesis being built position by position.
Second, Catamaran keeps its tickets small. Nothing in this cluster is a control stake, and Foseco at 0.74% sits below the 1% threshold at which a shareholder must be named in the quarterly pattern. Unless the office adds more, this holding will not appear in the September filing at all. Investors waiting for the shareholding pattern to confirm it will wait a long time, which is precisely why the bulk deal record matters.
Third, the entry point was made by someone else. Catamaran did not force this open. A British group needed the cash and a regulator-driven float expansion did the rest. The lesson for anyone tracking star investors is that conviction and opportunity are different things, and the filings rarely tell you which one you are looking at. Here, for once, they do.
A good idea would be to add this stock to a watchlist and keep a close eye on it in the near future.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.


