



When you buy a new car today, you are paying for much more than an engine and four wheels. Bigger touchscreens, illuminated logos, chrome trims and premium interiors have quietly become selling points, creating a new opportunity for the companies supplying these parts.
SJS Enterprises is one of them.
The company makes many of the visible components that give a car its premium look, from badges and dashboard finishes to chrome trims and is now moving into products such as protective glass for digital screens. The shift matters because instead of relying only on more cars being sold, SJS wants to earn more from every vehicle that leaves the factory.
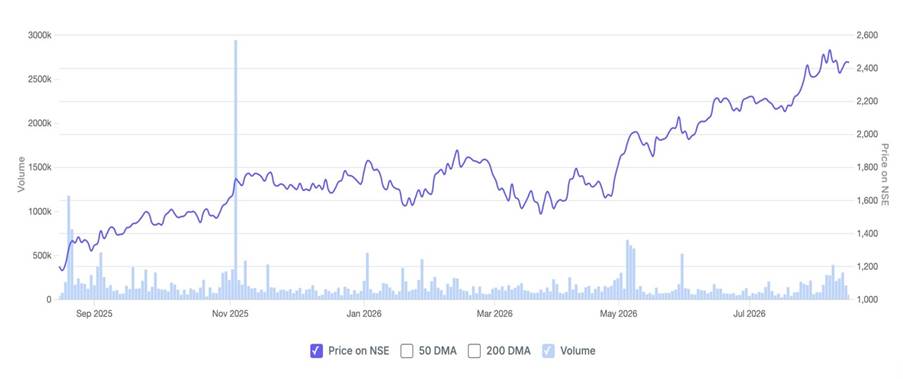
SJS Enterprises 1-Year Share Price Chart
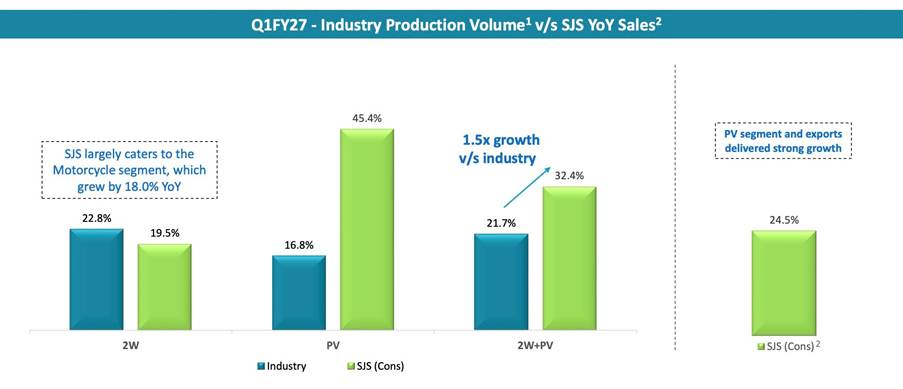
The strategy already seems to be paying off. While the combined passenger vehicle and two-wheeler industry grew 21.7% in the June quarter, SJS’s automotive business grew 32.4%, extending its streak of outperforming the industry to 27 consecutive quarters.
The quiet shift happening inside SJS
Most auto component companies wait for the industry to grow. SJS is trying to make sure it grows even when carmakers make better-looking cars.
Think about what has changed inside a modern vehicle. A dashboard that once had basic plastic panels now has chrome trims, textured surfaces, illuminated logos and large digital displays. None of these replaces the engine. They simply increase the value of what goes inside the car.
Join now
SJS wants a bigger share of that wallet.
The shift is visible in the numbers too. A few years ago, it supplied products worth roughly Rs 1,200-1,500 for a vehicle. After adding Walter Pack India’s premium interior technologies and SJS Decoplast’s chrome-plated parts, that figure has climbed to around Rs 3,500-5,000, with newer products expected to push it higher still.
That is an important shift because selling one more component to an existing customer is often easier than finding an entirely new customer. It also explains why management keeps talking about premiumization rather than simply chasing higher vehicle volumes. New-age products already contribute about 24% of consolidated revenue, giving the company a larger base to build on.
The strategy is already showing up in the numbers. While the combined passenger vehicle and two-wheeler industry grew 21.7% year-on-year in Q1FY27, SJS’s automotive business expanded 32.4%. Passenger vehicle revenue jumped 45.4%, suggesting that richer content inside newer vehicles is becoming as important as the number of vehicles being sold.
The company also reported its highest-ever quarterly revenue of Rs 261 crore in Q1FY27, up 24.5% year-on-year. Earnings Before Interest, Tax, Depreciation and Amortisation rose 36.2% to Rs 80 crore, while the EBITDA margin expanded to 30% from 27.6%.
The reported profit after tax grew 115% year-on-year to Rs 74.4 crore, but that number includes a one-time gain from the sale of an old Bengaluru facility. Excluding that exceptional item, adjusted profit after tax still rose 45.2% to Rs 50.3 crore, giving a better picture of how the core business performed.
The next upgrade could be inside the screen
If chrome trims were yesterday’s upgrade, digital displays could become tomorrow’s. SJS has tied up with Hong Kong-based BOE Varitronix to manufacture automotive display solutions in India, with commercial production expected from Q2FY28. At first glance, it looks like another product launch. It is actually a bet on where vehicles themselves are headed.
Management argues that many electric vehicle makers still import displays and instrument clusters. As those components gradually get localised, products such as cover glass could become a new revenue stream across both four-wheelers and two-wheelers.
That explains why the company has already created a wholly owned subsidiary for the cover glass and display business and begun preparing manufacturing capacity well before volumes arrive.
Management believes the opportunity could become meaningful over the next few years. It estimates the market for these products could reach Rs 5,000-7,000 crore by FY30 and hopes to build a meaningful presence in that space. Whether it reaches those ambitions remains to be seen, but the company is positioning itself before that market becomes crowded.
Exports are becoming another growth lever
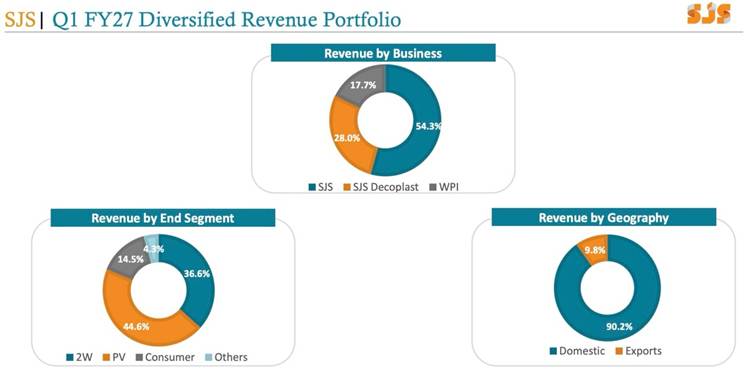
The story does not end with India. Exports still contribute less than a tenth of consolidated revenue, but they are growing much faster than the domestic business.
Export revenue jumped 83.2% year-on-year in Q1FY27 to around Rs 25.6 crore and management continues to target exports contributing 14%-15% of revenue by FY28. That target is not based on one large customer alone.
Management says it is expanding both its customer base and product mix, with discussions underway across multiple product categories and geographies. The company is also strengthening its presence in markets such as Germany, Turkey, Brazil, Argentina and South Korea, while expanding across Association of Southeast Asian Nations countries.
Walter Pack India could become an important contributor here. The subsidiary is preparing supplies for global customer programmes from India, although the timing will ultimately depend on customer launches. Another factor worth watching is that the non-compete agreement with Walter Pack Spain expires in January 2027, which could gradually open up additional export opportunities.
A balance sheet built for expansion
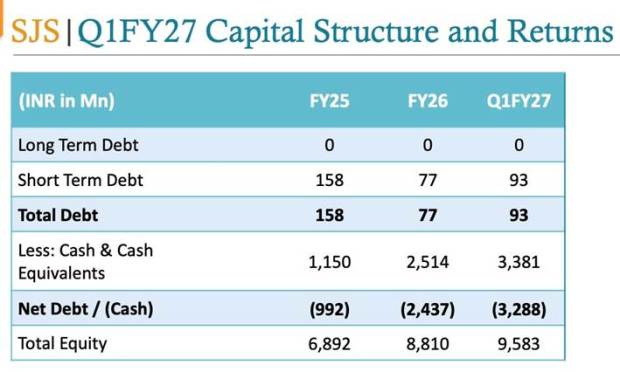
Growth stories become much stronger when the balance sheet can support them. SJS entered Q1FY27 with cash and cash equivalents of about Rs 338 crore against total debt of just Rs 9.3 crore, leaving it with a net cash position of roughly Rs 329 crore. Long-term debt remains zero, giving the company considerable flexibility as it expands capacity.
The cash generation is equally impressive. Cash flow from operations stood at Rs 81 crore during the quarter, equivalent to 101.2% of Earnings Before Interest, Tax, Depreciation and Amortisation, while free cash flow reached nearly Rs 84 crore.
That financial strength is already being put to work. The new SJS Decoplast facility in Pune has commenced operations. Meanwhile, the optical display facility is ready with equipment on order and Bengaluru capacity expansion is progressing to support future business. Management has also said Decoplast’s expanded capacity can support an additional Rs 200-250 crore of annual sales over time, while the broader ambition is to double Decoplast’s revenue over the next three to four years.
The balance sheet also gives the company another option. Management continues to look at acquisitions and Walter Pack India itself has grown its revenue by roughly 1.5 times since becoming part of the group.
Returns that stand out
Few companies combine high margins with such a conservative balance sheet. Annualised Return on Capital Employed stood at 37.2% in Q1FY27, while Return on Equity was 20.3%. Those numbers reflect a business that has been able to grow without stretching its finances.
Management believes the story has another leg to play out. The company expects to outperform the underlying automotive industry by 1.5-2 times in FY27, supported by premiumisation, a healthy order book, an expanding customer base and higher exports. It continues to target exports contributing 14-15% of consolidated revenue by FY28, up from 9.8% in Q1FY27, while investments in Decoplast, cover glass and newer premium products are expected to help increase the value of parts supplied to every vehicle.
The market has noticed this transformation and that creates the next question for investors.
At around Rs 2,437, SJS trades at roughly 41 times trailing earnings, well above its five-year median Price-to-Earnings multiple of about 29 times. Investors are already paying a premium for the expectation that the company will continue increasing its content per vehicle while expanding into displays and exports.
What lies ahead
That perhaps sums up where SJS stands today.
The company is no longer simply a supplier of badges and chrome trims. It is steadily becoming a company that earns more every time a car becomes more premium, whether through richer interiors, larger digital displays or higher-value decorative components.
The opportunity is becoming bigger. The only question investors need to answer now is whether the next phase of growth arrives quickly enough to justify the premium the market is already willing to pay.
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Manvi Aggarwal has been tracking the stock markets for nearly two decades. She spent about eight years as a financial analyst at a value-style fund, managing money for international investors. That’s where she honed her expertise in deep-dive research, looking beyond the obvious to spot value where others didn’t. Now, she brings that same sharp eye to uncovering overlooked and misunderstood investment opportunities in Indian equities. As a columnist for LiveMint and Equitymaster, she breaks down complex financial trends into actionable insights for investors.
Disclosure: The writer and her dependents do not hold the stocks discussed in this article. The website managers, its employee(s) and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.