



India’s electronics manufacturing services (EMS) sector is going through a quiet reset. For the past few years, it was a one-sided story. Stocks that had stronger PLI exposure and those that benefited from the China+1 play were assigned a higher premium. That equation is now changing.
The sharp correction in Dixon Technologies and Kaynes Technology suggests investors are becoming more selective, not necessarily about the EMS opportunity, but about which businesses deserve a premium.
The latest quarterly results from Syrma SGS Technology and Avalon Technologies offer an interesting contrast. Both delivered strong growth in Q1FY27, while their businesses are increasingly exposed to higher-value segments such as industrial, automotive, defence, railways and aerospace.
The next phase of the EMS story, therefore, may be less about how much a company manufactures and more about what it manufactures, for whom, and how much value it captures.
Join now
The Numbers Are Getting Bigger
Avalon and Syrma have been scaling their operations at an aggressive pace, and the numbers reflect that too.
For Syrma SGS, the growth trajectory is particularly striking. After reporting a 19% YoY drop in revenue in Q1FY26, the company delivered four consecutive quarters of accelerating growth: 38% in Q2, 45% in Q3, 58% in Q4 and 68% in Q1FY27. This is important because the recovery is not being driven by a single strong quarter; growth has accelerated for four consecutive quarters.
Accelerating Revenue Growth
| Q1FY26 | Q2FY26 | Q3FY26 | Q4FY26 | Q1FY27 | |
| Syrma SGS | 944 | 1,146 | 1,264 | 1,465 | 1,589 |
| YoY Sales Growth (%) | -19.0% | 38.0% | 45.0% | 58.0% | 68.0% |
| Avalon Technology | 323 | 382 | 418 | 480 | 484 |
| YoY Sales Growth (%) | 62.08% | 39.07% | 48.67% | 40.0% | 49.83% |
The growth trajectory is equally strong in Avalon. After moderating to 39% in Q2, revenue growth remained close to 50% in Q3FY26 and Q1 FY27. Revenue has increased from ₹323 crore in Q1 FY26 to ₹484 crore in the latest quarter.
Growing at such rates would have historically commanded a premium. But a more important question is whether this growth can translate into structurally higher margins and cash generation.
EBITDA Margins Reveal Operational Divergence
EBITDA Margin Profile
| Period | Q1FY26 | Q2FY26 | Q3FY26 | Q4FY26 | Q1FY27 |
| Syrma SGS Technology | 10.0% | 10.1% | 12.6% | 11.9% | 10.2% |
| Avalon Technology | 9.2% | 10.1% | 11.5% | 11.8% | 12.0% |
The margin trajectory, however, tells a more nuanced story. Avalon’s EBITDA margin has expanded steadily from 9.2% in Q1 FY26 to 12% in Q1 FY27. That is a meaningful improvement for an EMS company because it shows that revenue growth is translating into better operating economics.
Syrma’s margin story is less linear. EBITDA margin rose from 10% in Q1 FY26 to 12.6% in Q3, before moderating to 11.9% in Q4 and 10.2% in Q1 FY27.
Avalon’s margin trajectory is particularly encouraging because the expansion has occurred alongside strong revenue growth. Syrma, in contrast, has delivered faster revenue growth but has yet to demonstrate the same consistency in margins.
The More Interesting Story is What They Are Manufacturing
For years, investors broadly classified EMS as one theme. PLI incentives, China+1, electronics exports, smartphone manufacturing, and capacity expansion were all part of the same investment thesis.
But as the industry matures, the market is separating companies based on what they manufacture, who they manufacture for, and how much value they capture. That distinction matters because not all electronics manufacturing carries the same economics.
This is where Syrma and Avalon have differentiated themselves from some of the larger EMS names.
Syrma SGS serves a diverse set of industries, including automotive and EVs, healthcare and MedTech, consumer electronics, industrial IOT, railways, and defence. On the other hand, Avalon has exposure to aerospace and defence, clean energy (solar and hydrogen), railways, telecom, and industrial automation.
In these industries, supplier qualification can be lengthy and demanding. But once a supplier is qualified, replacing it is not always straightforward, particularly in sectors where reliability, product quality and regulatory compliance are critical. These segments can offer greater value addition and potentially stronger customer stickiness than a pure high-volume assembly business.
In other words, the opportunity is no longer simply to manufacture more electronics. It is to manufacture more complex electronics.
Growing International Presence
Geographic diversification adds another layer to the story. Avalon already derives 59% of revenue from the US, while exports contributed nearly 24% of Syrma’s Q1FY27 revenue. This gives both companies access to global customers. At the same time, it also exposes them to currency, geopolitical and demand risks.
Order Books Are Becoming More Important
For an EMS company, the order book is arguably more important than the headline revenue number. It shows what is coming next and what to expect.
Syrma SGS has an order book worth approximately ₹6,770 crore at the end of June 2026. That is equivalent to around 1.4 times its FY26 revenue of ₹4,819 crore.
The order book is relatively diversified. Automotive accounts for around 29%, consumer electronics 30% and industrial products 24%. Healthcare, including MedTech, contributed another 7%, while IT and railways together accounted for about 9%.
Avalon’s order book is similarly significant relative to its size. The company had ₹2,208 crore of executable orders, equivalent to around 1.38 times its FY26 revenue. Beyond this, Avalon had another ₹1,256 crore of long-term contracts executable over 14 months to three years.
The order books provide meaningful revenue visibility, but execution remains the key variable. For investors, the quality and mix of the order book may matter more than its absolute size.
Growth Is Strong, But Cash Flow Needs Watching
The strong growth numbers also need to be viewed alongside cash generation. EMS is a working-capital-intensive business, as companies often need to build inventory and fund receivables as they scale.
Avalon’s cash conversion remains an area to watch, as it has not been consistent over the years. However, on a year-on-year basis, its CFO-to-operating profit ratio improved to 53% in FY26 from 39% in FY25.
Avalon Technologies: Cash Flow Statement
| Period | FY24 | FY25 | FY26 |
| Cash from Operating Activity | 17 | 25 | 57 |
| Cash from Investing Activity | -146 | 54 | -64 |
| Cash from Financing Activity | -251 | -52 | 8 |
| Free Cash Flow | -18 | -21 | 4 |
| CFO/OP | 54% | 39% | 53% |
The company is still investing heavily to support its next phase of growth. If cash conversion remains volatile even as earnings grow, investors may question the quality and sustainability of that growth.
Syrma’s cash conversion looks stronger. The company’s CFO-to-operating profit ratio was 69% in FY26. In the previous financial year, it was around this level.
Syrma SGS Technology: Cash Flow Statement
| Period | FY24 | FY25 | FY26 |
| Cash from Operating Activity | -109 | 176 | 290 |
| Cash from Investing Activity | -9 | -103 | -736 |
| Cash from Financing Activity | 150 | -71 | 558 |
| Free Cash Flow | -446 | 4 | 114 |
| CFO/OP | -27% | 73% | 69% |
Free cash flow also turned positive at ₹114 crore in FY26, compared with just ₹4 crore in FY25. For investors, this means the next phase of the story cannot be judged by revenue and EBITDA alone. The real test will be whether the rapid growth in earnings eventually translates into stronger operating cash flows and free cash generation.
Valuations Leave Little Room for Error
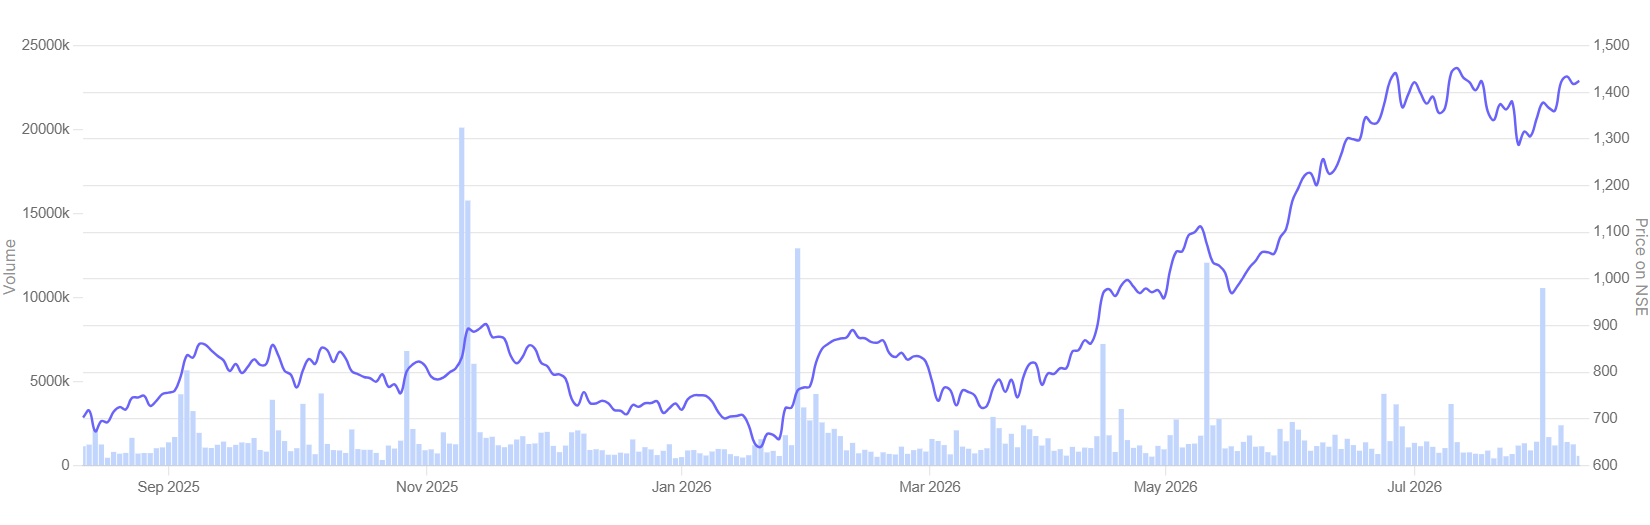
Over the last 12 months, both Syrma SGS and Avalon have rallied, delivering nearly 100% and 120% returns, respectively. Dixon Tech, meanwhile, has seen its stock drop 10% over this time period.
The price surge in the case of Syrma and Avalon has pushed the Price-to-earnings (PE) multiple of both stocks higher.
Syrma SGS Technologies: 1-year Stock Price Chart
Avalon Technologies: 1-year Stock Price Chart
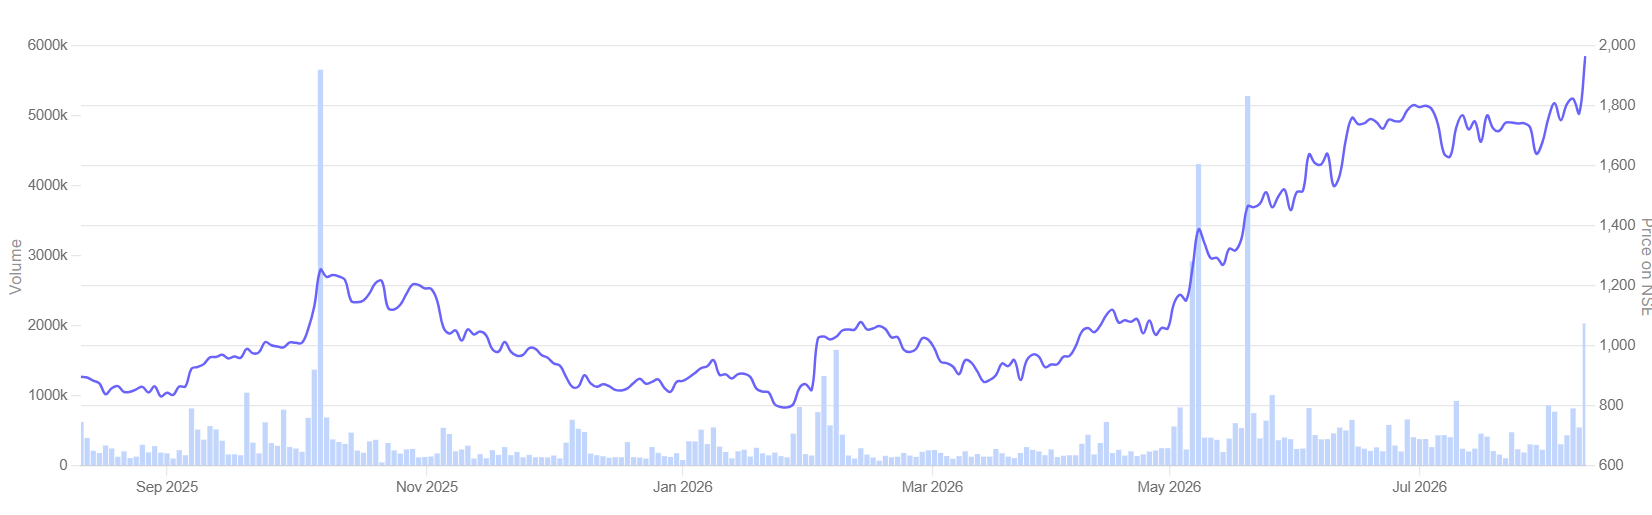
As of August 8, 2026, Syrma SGS Technology has a trailing PE multiple of 74X, while Avalon’s is nearly 98X. Both have a listing history of less than five years; therefore, it’s difficult to compare against the historical averages. Dixon Tech’s current P/E is 46.2X, which is largely into consumer and home electronics.
The premium valuation reflects more than revenue growth. Investors are effectively paying for sustained growth, improving margins, stronger order-book visibility, and the possibility that both companies can move further up the value chain.
For investors, the key metrics to monitor will be order book momentum, margin expansion, and the CFO-to-operation profit ratio. If any of the metrics shows moderation or slowdown, then the premium valuations will be difficult to sustain.
The EMS Story Is Entering Its Next Phase
India’s EMS opportunity is still intact. But the market is becoming more selective about how that opportunity should be valued. The first phase was about capacity, scale and PLI-led manufacturing. The next phase could be about complexity, customer stickiness and value addition.
Syrma SGS and Avalon are positioning themselves for this transition. Both are growing rapidly, have sizeable order-book visibility and are increasing their exposure to automotive, industrial, healthcare, defence and other specialised electronics.
For investors, the takeaway is less about picking a side in the smallcap vs largecap EMS debate and more about paying attention to what is actually inside the order book, and how much value the company can capture from it. Add these stocks to your watchlist and monitor how they execute their growth plans.
Disclaimer:
Note: We have relied on data from www.Screener.in throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Deepan Datta has spent over a decade studying stocks and mutual funds. His passion is to uncover interesting stories in the financial markets and share them through his writings with investors at large. He is focused on delivering clear, easy to understand and research-backed insights. Deepan began his career as a Research Associate at S&P Global, where he developed a strong foundation in financial research and data analysis.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, their employees (s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The content of the articles and the interpretation of data are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources and only after consulting such independent advisors as may be necessary.