



Buying medicines in India has traditionally been a neighborhood-driven experience. A customer walks into a local pharmacy, asks for a medicine, and often gets it within minutes. Behind that simple transaction is a large, fragmented distribution network connecting pharmaceutical companies, distributors, and thousands of pharmacies across the country.
This network is now gradually changing. According to Medplus’s FY26 Annual Report, India’s pharmacy retail and distribution market is valued at around US$24-27 billion (around ₹2.3 lakh crore at the lower end) and is growing at about 10% CAGR.
Rising healthcare spending, increasing chronic disease cases, greater health awareness and the expansion of organized pharmacy chains are supporting this growth. The shift is also changing how medicines reach consumers.
Organized retailers and digital platforms are investing in technology, larger store networks, inventory management and home delivery. At the distribution level, scale and supply chain efficiency are becoming increasingly important.
As the market becomes more organized, pharmacy retailers with large networks and well-operated systems could capture a larger share of this market. Against this backdrop, this article looks at two listed pharmaceutical distributors.
#1 Entero Healthcare: From Distribution to Demand Creation
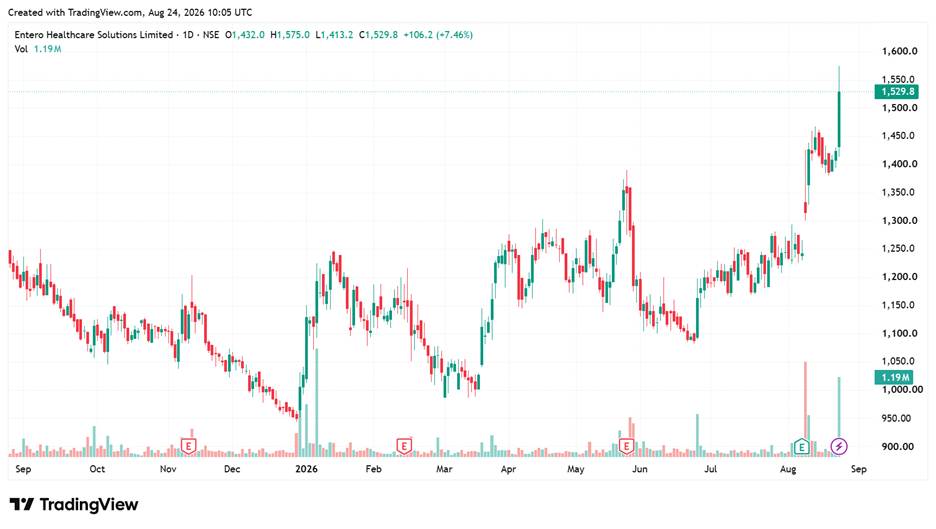
Entero Healthcare Solutions is one of India’s largest and fastest-growing healthcare product distributors in terms of revenue. The company operates a differentiated business model that integrates two primary service capabilities to add value across the healthcare supply chain. This includes Core Distribution and Integrated Commercial Solutions.
Within Core Distribution, Entero provides end-to-end distribution solutions for healthcare products. The product range spans pharmaceuticals, over-the-counter products, medical devices, nutraceuticals, surgical consumables, and vaccines. The company serves over 72,000 retail pharmacies and more than 2,300 hospitals as of Q1FY27.
Join now
Demand Generation Over Fulfillment
Unlike traditional distributors, Entero actively helps healthcare brands create demand for their products through its Integrated Commercial Solutions business. It provides pharmacies with a technology-enabled supply chain solution, including ordering, real-time pricing and inventory visibility, and complete tracking of manufacturer discount schemes.
Entero reported strong top-line growth in Q1FY27. Revenue grew 38.2% year-on-year to ₹1,940 crore, driven by both organic and inorganic growth triggers. Organic revenue grew 17.8% on a reported basis (and 19.6% on a like-for-like basis), beating the Indian Pharmaceutical Market growth rate of 13.8%.
Decoding the 38.2% Q1FY27 Revenue Surge
This organic outperformance is primarily driven by higher wallet share from existing customers and an expanding customer base. This growth is anchored in Entero’s core Unique Selling Proposition: superior product availability and higher fill rates compared to traditional distributors.
Inorganic growth contributed another 20.4%. Inorganic growth was driven by the spillover impact of acquisitions completed in FY26. The management’s priority for FY27 is organic growth and integrating its existing national footprint. With estimated revenues of ₹1,000+ crore in FY27, the medtech segment serves as a major growth engine.
Expanding Margins Through the MedTech Pivot
In MedTech, it focuses on In Vitro Diagnostics (IVD), Cardiovascular and Orthopedic devices. Surgical Consumables and Imaging are also major focus areas under MedTech. Together, the revenue split within MedTech stands at Consumables (20%), IVD (17%), Cardiovascular + Ortho (15%), Imaging (14%), and Others (34%).
Entero plays an active role in demand generation. Rather than acting purely as a logistics fulfillment provider, it assists manufacturers with end-to-end promotion. This creates stronger growth opportunities and higher margins than traditional pharma distribution.
Entero is actively shifting its business mix, distribution methods, and capital allocation strategy to prioritize margin expansion over pure volume expansion. In its initial years, Entero expanded inorganically by completing 51 acquisitions since inception. However, the company completed zero new acquisitions during Q1FY27 as it now focuses on consolidation.
Rationalizing Capital: The Zero-Acquisition Strategy
The company is also shifting from fulfilling low-margin demand to driving demand. This includes deploying medical representatives to promote products directly to healthcare providers. This is evident in its MedTech segment, where Entero manages end-to-end promotion and captures significantly higher gross margins.
Entero is also exiting low-margin, capital-intensive sub-distribution accounts. This business rationalization is already showing results. EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortization) margins expanded by 143 bps to 5.0% in Q1FY27. As a result, net profit grew by 73.3% to ₹52 crore.
Further margin expansion is expected to be driven by procurement efficiencies, a rising mix of high-margin MedTech contracts, and the ongoing rationalization of low-margin accounts
FY27 Guidance and Cash Flow Targets
Looking ahead, Entero has guided for 23% revenue growth (excluding any new acquisitions) and 5% margins in FY27. Management expects the platform to grow organically at over 20% annually over the next 3-4 years. It is targeting an annual EBITDA-to-operating cash flow (OCF) conversion rate of 50%.
#2 Medplus Health Services: From Pharmacy Stores to a Healthcare Platform
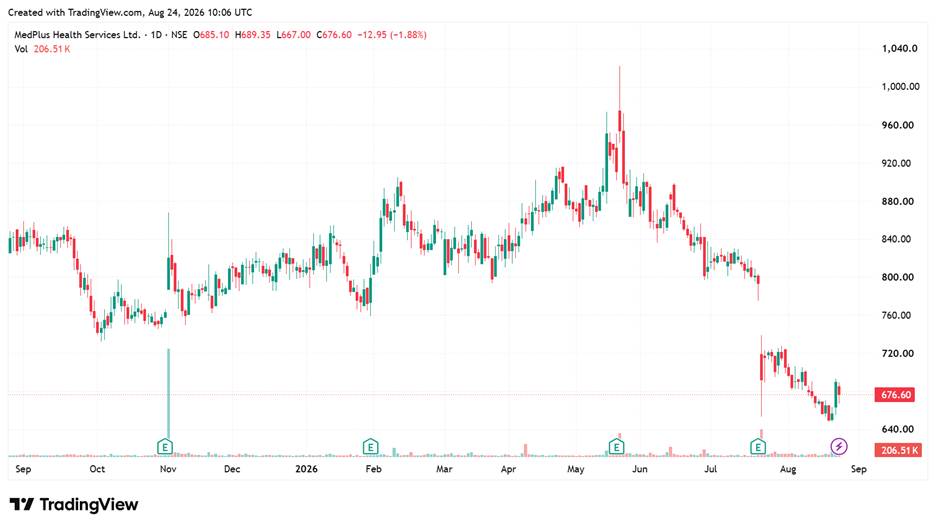
Medplus Health Services is India’s second-largest pharmaceutical retailer and a pioneer in omni-channel pharmacy retailing. As of 30 June, 2026, Medplus operates a network of 5,476 stores. These stores span 13 states and 1 union territory, covering approximately 850 cities. Its long-term goal is to have 20,000 to 40,000 stores nationwide.
The 40,000-Store Masterplan and Densification
Medplus expands using a cluster-based strategy. It prioritizes deeper penetration in cities where it already has established operations. Its target market is Metro and Tier-1 cities first, followed by Tier-2 areas and beyond. Medplus focuses on actively opening new stores in close proximity to mature ones (densification).
Management views self-cannibalization as an effective model to capture maximum local market share and shun competition. Mature stores (those older than 24 months) achieve a Store Level Return on Capital Employed (ROCE) of over 60%. Newer stores mature to become P&L accretive under 24 months.
Pushing High-Margin Private Labels
As of June 2026, approximately 27% of the Medplus store network has been in operation for less than two years, and the remaining 73% has been in operation for two years or more. This means most stores are mature. The company stores over 51,000 stockkeeping units (SKUs) in warehouses. Medplus has built a large private label portfolio with over 1,550 SKUs.
In Q1FY27, private label products accounted for 20% of revenue, with pharma private labels representing 10.7% and non-pharma representing 9.3%. Pharma private labels are sourced from major manufacturers supplying India’s top pharmaceutical firms. Beyond pharmacy, Medplus is actively scaling its diagnostics business.
Shifting Expansion to the Franchise Model
The company aims to maintain an annual guidance of 800 net store additions for FY27. Expansion is expected to split 50/50 between the company and the franchise. However, in Q1FY27, franchise stores accounted for 131 of the 146 net stores. Franchise sales have a lower gross margin profile, but offer zero inventory capex and a higher return on investment.
Medplus continues to grow beyond Maharashtra into Chhattisgarh, Madhya Pradesh, and Kerala. Once these states mature and turn profitable, they plan to deploy capital in North and West. It relies on franchise mode to expand.
Q1FY27 Financials: Strong Top-Line, Pressured Margins
Overall, pharmacy business revenue grew 21.8% year-on-year to ₹1,839.9 crore in Q1FY27. This business accounted for 97.8% of consolidated revenue. However, operating EBITDA fell 14.8% to ₹58.8 crore, while margins fell 140 bps to 3.2%.
Diagnostics is also growing. Diagnostics segment revenue increased 22.4% to ₹37.1 crore in Q1FY27. Operating EBITDA increased 59.6% to ₹6.6 crore from ₹4.1 crore in Q1FY26. The business has an active user base of 2 lakh clients. Pathology business margins expanded to 17.8% from 13.6% in Q1FY26.
On a consolidated level, revenue grew 21.8% year-over-year to ₹1,879.6 crore in Q1FY27. This growth was supported by steady expansion of the physical footprint and deep penetration in cluster markets. Operating EBITDA fell 10.6% to ₹65.1 crore, as margins declined 120 bps to 3.5%. Consequently, net profit fell 21.7% to ₹33.2 crore.
Entero vs Medplus: Here’s What the Numbers Say
| Particulars | Entero Healthcare | Medplus Health |
| Business Model | Healthcare distribution + MedTech | Pharmacy retail + diagnostics |
| Q1FY27 Revenue (Growth) | ₹1,940 crore (+38.2% YoY) | ₹1,879.6 crore (+21.8% YoY) |
| Q1FY27 EBITDA Margin | 5.0% | 3.5% |
| Q1FY27 Net Profit | ₹52.0 (+73.3% YoY) | ₹33.2 crore (-21.7% YoY) |
| FY27 Growth Guidance | 23% revenue growth | 800 net store additions |
| Key Growth Driver | MedTech + organic distribution growth | Store expansion + private labels + diagnostic |
| Key Monitorable | Organic growth and margin expansion | Store productivity and margin recovery |
The table shows that Entero is currently growing faster and delivering higher margins, with revenue growth of 38.2% and an EBITDA margin of 5% in Q1FY27. Medplus, meanwhile, is growing more slowly, while its profitability declined during the quarter.
Entero’s growth is being supported by MedTech and organic distribution, whereas Medplus is relying on store expansion, private labels and diagnostics.
Bridging the Valuation Gap
Medplus Health Return on Capital Employed (ROCE) and Return on Equity (ROE) are better than Entero. That said, both companies are still in expansion mode. As these investments mature and operating leverage improves, return ratios have scope to strengthen further.
On valuation, MedPlus trades at a discount to both the industry median multiple and its 3-year historical median. Entero, on the other hand, trades at a premium to the industry median and its 2.5-year historical median. But note that both have short trading histories.
| Peer Comparison (X) | ||||
| Company | Price-to-Earnings Multiple | Return Ratios | ||
| Company | 3Y Median | ROCE (%) | ROE (%) | |
| Medplus Health | 38.3 | 72.9 | 12.6 | 11.6 |
| Entero | 52.1 | 51.2 (2.5Y) | 10.5 | 6.9 |
| Industry | 45.2 | 11.5 | 9.3 | |
Entero Healthcare and Medplus Health are approaching India’s pharmacy distribution and retail opportunity from different ends of the value chain. Entero is building scale in healthcare distribution and MedTech, while Medplus is expanding its pharmacy network and private label business.
Entero offers faster revenue growth, but Medplus currently stands out on return ratios and valuation. The key monitorable for both is whether expansion translates into better margins and cash generation. You could keep these names on your watchlist to track their execution.
Disclaimer
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely used, and accepted source of information only when the data was unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.