



India’s power story is creating an opportunity in a product most investors rarely notice: transformer oil. As the country builds more power plants, transmission lines and substations, it also needs more transformers. And every transformer needs oil to cool and insulate it. This makes transformer oil an indirect beneficiary of the country’s growing power infrastructure.
The opportunity is sizable. India has planned around ₹9 lakh crore of investment to overhaul and expand its national power transmission grid under the National Electricity Plan. Demand for transformer oil is not limited to India; it is expanding globally as well.
Join now
The global transformer oil market, valued at about $2.9 billion in 2025, is expected to reach $7.5 billion, or nearly ₹70,000 crore, by 2033. The next leg of demand could come from India’s clean energy push. India is targeting 500 gigawatts (GW) of non-fossil fuel capacity by 2030, which will require new transmission lines to move electricity from renewable-rich states to consumption centres.
The Green Energy Corridor is part of this build-out. Add to this the growing power demand from manufacturing, urbanisation, and data centres, and the need for transformers is growing. For transformer oil manufacturers, India’s power expansion is quietly creating a large addressable market. Against this backdrop, let’s look at two leading transformer oil companies.
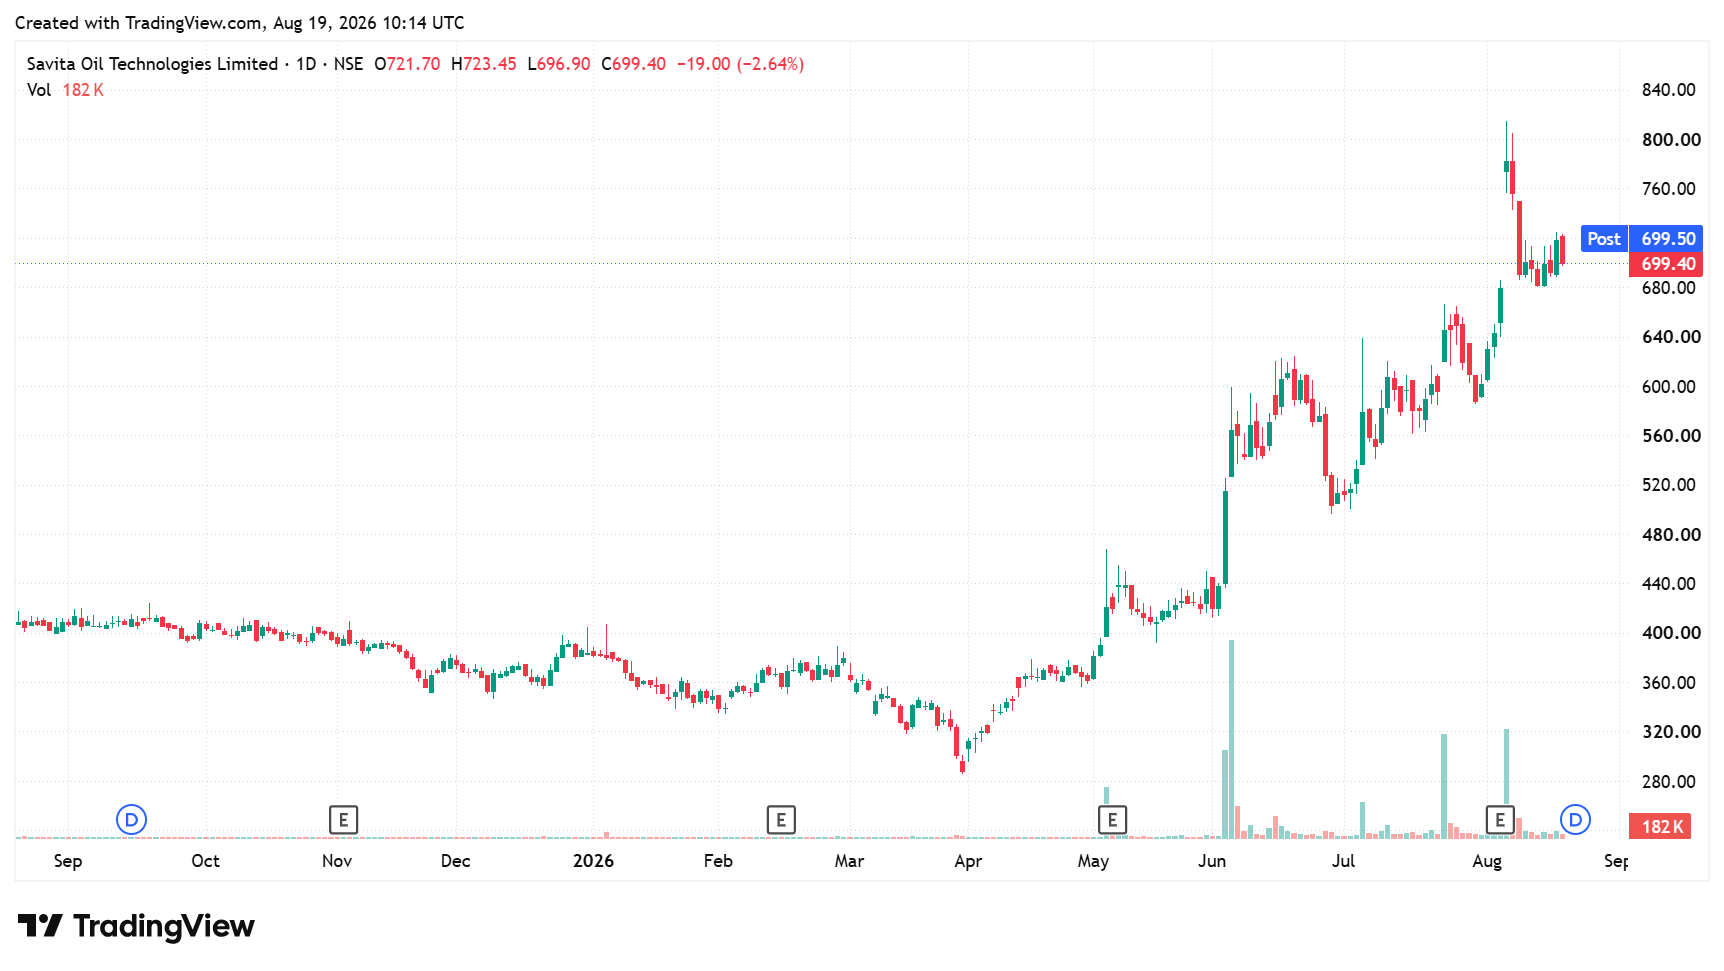
#1 Savita Oil: Specialty Oils With A Power Infrastructure Play
Savita Oil manufactures speciality petroleum products. Its main product is petroleum specialty oils, which account for 73% of the company’s revenue. The company also has a major presence in transformer oils, white and mineral oils, specialty fluids, and automotive lubricants.
The company has built a widespread distribution network across 75 countries. This includes 41 stock points, over 400 distributors, 1,500+ franchise dealers, and more than 20,000 retailers. Savita Oil’s revenue is split between 83% domestic sales and 17% exports.
Its transformer oil brands include TRANSOL, bioTRANSOL and TRANSOL Synth for the power and distribution sector. Notably, Savita Oil is the only global manufacturer offering a portfolio of mineral-, natural-, and synthetic-ester-based transformer oils. The company serves a diversified customer base, including BHEL, Crompton, Hitachi, ABB, and NTPC.
These oils prevent electrical discharge and remove intense heat inside distribution, power, and instrument transformers. Savita directly supplies utility and power companies globally, including transformer manufacturers, electricity boards, and power plant operators. While power transformer oils command high margins, distribution transformer oils offer the lowest margin.
Record Margins & One-Off Inventory Gains
The company’s revenue rose by 49.2% year-on-year to ₹1,512.7 crore in Q1FY27. EBITDA (Earnings Before Interest, Tax, Depreciation, and Amortisation) grew by 370.6% to ₹396.7 crore as margins expanded 1,790 bps to 26.2%. As a result, net profit surged almost 5x to ₹292 crore, up from ₹59 crore in Q1FY26.
This growth was primarily driven by higher prices for crude oil and refined products. Since crude oil is a key raw material for its product portfolio, Savita increased prices to reflect rising input costs. Further, inventory gains from old raw material stocks boosted margins. These benefits may be one-time.
Overall, the business performance was strongly supported by double-digit volume growth in both the lubricating oil and export divisions. The premium product SAVSOL Ester5 automotive lubricant range continued to outperform the broader market, scaling at 4X the industry growth rate.
Pivoting to EV & Data Centre Cooling
Additionally, Savita Oil has received several original equipment manufacturer approvals for its ester-based fluid range. Management states that the products have rapidly gained commercial traction. Management expects strong export demand in FY27. The company is also developing cooling fluids for data centres, energy storage systems, and electric vehicles.
#2 APAR Industries: Diversified Power Play With Transformer Oil Exposure
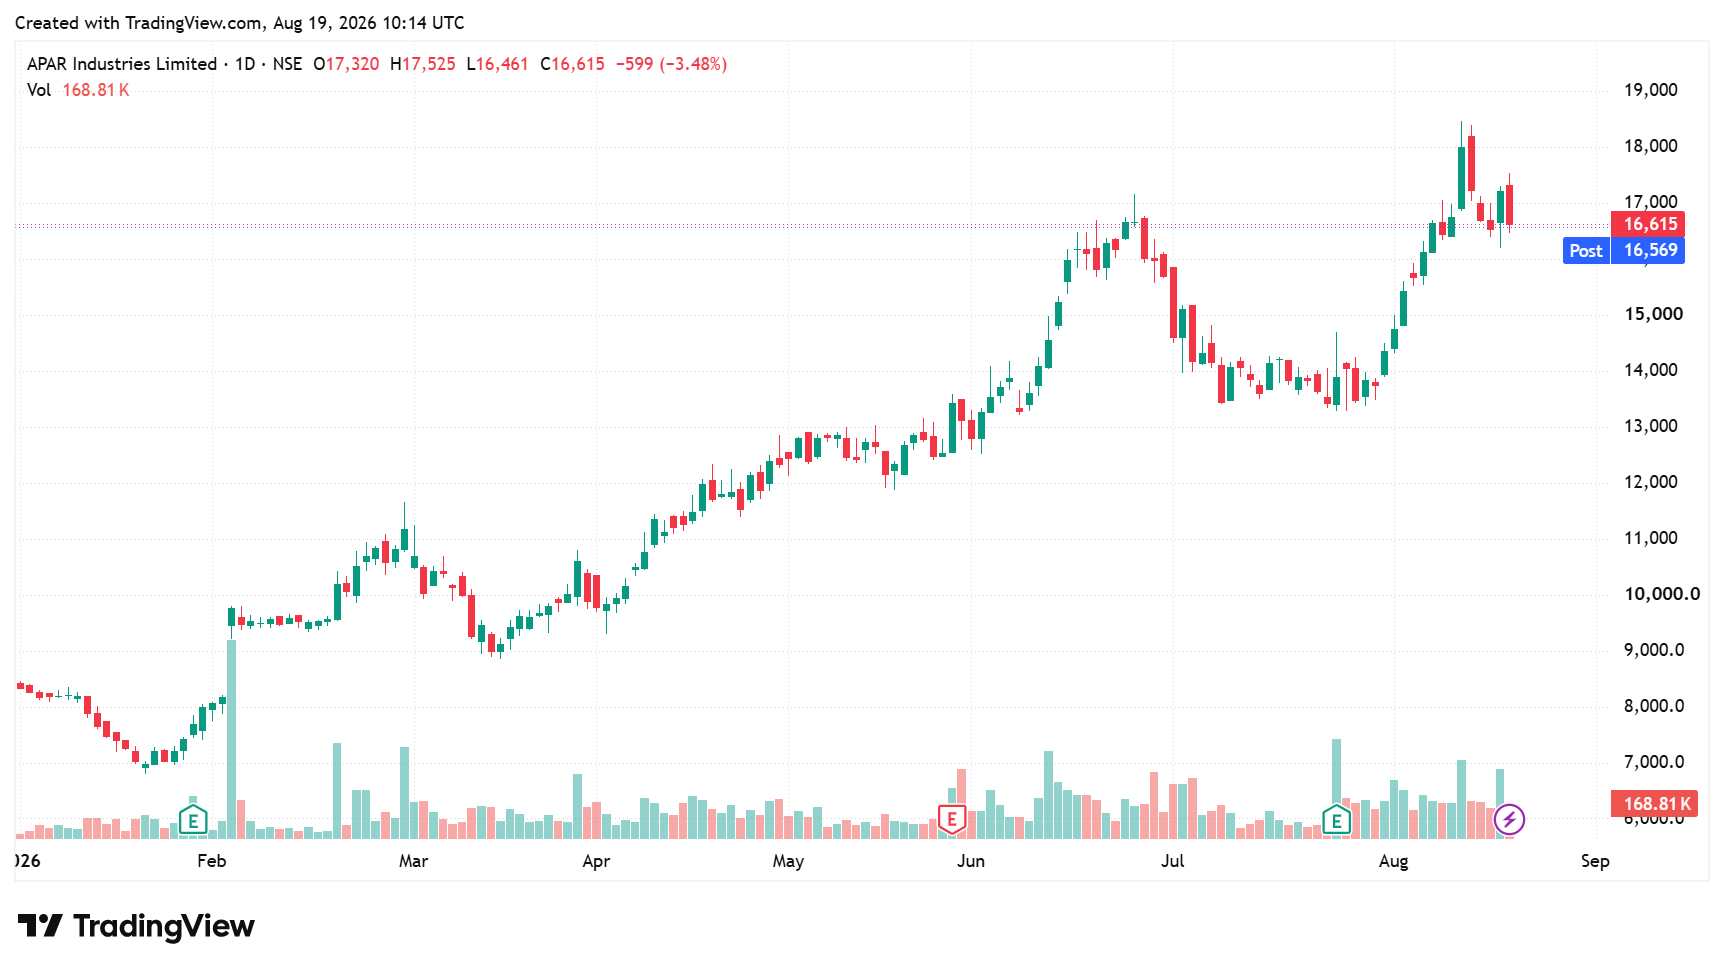
APAR Industries is a leading global industrial manufacturer operating across three diversified business divisions: Conductors, Speciality Oils, and Cables. The Conductor business is a major beneficiary of growing power transmission and distribution capex globally.
The Cables division manufactures power and specialty cables. The Oil Division (Specialty Oils) manufactures transformer insulating oils, automotive lubricants, and industrial lubricants. Transformer oils help insulate and cool power equipment while preventing leaks and sparks that can cause damage.
In the revenue mix, conductors accounted for 48.5% in Q1FY27, followed by cables (26.7%) and Oils (24.8%). In the geographic mix, the domestic market contributed 72.5% of revenue, and the rest came from exports (27.5%).
Expanding Margins Despite Supply Chain Disruptions
The Transformers and Specialty Oils division delivered a strong performance. Revenue grew by 34.7% year-on-year to ₹1,701 crore in Q1FY27, while volumes declined 13.7%. Volumes were lower due to supply chain disruptions. This was driven by an increase in EBITDA per kiloliter, which increased from ₹7,004 to ₹25,482.
This was also due to higher energy prices. EBITDA (after forex) increased 214.2% to ₹329 crore, while margins expanded 1,100 bps to 19.3%. APAR purchases approximately 65% of its oil under long-term contracts and 35% from the spot market. Thus, when energy prices rose, APAR benefited from selling at higher prices.
Defending Profitability: The Just-In-Time Pivot
As commodity prices fell from their peaks toward the close of June, APAR strictly followed accounting standards and made a provision of ₹93 crore to ₹94 crore for the oil division in Q1. Even after absorbing this provision, the division delivered high segment earnings. Management has now adopted a defensive position.
The company is intentionally reducing and optimising its specialty oils inventory. Management is also moving toward a just-in-time supply structure, which reduces working capital risk and limits potential margin erosion if commodity prices reverse sharply downward.
Consolidated Tally: A 77% Jump in Net Profit
From a consolidated perspective, revenue grew 29.1% year-on-year to ₹6,591 crore, supported by a 36.9% increase in domestic revenue. EBITDA (post-forex) increased 62.7% to ₹814 crore, while margins expanded 260 bps to 12.4%. Consequently, net profit rose 77.7% to ₹467 crore.
Fundamental Valuation: The Quality Premium Trade-Off
APAR Industries has stronger Return on Capital Employed (ROCE) and Return on Equity (ROE) than Savita Oil. Valuation-wise, APAR trades at a premium to both the 3-year historical average and the industry median. Savita Oil, on the other hand, trades at a discount to the historical median but in line with the industry median.
| Peer Comparison (X) | |||||
Company | Price-to-Earnings Multiple | Return Ratios | |||
| Company | 3Y Median | Industry Median | ROCE (%) | ROE (%) | |
| Savita Oil | 11.2 | 18.9 | 11.2 | 14.0 | 8.9 |
| APAR Industries | 57.9 | 38.6 | 28.4 | 31.1 | 20.2 |
| Source: Screener.in (As of 19 August 2026) | |||||
The transformer oil opportunity is closely tied to India’s expanding power infrastructure, but the two companies offer different ways to play the theme. Savita Oil combines transformer oils with speciality products, exports and newer cooling applications.
APAR benefits from its larger presence across conductors, cables and oils. However, recent earnings should be viewed in the context of commodity prices and inventory gains, which may not be sustainable. Meanwhile, keep them on your watchlist.
Disclaimer:
Note: Throughout this article, we have relied on data from http://www.Screener.in and the company’s investor presentation. We used an alternative, widely accepted source of information only when the data were unavailable.
The purpose of this article is only to share interesting charts, data points, and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educational purposes only.
About the Author: Madhvendra has been deeply immersed in the equity markets for over seven years, combining his passion for investing with his expertise in financial writing. With a knack for simplifying complex concepts, he enjoys sharing his honest perspectives on startups, listed Indian companies, and macroeconomic trends.
A dedicated reader and storyteller, Madhvendra thrives on uncovering insights that inspire his audience to deepen their understanding of the financial world.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article.
The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein. The articles’ content and data interpretation are solely the personal views of the contributors/ writers/authors. Investors must make their own investment decisions based on their specific objectives, resources, and only after consulting such independent advisors as may be necessary.