



The Anatomy of Inaction: How a ₹3,600Cr Portfolio Survives on Stillness
There is a kind of discipline that does not photograph well. No launch event, no television appearance, no quarterly reshuffle for the newswires to chew on.
That is the Nemish Shah portfolio. Five companies: a textile machinery maker, a glass company, an air compressor firm, a sugar mill and a clothing brand. He has held them atleast since 2015. He might have held it for longer, but Trendlyne shows data only that far.
What makes the book worth a second look is not the stillness. It is what the five businesses have been doing while he sat still. One just posted its best operating margin on record. Another posted an operating loss. Same portfolio, same quarter.
Nemish Shah Portfolio: All Five Holdings
Here is the entire portfolio as per the June 2026 filings, valued at recent closing prices.
| Stock | Stake | Shares held | Value (Rs cr) | Share of book |
| LMW | 8.6% | 9,13,873 | 1,793 | 49.0% |
| Asahi India Glass | 5.7% | 1,44,82,818 | 1,393 | 38.1% |
| Elgi Equipments | 1.7% | 53,60,000 | 340 | 9.3% |
| Bannari Amman Sugars | 2.6% | 3,25,000 | 130 | 3.6% |
| Zodiac Clothing | 1.5% | 4,05,124 | 3 | 0.1% |
| Total | 3,659 | 100% |
Two names carry 87% of the money. The smallest position is worth Rs 3 cr.
Join now
One detail is worth pausing on. Where his stake percentage has slipped, it is mostly not because he sold. In Asahi and Zodiac his share count has not changed at all. The percentage fell because those companies issued new shares. The only genuine selling in the book is 20,000 shares of LMW over the past year, out of more than 9 lakh held.
Let us look at his holdings to see if we can find a pattern in his stock picking style
#1 LMW: When Re-rating Outpaces Earnings
LMW, the company most people still call Lakshmi Machine Works, makes textile spinning machinery, CNC machine tools and heavy castings out of Coimbatore. It is 49% of his book, worth about Rs 1,793 cr.
Return on equity last year was 4.05%. Return on capital employed was 5.58%. FY26 profit came in at Rs 131 cr, which is 66% below the Rs 384 cr earned in FY23.
The composition of that profit matters too. On a trailing twelve-month basis, pre-tax profit is Rs 234 cr, of which Rs 136 cr is other income rather than operations. Strip it out and the operating business contributes under Rs 100 cr. The company is almost debt free and sits on a large treasury, so that income is real money. It is simply not manufacturing money.
The Growth Illusion: Profit Trajectory That Tells a Hump, Not a Slope
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 1,727 | 3,171 | 4,719 | 4,696 | 3,012 | 3,207 | 13% |
| EBITDA (Rs cr) | 71 | 247 | 450 | 435 | 142 | 170 | NM |
| Net Profit (Rs cr) | 131 | 181 | 384 | 374 | 103 | 131 | NM |
EBITDA here refers to operating profit before other income. The EBITDA and net profit growth rates are marked NM, meaning not meaningful. FY21 was a pandemic hit year with an operating margin of just 4.1%, against a normal range nearer 10%. Growth measured from that base flatters a recovery into a trend. The column of years tells the honest story, and it is a hump, not a slope.
The June 2026 quarter showed sales of Rs 861 cr with net profit of Rs 56 cr, better than a year earlier. Promoter holding is steady at 30.80%.
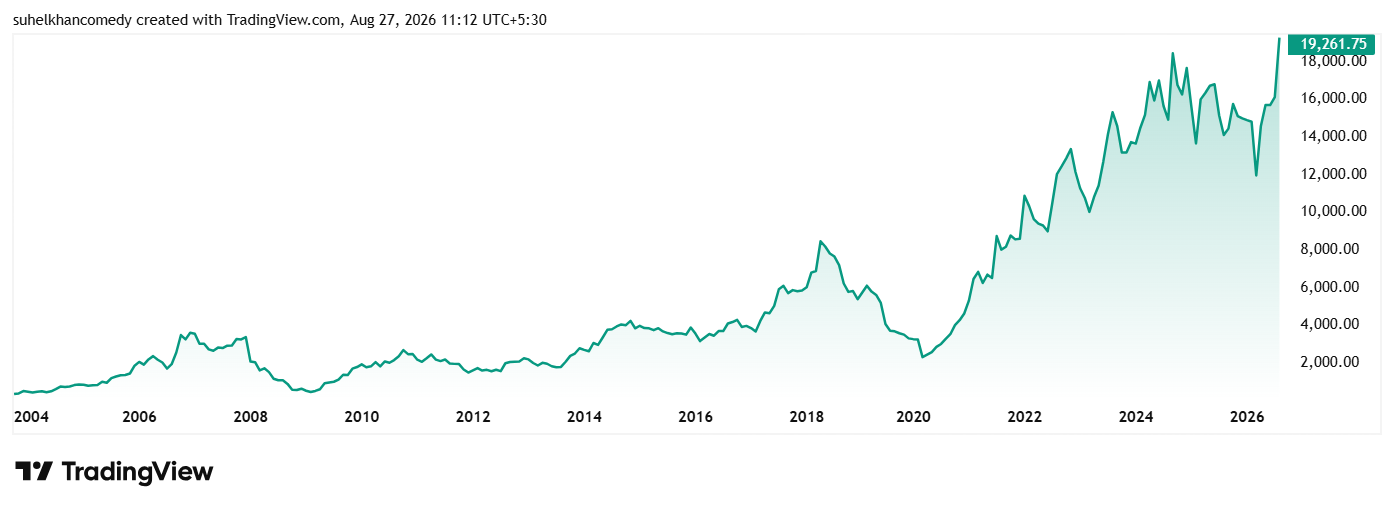
The share price of LMW has compounded at 17% a year in the last decade and the stock trades at a PE of 113x against an industry median of 34x.
The Decoupling of Profit and Price
Over the last decade, LMW sales have compounded at about 1% a year and profit has compounded at about minus 7% a year. The share price over the same decade has compounded at about 18% a year.
That gap is the entire argument. Nothing in the earnings explains the share price. The re-rating does.
Something may be behind it. On 11th August 2026 the company issued a postal ballot seeking shareholder approval to widen its stated objects and enter new businesses. On 7th August, CRISIL assigned it a fresh AA corporate credit rating with a stable outlook. LMW also runs an aerospace and advanced technology division and sits inside a defence themed index.
#2 Asahi India Glass: The Cost of Capacity
Asahi India Glass makes the glass on most Indian cars and a large share of the flat glass in Indian buildings. At Rs 1,393 cr it is 38% of the book.
For two years this was a story about spending. The company built new capacity, and the cost of that showed up in the accounts before any of the benefit did. In FY26 sales rose 9% to Rs 4,990 cr, yet net profit fell 6% to Rs 345 cr. The reason sits in two lines. Depreciation jumped 48% to Rs 285 cr as a new plant came onto the books. Interest rose 59% to Rs 204 cr.
Capex vs. Cash Flow: The Financial Toll of Asahi’s New Plant
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 2,421 | 3,170 | 4,019 | 4,341 | 4,594 | 4,990 | 16% |
| EBITDA (Rs cr) | 435 | 761 | 795 | 724 | 766 | 918 | 16% |
| Net Profit (Rs cr) | 131 | 343 | 362 | 325 | 367 | 345 | 21% |
EBITDA here refers to operating profit before other income. Sales for the quarter ending June 2026 were Rs 1,413 cr, up 15% year on year. Operating margin came in at 23%, the highest in the twelve quarters on record. Net profit was Rs 149 cr against Rs 55 cr.
The balance sheet moved too. The company raised equity during FY26, which lifted reserves from Rs 2,645 cr to Rs 3,907 cr and allowed borrowings to fall from Rs 2,696 cr to Rs 2,198 cr. That raise is also why the promoter stake reads 51.58% now against 54.19% a year ago, and why Shah’s own stake reads 5.7% instead of 6.0% despite him not selling a single share.
Domestic institutions noticed, lifting their holding from 1.63% in March 2025 to 5.35% by June 2026.
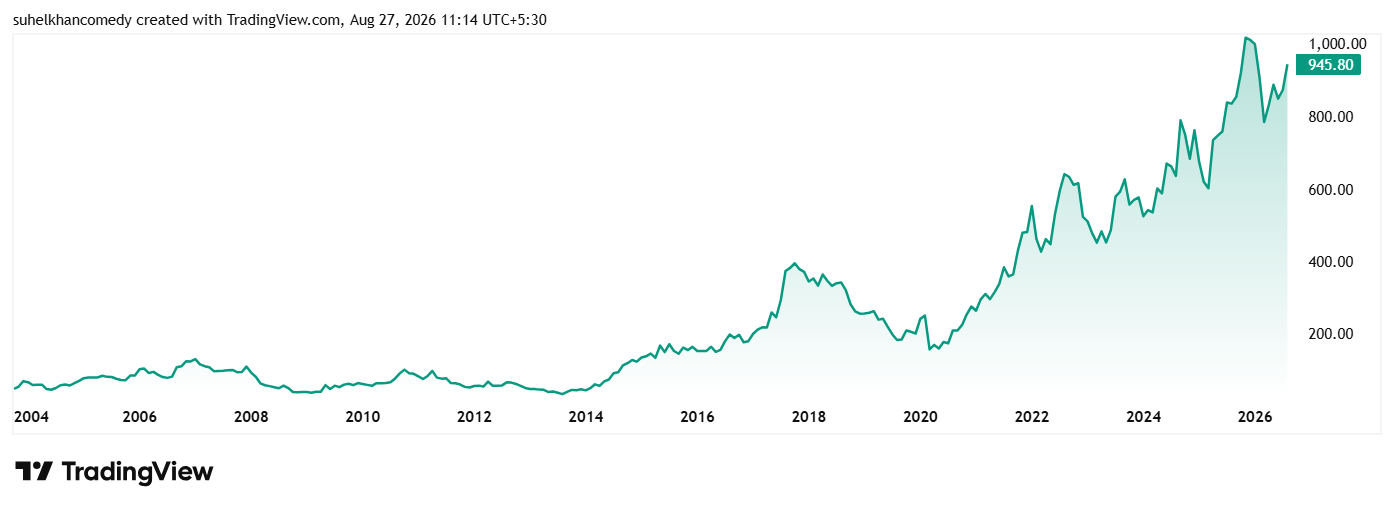
The stock trades at a PE of about 54x, which is not a bargain multiple for an auto components supplier. The case for it now rests on that new capacity earning rather than merely depreciating. The share price has compounded at 18% in the last decade.
#3 Elgi Equipments: The Cash Flow Compounder
Elgi Equipments makes air compressors, the machines that run pneumatic tools, paint lines and packaging equipment inside factories. The holding is worth about Rs 340 cr.
On raw numbers this is the strongest business of the five. Return on capital employed is 22.1% and return on equity 19.0%. Free cash flow in FY26 was Rs 348 cr, with Rs 454 cr generated from operations, comfortably above reported operating profit.
By the Numbers: How Elgi Maintained a 22% Operating Margin
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 1,924 | 2,525 | 3,041 | 3,218 | 3,510 | 3,951 | 16% |
| EBITDA (Rs cr) | 217 | 298 | 437 | 491 | 529 | 583 | 22% |
| Net Profit (Rs cr) | 102 | 178 | 371 | 312 | 350 | 430 | 33% |
EBITDA here refers to operating profit before other income. Operating margin has settled around 15%, up from 11% in FY21. The June 2026 quarter delivered Rs 1,062 cr of sales and Rs 103 cr of net profit.
The FII Exodus: Who is Buying Elgi Equipments Now
The ownership shift here is the most striking in the portfolio. Foreign institutional holding has fallen from 29.09% in March 2025 to 21.90% in June 2026. Domestic holding has more than doubled, from 4.98% to 10.12%. Individual shareholders have climbed from about 68,500 to over 89,000.
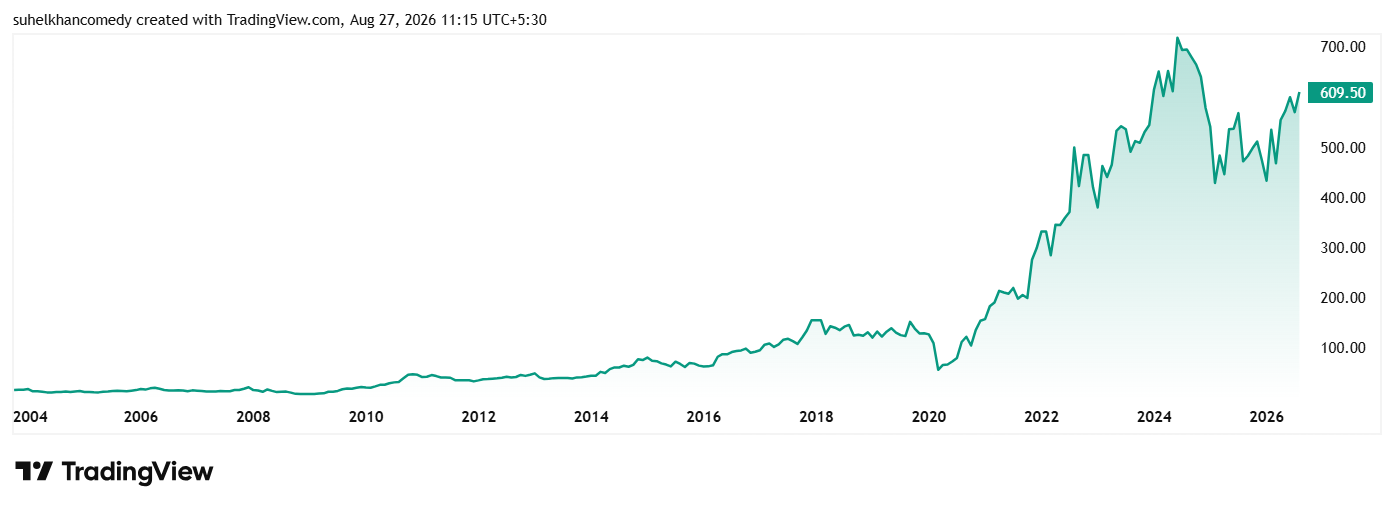
In August 2026 it launched a new compressor range in India and picked up an 18.01% interest in a small energy solutions firm for Rs 1.617 cr. The stock has compounded at 21% a year in the last decade and trades near the top of its range at a PE of roughly 42x.
#4 Bannari Amman Sugars: A Pristine Balance Sheet, A Struggling Trade
Bannari Amman Sugars crushes cane across five mills in Tamil Nadu and Karnataka, and also runs distilleries, cogeneration plants, windmills and a granite unit. The stake is worth Rs 130 cr.
The balance sheet here is impressive. Borrowings have gone from Rs 1,221 cr in FY15 to Rs 9 cr in FY26, and an investment book has been built from almost nothing to Rs 263 cr. Interest cost for all of FY26 was Rs 2 cr.
The trading story is not impressive at all.
The Revenue Paradox: When Profit Rises but Operations Contract
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 1,563 | 1,998 | 2,526 | 2,220 | 1,793 | 1,917 | 4% |
| EBITDA (Rs cr) | 211 | 218 | 304 | 306 | 210 | 198 | -1% |
| Net Profit (Rs cr) | 92 | 80 | 143 | 152 | 105 | 148 | 10% |
EBITDA here refers to operating profit before other income. Note the shape of these three rows. Operating profit has gone backwards over five years while net profit has risen. The FY26 net profit of Rs 148 cr was helped by Rs 43 cr of other income and an unusually low tax rate of 17%.
Sales for the quarter ending June 2026 were Rs 172 cr, down 59% from Rs 419 cr a year earlier. The company reported an operating loss of Rs 5 cr and a net loss of Rs 11 cr. Sugar has a seasonal off quarter, but the year earlier period was profitable on far higher volumes, so this is more than seasonality.
On 18th August 2026 the company received a show cause notice from the GST authority over an alleged input tax credit excess of Rs 29.76 cr. The annual general meeting is set for 23rd September 2026.
Ownership here is unusually thin. Foreign institutions hold 0.27%, domestic institutions nothing at all, and the register carries just 6,366 shareholders. Shah is effectively one of very few large outside holders, and the stock trades at a PE of about 41x, with the share price compounding at just 7% in the last decade.
#5 Zodiac Clothing: The Decade-Long Value Trap
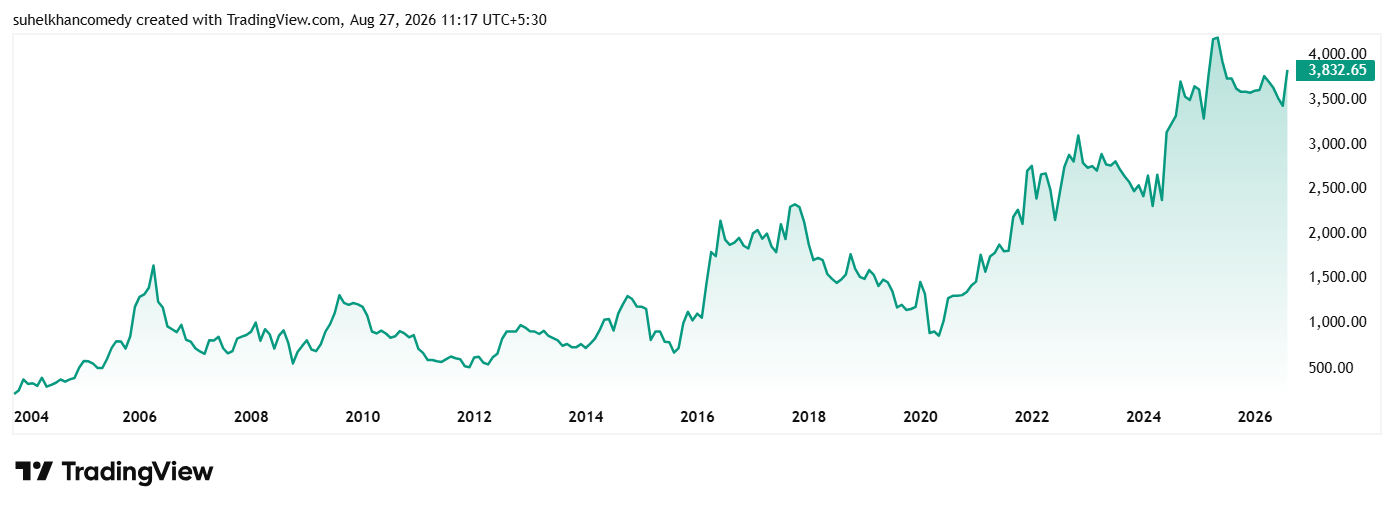
Zodiac Clothing sells men’s formal shirts, ties and trousers under the Zodiac, ZOD! and z3 labels, licensed from a promoter owned group company against a royalty of 1% of turnover. Shah’s 1.5% stake is worth Rs 3 cr, or 0.1% of his portfolio.
The decade has been brutal. Sales have fallen from Rs 391 cr in FY15 to Rs 162 cr in FY26. The share price has compounded at about minus 10% a year over ten years and is down about 25% over the past year. Reserves have eroded from Rs 283 cr in FY19 to Rs 155 cr. Return on equity last year was minus 18.1%.
Bleeding Fundamentals: Zodiac’s 10-Year Revenue Collapse
| Financial Year | FY21 | FY22 | FY23 | FY24 | FY25 | FY26 | 5Y CAGR |
| Sales (Rs cr) | 100 | 127 | 175 | 146 | 174 | 162 | NM |
| EBITDA (Rs cr) | -22 | -17 | -5 | -18 | -19 | -13 | NM |
| Net Profit (Rs cr) | -29 | -16 | 16 | -36 | -37 | -35 | NM |
EBITDA here refers to operating profit before other income. All three growth rates are marked NM. Operating and net profit are negative at both ends, so no compounded rate exists. Sales growth would read positive only because FY21 was a lockdown year, when sales collapsed to Rs 100 cr from Rs 191 cr. Over ten years, sales have shrunk about 7% a year. There is also no price to earnings ratio, because there are no earnings.
The June 2026 quarter brought sales of Rs 33 cr and a net loss of Rs 9 cr. Foreign institutions, who held 10.57% back in FY17, now hold nothing. Promoters have gone the other way, from 61.55% to 72.93%.
One thing has improved. Working capital days have fallen sharply, and the stock trades at 1.11 times book value, the only holding anywhere near its net asset value.
The stock price has logged a negative 10% compounded fall a year in the last decade and as already said, is trading at a negative PE as there are no earnings.
The Portfolio Paradox: Why Stillness Beats Screening
Put the June 2026 quarter side by side and the portfolio stops looking like one idea.
| Stock | PE | ROCE | ROE | June 2026 quarter |
| LMW | 113x | 5.6% | 4.1% | Profit Rs 56 cr |
| Asahi India Glass | 55x | 11.8% | 10.7% | Record 23% margin |
| Elgi Equipments | 43x | 22.1% | 19.0% | Profit Rs 103 cr |
| Bannari Amman Sugars | 41x | 9.3% | 8.0% | Net loss Rs 11 cr |
| Zodiac Clothing | Loss making | -8.0% | -18.1% | Net loss Rs 9 cr |
A note on method. A ten-year median multiple for each industry would be useful here, but that history is not available on a consistent basis across all five names. Rather than estimate it, I have left it out.
Four of these five would fail a conventional screen. One has 113 times multiple against a 4% return on equity. One just reported an operating loss. One has lost money for most of a decade. Only Elgi looks straightforwardly good.
And yet the book has not moved.
The True Lesson of a 10-Year Hold: Market Discipline or Stock Illiquidity?
Holding for a decade is easy to admire and hard to copy, because it means owning the bad years too. It means watching a position fall to Rs 3 cr and not treating the exit as urgent. Anyone can hold a winner. Asahi has just been vindicated after two years of looking like an expensive mistake, and the reward arrived in a single quarter, seven quarters late.
There is a less flattering reading too. Some of this stillness may not be conviction at all. A 2.6% stake in a company with 6,366 shareholders is hard to exit without moving the price. A Rs 3 cr position in a Rs 203 cr company is barely worth the effort. Concentration and illiquidity can look identical from the outside.
Which is why the useful takeaway is not to copy the list. It is to notice how much of what looks like genius from a distance is really the absence of activity, and how rarely that absence pays off on a schedule anyone can plan around. Adding these names to a watchlist and following the next few quarters will teach you more than the holding table ever will.
Disclaimer:
Note: We have relied on data from http://www.Screener.in and http://www.trendlyne.com throughout this article. Only in cases where the data was not available, have we used an alternate, but widely used and accepted source of information.
The purpose of this article is only to share interesting charts, data points and thought-provoking opinions. It is NOT a recommendation. If you wish to consider an investment, you are strongly advised to consult your advisor. This article is strictly for educative purposes only.
Suhel Khan has been a passionate follower of the markets for over a decade. During this period, he was an integral part of a leading Equity Research organisation based in Mumbai as the Head of Sales & Marketing. Presently, he is spending most of his time dissecting the investments and strategies of the Super Investors of India.
Disclosure: The writer and his dependents do not hold the stocks discussed in this article. The website managers, its employee(s), and contributors/writers/authors of articles have or may have an outstanding buy or sell position or holding in the securities, options on securities or other related investments of issuers and/or companies discussed therein.